Friday, September 10, 2010

The soundtrack of my life

I had this gigantic mp3 player - one of the first few generations of mp3 players, I proclaim proudly - from iriver. It is one gigantic piece of awesome, orgasm inducing music device, though it looks like a brick since it's essentially a harddisk. Not as sexy and slim as ipod...gosh, it does not even come with colours (it's only black fonts with blue background). I bought it for nearly 700 bucks for 10 Gb of storage and it's mine, so I loved it very much :)


Recently I brought it out of cold storage to listen to the songs I had inside. Usually I listen to songs by albums, put in the exact sequence as laid out in the album. If the artist and album producers decided that there is some magical rituals in putting the song listings in a particular way, who am I to say it's not? But yesterday, I put it to random shuffling, so instead of listening to albums one by one, I listened to my treasury troves, well, randomly.


I've always thought of producing an album known as my personal soundtrack. It's like the movie sound track of LP's life story. There are certain music that define my existence here on earth. When I was in primary school (the defunct Bedok View Primary school), I was quite into Chinese music. 特别的爱给特别的你 by Sky Wu, 蝴蝶飞呀 by Little Tigers and 红尘有你 by Wang Jie are very representative of what I listen to. I was humming my way into PSLE with these songs as the backdrop or playing hopscotch with these soundtrack. As it was my first foray into the vast universe of songs and pop culture, these songs are very very significant to me.


After that, I went into Maris Stella and had a musically unfruitful 2 years of my life. I was busy adjusting to the new pace of life and didn't have much joy to listen to music. It was the 90s and the beginning of funky hairdo, bold makeup and shoulder padded blouses. And Michael Jackson. I love to buy those big compilation cassette taps and CDs, titled suitably as Mega hit X (where X is a set of integers greater or equals to 1). I was trying to find my musical direction, so I sampled all sorts. There's the very lovely It must have been love by Roxette and (Everything I do) I do it for you by Bryan Adams. I love Bryan Adam's husky voice and his unique way of singing. I practically rushed home to listen to this song in certain periods of my secondary school live. I remembered 'ripping' (if you can call copying songs from cassettes to cassettes ripping) songs into my own personal compilation albums, songs like Paint my love by Michael learns to rock, the very long title by Meatloaf - I'd Do Anything For Love (But I Won't Do That), Soul asylum's Runaway Train and a little bit of Chinese songs. I'd changed my taste from chinese to english songs by secondary school but it'll be a sin to forget about Kit Chan's 喜欢你, 心痛 and 伤心. About the only local Chinese artist I like is Kit Chan. Much more than Stephanie or JJ anyway.


And people wonder why I've a melancholy nature. I supposed years of listening to love songs made me as such. There are 3 classes of love songs - the longing for love (She will be loved by Maroon 5), the joys of being in love (I want to hold your hand by Beatles) and the heartbreaking of love (I will survive by Cake). Each can be sub categorized into more subtle differences, but you get my point. Somehow, I always loved the type 3 class of love songs. So am I melancholy because of love songs, or I listen to love songs hence I became melancholy? I lean towards the latter.


I kept a lot a lot of cassette tapes depicting my secondary school life but sadly those didn't survive. A cruel woman in my home threw them away when I went to army. I remembered being devastated for a quite some time when I cope with the sudden loss of that important part of my life, my memories. How can someone throw other people's memories away? I forgive her but will never forget about it.


I went on to Temasek Junior College and was during the 2 short years, I have only 2 groups of artist that interests me most. Faye Wong and Cranberries. Especially cranberries. Most especially cranberries. I was practically listening to the CDs for most of my life in JC and it is definitely my soundtrack during the 2 years of my life there in TJC. It's my first 'heavy' music - Zombie. Ode to my family is very significant to me because I was humming that during my promos and A'lvls. It has that calming effect on me. Who can forget Linger and Dreams too? I loved this kind of enigmatic voices, so on hindsight, I think Faye Wong is the equivalent chinese verson of that obsession with this particular kind of sound. I bought the very expensive Faye Wong album in JC1 that costs me 30+ bucks at that time. I particularly loved the song 其子, which is the soundtrack of one of the TV movies made by SBC/TCS/Mediacorp (whatever name they call themselves these days, I can't keep track). Actually in the past she used the name Huang Jing Wen, as opposed to the more populist name Faye Wong now. I only bought two albums by her, one is the  天空 album and the other is a canto compilation.


There are little pleasant distractions like 愛相隨 by Emil Chau. It was not until very very much later that I discovered what I really like about music in general. As long as there's a guitar strumming, I would love it. I only knew that much much later in university around 2-3 yrs later. It's interesting to look back though, as I explored the wider universe of music. My classmates are all hot about Zhang Xin Zhe (Jeff Chang), though I'm not. I don't really like high octave male voices, haha :)


I think that marks the real end of my Chinese music era. No more Chinese music from there on...just the occasional songs here and there (I call it a one night stand with that artist). Just love and bye kind of thing.


Out of a philosophical thinking that my life cannot be suitably compressed into one blog post, I decided to blog about my soundtrack from army to the present time in another blog articles. If my soundtrack only lasts one post, it'll be a boring and short movie. Neither do I want it to become a long and draggy Lords of the Rings trilogy (seriously, who ever wants to watch the Return of the King twice? It's so draggggyyyyyy...). Yes, yes, 2 posts should be enough.
Tuesday, September 07, 2010

Why I don't blog about the stock market anymore?

Someone mentioned in the cbox (the 'infamous' cbox as AK puts it) that how come I don't blog about stocks and shares these days. If you look at the recent posts, it's all about my ramblings and rantings. Whine whine whine...occasionally there'll be the personal finance or insurance topics that interests me greatly, but almost nothing about stocks or shares.


I don't know if this is a good thing or a bad thing for I suspect that it'll happen to all bloggers one day. Those who felt it but survived gone had gone on to greater heights. Those that felt it and did not survive, well, let's just say their blog's natural lifespan had been reached. I'm sure there are plenty of names in the blogosphere that had its day in the past, but had been gone by now. It's like there's an nuclear explosive - one day it's normal blogging as usual, then the next, only the site remains but there's no more updates. I suppose some blogs even had their infrastructure 'destroyed', meaning that the site can no longer be found and had been taken out with their contents erased.


So...you hear it from me first. I'm no longer as interested in stocks as I had once been in the past. 'No longer interested' is relative, of course. I'm still more interested in stocks then my gf ever will be (haha). Comparing myself in say 2 years ago and the present me, I think the present me is more disinterested and bo chup about the whole market thingy. I mean I still read about market news and read charts and all, but that's because I had to and not because I am inherently interested in it.


It's interesting to note my level of interest waning. It's partly due to my disillusionment about reading books. After you've read shelves of finance books in the library, you'll find that if you've read one, you've read all (figuratively, don't take it literally). The concepts are nearly all the same, so occasionally you'll find a gem that blows your mind, but those are rare and chances are you'll be more likely to find another book that sounds like the one you had read. Food gives nutrients to the body and books gives nutrients to your thoughts. I guess I'm weary about reading finance books now, so my thoughts are seldom about the market.


However, not being interested is different from not having to do it. I think I'll have to do it whether I'm interested or not, as opposed to say putting money in a bank. So while I am practically doing the same stuff with regards to the market as before (I think perhaps more stuff, since I do read charts everyday), I do so without the passion I felt when I first found out what is value investing, what is MA lines, macd histogram... These days, I'm more interested in freeing up my time to do what I like to do, be it playing games, reading or just watching youtube.


Another significant reason why I don't blog so much about the market is that there are people who are doing very much better than me. You can find all their blog links in my site on the top and on the right. Their articles are so much more insightful and more detailed than I can ever do, so I do not see the reason for repeating or trying to re-invent the wheel. I acknowledge that I'm not the best chartist/trader/investor - that much I know. Hence, there's no need to pretend to be good in it just so as to generate more viewership. I'll take a step backwards and try to facilitate traders and investors to meet up in the infamous cbox of mine and to exchange views. That I can do.

Wednesday, September 01, 2010

Embracing our differences

I came upon this realisation that me and my gf have very different ways of doing things. It's not that I didn't know that after being together for so long, but rather during these few months of working together on a single project (i.e. our wedding), our differences are amplified and presented to us starkly. In the past, we settle our own projects and seldom have any interference from each other, so the inherent differences in our methods of doing things are thus hidden from view.


She's more of a feeling kind of person, meaning that she'll only do things when she feels like doing so. No amount of pep talk or well laid plans can persuade her to do otherwise. Me, on the other hand, prefers to come up with a plan and stick to it no matter what happens. So often times, when I'm hurried to do something as laid out by my plans, she'll amble along half-heartedly while waiting for her feeling to come, before she'll do it. It's been quite frustrating for me, but no longer.


Disciplined and structured - my way of doing things sounds like the military


Why? After some serious reflection, I thought that it's no point trying to force another person to adopt my way. She had her own successes doing things her own way, so do I, so why should she change to suit my need so that things go 'according to plan'? Besides, after nagging at her to do things for weeks, there's still no progress, so I might as well try another tack. I think it's because of this constant pressuring on my part that causes some arguments between us, and ultimately, I'm the one who feels even more stressed up.


I think if we shine the light of reflection upon ourselves, and stop seeing others as being the problematic one, it'll be the start of a new understanding and cooperation between the parties involved. This kind of concept is easy to read but hard to apply. Therefore, my epiphany that our differences are to be celebrated is both liberating and stress-relieving.


According to her, things that need to happen would happen, so there's no point rushing it. I would bear that in mind and perhaps adopt her free-style way of doing things. Seeing how she's so happy go lucky, perhaps I really should look into the advantages and disadvantages of my disciplined way of handling matters.

Friday, August 27, 2010

Tuition nation no more?

There's recently a lot of forum letters on the subject of tuition in Singapore. Tuition is so pervasive here that it's a shadow education, as opposed to the more formal educational institutions. I think the phenomenon is quite common in asian countries, with taiwan, HK and korea being many more times more pervasive than here in Singapore. I heard that in Korea, where the kids are sitting for their entrance exams, even airplanes have to stop flying in the duration of exams to avoid disturbing the kids. You can imagine the booming tuition business there since they are so focused on exams.


My views are naturally biased, since I'm a part of this love-it-or-hate-it industry. Some students found great benefit in tuition, because it's a much more effective means of getting to master subjects. Of course you can explore yourself to reach the same mastery level but it'll take time, and tuition can help students reach this level in the shortest time possible. But some people complained why teachers cannot do the same thing in school? After all, the kids spend more time in formal lessons in school than in tuition, so shouldn't more learning be done in school than outside during tuition?


Tuition can break your piggybank in Singapore


I think there are a few reasons why school teaching is less effective:


1. There are many more students in school classroom than in a tuition class. If you join a tuition class with as many students as there are in school classroom, you should seriously consider finding an alternative. I think teacher-student ratio is the main reason why tuition centres are flourishing. It's quite impossible to learn when you have a teacher juggling with different learning capabilities of 40 odd students in class, within say 30 mins a lesson. It's possible to do it, but it's rare to encounter it.


2. There are many distractions in school. Kids behave differently in the company of their friends and when they are in the presence of 'adults'. Put 40 kids together in a room is bound to be a testing experience for any teachers. I believe a lot of time is wasted doing disciplinary actions and on administrative matters. What about tuition? You go in, you start a lesson, you end it, you go home.


3. This point boils down to the teacher-student ratio again. If the ratio is high, meaning there are more teachers than students, there is more attention. After so many years doing this, I find that the greatest advantage of tuition lies in 1-1 kind of setting. When someone experienced is there to observe the student's reaction to the things said in the textbook, the learning is made more effective because adjustments can be made on the fly. Basically I spend a lot of time observing how the student react to a question and when I impart content to them. From their observations, I will change my teaching on-the-fly and make decisions as to whether to elaborate more, or give more examples, or go back to the previous chapters to revise certain materials before moving on. It's different from asking the student to read the textbook himself because the teacher in the classroom cannot possibly help out the individual needs and concerns of every student. A small class size of maybe less than 5 in tuition can do the trick too.


As I was reading the letters, the first thought that came to my mind was that if my career is going to be jeopardized. If so, I will need a backup plan. As I talked with my gf and analysed the situation, I find that it's hard to do away with tuition, at least not in the next 5 yrs. Perhaps more regulation in the sense of asking tutors to register with an association might be in the pipeline. So what can I do in the event that the whole industry - my livelihood - is threatened?


No way I'll be an engineer. Most likely I'll join a formal institution to carry on what I've been doing all along.

Thursday, August 19, 2010

Random thoughts

Once a while, I gathered all the thoughts that I had in my mind - those that are worthy enough to blog but not long enough to write on a post by itself. For me, it's therapeutic to blog down these random thoughts. I love blogging, it converts formless thoughts in my head into concrete words. The act of converting them into forms that others can react to is itself a joy to me. Sometimes, when I write along, more thoughts will form to give framework and structure to my initial spark that prompted the blogging in the first place.


Random thoughts:


1. Why do I get the impression that FA guys are more critical of TA guys but not the other way? It seems like there is a universal disdain for the use of charts and indicators by those who walks the investing pathway. On the other hand, those who practice TA would think (in my impression, of course) that knowing the fundamentals of the stocks they are trading would definitely be of some value to their craft.


2. I think there are a lot of mindset differences between a self-employed and an employee. Speaking from my point of view of being self-employed for 7-8 yrs, I am always trying to initiate something. I've to look for work all the time, instead of letting it be arrowed to me. I've to handle my career image well and to constantly look out for ways to improve and get more work. I wonder how someone in the employee path will do. From what my friends told me, they seem to be avoiding work if and when possible. Innovation isn't that well regarded if your boss don't recognise it. Besides, if you initiate a project, you might not have any personal benefits at all.


I don't think I'm can be a model employee. I hate bureaucratic paper pushing and will never do well in such environment.


3. I don't think you have to ask someone how well they do in the market. If they make a profit, they would open their floodgates and tell you all about it, if you only allow it. The sense of joy and happiness when they win something cannot be contained easily. The same goes when they lose money in the market. A general sense of gloom will prevail and they are generally more quiet. The same cannot be said for those who had been in the market for a longer period of time. They generally have a calmer disposition and are immune to both the joys of winning and the pains of losing.


If I've the time, I would so wish to sit at the financial districts and watch whether people lose or gain money just by observing them. It'll make an interesting study.


4. I've saved accordingly to my target for the past 8 months. Another 2 more months of savings and I'll have finished my savings target of 50k. This would be the second time I'm doing this and I'm getting quite used to it. This system, though tough and demanding, does have it own advantages. The most obvious one is that I got to enforce a certain discipline to how much I can spend in a month. The not so obvious advantage (it even surprises me) is that I can know how much to work. Before I had this system, I was always trying to work a little more, save a little more without a fixed goal. Thus, being much a workaholic, I take work as it comes along. These days, once I reached my monthly saving goals, I tend to cancel lessons so as to take breaks to walk further. My journey ahead is long and winding, seemingly no end. Thus, I cannot afford to burn myself out prematurely. A break every now and then is crucial for my mental well-being.


I'm so looking forward to my end of the year trip to anywhere, to take my long deserved break from the bondage of work.

Wednesday, August 18, 2010

Security

** "BIAS" is a special feature in my blog where I get to say whatever I want with scant regards for your feelings. I'm not politically correct in this feature, so go ahead, judge me."

I was quite frustrated on last Sunday when I was out for work. As a result of this, I was particularly skeptical and thoughtful about things. In hokkien, this is called guai lan.


On that particular day, I was going to a condo. Actually there are two sorts of condos, one is with a laxer security and the other with more oxymoronic security. This particular one that I visited last Sunday was of the latter kind. By right, all the security guards have to ask any visitors to sign on the guest list, putting down details like:


1. NRIC and name
2. The unit to visit and the purpose of the visit
3. Time of entry
4. Signature


By principle, I do not see a point in giving these details. Firstly, I do not know what they are going to do with the book after it's finished. There are a lot of details that are personal and there is a risk that these private information can fall on wrong hands. The security guards watch the premises, then who watches the security guards? Secondly, there is no confirmation by the security guards that these details are even correct in the first place. If the purpose of writing these details is to catch those who are going to do suspicious things, then obviously it wouldn't work. Normal guests who fill in honestly will not do suspicious things, suspicious characters going in will not fill it up honestly.


As such, I always walk in as though I'm the resident of the condos. If they stop me, then I'll fill up, but in such a scribbled form that it satisfies their request but yet at the same time, does not yield any information. I think I'd even wrote an NRIC like S1234567 and it went through. If they are happy, I'm happy.


So on last Sunday, this security guard stopped me from going into the condo premises. He asked me rather rudely to sign in. I asked him why I should sign in. He was erm...ah... I think he had never been asked this question before. Then he replied that since I am an outsider, I must sign in. Then he waved vaguely behind him that there is a camera and it will track me.


Do you know why security wears black? They are trying to blend into the background to be non-intrusive


Do you know why there is rain? It's because there is water up in the sky so it drops down. It's a non-answer to a question.


If I had more time, I would request politely to meet up with the management concerning the security of the condos to ask them the questions that I had in mind with regards to filling in my details. You know what's the funny thing? I've been there for a least 2 years and had entered the condo at least 1-2 times a week. There is no excuse for not having seen me around. He is not doing his job well because the best form of security is based on a non-intrusive kind of scrutiny - you observe the people that comes in and recognise the familiar faces (either resident or not), sieving out the unfamiliar faces and observing them further.


I had been to condos in Orchard area and they are in familiar talking terms with me. Sometimes I'll just chit-chat with them and they tell me gossips about this and that. So I know that it can be done and it had been done in other places. It's just how individuals treat their job that distinguishes them. I've also know this particular MRT security lady (those that stand near the gates to check on luggage and bags). She never fails to strike up conversation with anyone whom she stops to check their belongings. My gf chatted with her for 30 mins before, so I know.


You know the saying, the best bodyguards do not use weapons? I think it can be applied to security too. The best kind of security is subtle and non-intrusive. It is based on a network of relationships so strong that if someone tries something funny, the people involved in the network will try their best to stop them simply because they view the other people as part of their own flesh and blood.


I could be idealistic, yes, but then again, I'm very guai lan that particular day, so I don't care.

Monday, August 16, 2010

Old people don't need life insurance?

I was browsing through some of the blogs when I saw Mr Tan's post on insurance. It's his usual style to advice people to buy term and invest the rest. But that doesn't attract me - it's this line:


"There is no need for people to have life insurance when they are old."


By 'life insurance', I take it that he means the whole life variety - those plans that gives a lump sum pay out in the event of death and total permanent disability of the insured person from the inception of the policy till age 100.  This is very different from the very much cheaper term plan where a similar lump sum pay out will be paid out but it is usually up to age 65. However, life insurance these days come along with a critical illness (CI) rider that allows a lump sum payment when it strikes. Since this rider 'rides' onto the main plan of the whole life, which is up to age 100, the CI cover will also be up to age 100. I am under the impression that CI stand alone cover up to age 100 is either exorbitant in price or does not exist.


What do we need when we're old?


I think we need a comprehensive, as-charged hospitalization and surgery plans (H&S) that covers the expenses if you are hospitalized. The key word here is that you must be hospitalized locally, otherwise the H&S plans do not cover them. Some had mentioned that instead of using the CI cover that is usually attached to whole life plans these days (and covers up to age 100), we can use the H&S plans to replace CI cover from age 65 and beyond. While it's true that H&S plans cover treatment of CI, it's also relevant that H&S covers expenses ONLY if you're hospitalized in local hospitals. If you remember Charmaine's case, the little girl had to seek alternative cancer treatment overseas because the local hospitals do not have this particular drug (pardon me if I remember the details incorrectly). The cost turns out to be 350k USD and this huge sum definitely cannot be covered in the H&S plans unless you bought one of those special ones (not to forget, expensive ones) that covers overseas hospitalization bills as well. A lump sum payout by the CI rider will be very helpful in such cases. Even if it's not for overseas treatment, the lump sum is good for covering expenses related to the critical illness outside of hospitals, which is currently not covered under the H&S plans.


(Of course, you might not be able to claim your CI even if you have CI, particularly with regards to cancer. This is because of the very stupid clause where the cancer had to be in the ending stages. I ask, if it's in the ending stages, why seek treatment? If it's not the ending stage, how do I get the payout to seek treatment? Catch 22...)


I've no idea why the doc and the man is so happy with the latter throwing away his money


Do old people need death payout? It's perfectly correct to say that when we're old, there is no more dependents. If your life insurance is planned for your dependents, then obviously you do not need it when there are no more dependents. In that case, getting a term plan is perfect because unless you have a kid beyond age 40, by age 65 your dependents would already have become independent. This makes the life policy meaningless. What about the cash value of whole life plans? It's really nothing much to shout for, because if you invest in equities related instruments, you'll probably end up getting more (or losing very badly). If you need to invest, don't buy a whole life plan obviously.


It thus appears that the one redeeming feature of whole life policy is the CI cover up to age 100. I faintly remember someone mentioning that if you start savings now and invest it wisely, by the time you need it after age 65, you can self-insure the costs, especially if you bought yourself a good H&S plan. What if I can't save enough or what if my savings are all lost in the bear market? I would insure against that possibility with a few layers of defense:


1. A fully paid up whole life plan with sufficient (but not overly high) CI cover to protect my savings from age 65 to age 100. This is to reduce the premium so that I can sustain the costs of maintaining the policy, which is not going to be cheap compared to term plans.

2. A good amount of savings.

3. Be darn good to my children so that if I need them to take care of me and I have the financial means to fund it, filial piety can be quite a given. These days, one has to provide the conducive environment for children to be filial - by being a good natured senior citizen and a financially 'okay' senior citizen.


What about now to age 65? Get a term plan lah, it has depth of coverage but do not have the length of coverage. Who says you have to buy term and invest the rest only? You can buy term, buy whole, save up and invest!

Friday, August 13, 2010

Marriage is NOT wedding

** "BIAS" is a special feature in my blog where I get to say whatever I want with scant regards for your feelings. I'm not politically correct in this feature, so go ahead, judge me."

Wedding is such a sham!


I've been having a rather bad week because I can't sleep well as my mind is still very active at night. I attribute it entirely to the stress of settling matters pertaining to the wedding preparation. There's a thousand and one thing to arrange and tie up with others and a million others to call up and wait for their reply before you can proceed on. It's really such a hassle! I have no romantic views on wedding and as far as I'm concerned, the marriage is more important than the wedding.


Is there a difference between marriage and wedding? I don't know if there's an official one, but I am going to make a distinction between marriage and wedding. Wedding is a one day event (but the preparation is  definitely not just one day!) where you showcase yourself to others, but marriage is a commitment (legally a contract) between the couple according, but not bounded only, by the marriage vows. I think the most important distinction is that marriage is a lifetime commitment but wedding is just a one-off incident. I might want to hold several more weddings in my lifetime but I only want just one good and long-lasting marriage.


You prepare a year ahead for the wedding so that it will run smoothly in just one day, but you say your vows and sign the papers in less than 30 mins but you are united together for a life time. That's how stark the difference is. For me, I'll concentrate on working on my marriage by ensuring that living together is made emotionally and financially possible. For my wedding, I'm just trying to reduce the cost so that my marriage life can proceed with more savings to pay for the COV and renovation. I'm very glad that my gf shares with me the same ideology and is not caught up by the rituals and rights of the wedding religion. Most people that I know prepare their wedding with 20 times my enthusiasm and energy, but of course, that's their point of view. I think it's only a problem when they try to tell me what a 'proper' wedding should be like.


Take the example of the bridal shop that I visited not too long ago to choose the photos for my wedding album. I was offered 34 poses and 28 pages for a package price of around 3k+. When I had to pick from nearly 200 pictures, we proceeded surgically. The salesperson told us usually it'll take 3 hours minimum to choose the photos but I think we took around 1.5 hrs. The salesperson also tried various methods to tempt us to part with another 1k+ to include more poses/pages in the album. I must say he looked visibly disgusted when we literally cut the amount of photos on the table by 70-80% (i.e. out of 10 photos, we threw away only 8). He then told us what other couples did blah blah blah...


I think many would have succumbed to their partners wishes to include more photos because it's "once-in-a-lifetime" event. Out of respect to some of my dearest friends who uttered the same cliche, I would refrain from discussing why wedding is not such a romantic "once-in-a-lifetime" event.


Going to take a nap now....

Wednesday, August 11, 2010

Living simply

I was quite intrigued by Bro8888's article on living with 100 things only. It's not so much about the number 100 that matters, it could easily be 200 or 1000 articles. Rather, it's those type of questions that when asked, will lead to more questions that will shine light on what really matters to you. It's something like one of the question that Mr WB had asked - if you only have 10 stocks that you can buy in your entire life, which one would it be? Something like that lah :) This kind of question forces one to think about what is really important.


When I told that question to my gf in a cafe for dinner, I replied my own question. I said that I would be quite sufficient to have what I had brought with me when I met her for dinner. This is what I had then:


1. A columbia heavy duty haversack bag
2. My highly durable Nalgene water bottle
3. My pencil case with stationary inside
4. My organiser
5. An umbrella
6. HTC handphone with internet data connection
7. Wallet with the necessary cards inside, for withdrawal of cash, transport and credit purchase etc..
8. Whatever clothes I'm wearing + Jeans. Definitely a pair of hard, worn out jeans
9. My super durable Clarke shoes that I had been wearing for 16 months now
10. Old casio watch with alarm and light


If I can bring along my kindle dx, I'll be even happier. If I have to travel, these 11 odd items will be sufficient for me. A laptop / desktop would be nice but not really essential. These are the objects that I really need in life. Life can be so simple if you limit the number of personal belongings to a certain digit. I think that's really what the original article is trying to point out.


But I guess having those articles with me wouldn't do. While I do not need a lot of material comfort, I do need emotional comfort. I need my gf with me, I need my close friends around me and family as well. There was a time where I was obsessed over a scratch on my new watch or my new phone but I had grown over it. I think one of the most important thing is to distinguish between objects and people. Objects are replaceable but people are not so easily replaceable. If a child drops your ipad, would you rush up to tell her that it's alright or would you give her a good scolding for damaging your new gadget?


As I age, I realise that I do not need a lot of things. There are a few things that I wished to get but the desire wanes over time and I ended up not buying it. There's this headphones that I wanted to reach aural orgasm, this particular graphics card that would make my gaming a few notches higher, this gaming console that would provide endless fun, this electric guitar and awesome amplifier that churns out insane riffs and this hot car that would make my travelling so much more fun and convenient.


Nah, maybe not anytime soon. I'd rather work less and acquire less of such things than to use my limited time to work to save up for it. If the desires boils up to a need, then I'll get it. If the desire boils up until it dries up, so be it. I'm still the same person with or without it.

Friday, August 06, 2010

My experience on using credit card

If you've been following my blog, you'll know that I've trouble applying for credit cards. It's a miracle that I got the POSB credit card when I applied a few months ago. Miracle because all the other cards have rejected me, despite the aggressive sales person pushing the cards, touting them as free.


After a few months of purchasing things on credit, I have very positive comments about it. I'm sure everyone knows about the dangers of bursting your own credit limits and going into debt blah blah. There are very good things to say about credit cards based on my limited experience.


1. It improves my cash flow.

Interesting isn't it? How can being in debt increase my cash flow? Firstly, you must understand that my work does not give me a nice pay check at a fixed date every month. It comes in bits and pieces throughout the month. Sometimes, because of the amount of money I diverted away from my spending account for savings, I do not have much liquidity to pay for things until my 'paycheck' comes in. Thus buying things on credit allows me to have slightly less than 1 month of interest free money for such spending. I especially like how I can control the date in which I have to pay my bills (of course, I pay in full before the due date), thus offering me a lot of freedom to control my cash flow.


I don't think people with a fixed paycheck will understand fully what I meant, so this advantage of having a credit card is no big deal for them.


2. I get points to offset my purchases.

This is not a big deal for me. Since mine is a POSB card, there are cash rebates for spending using the card. So far, I've got less than $10 rebate after using it for 4 months...really no big deal. Nice to have it, but really not essential. Perhaps after some super big expenditure like buying tons of furniture or wedding banquet, would I realise the benefit of having cash rebates. I'll know it soon ;)


3. Great discounts at selected places

I think this is fantastic. Sometimes, by flashing your cards, you get a lot of freebies that spending cash would not entitle you to have. I am often puzzled by how credit card companies manage to pull off such a deal for their customers and what the restaurants that offer such treats got in return. More business? Either way, I'm not complaining. I'm eyeing the buy 1 get 1 free lunch buffet at the chatterbox to see what the famous chicken rice is all about, haha :)


Of course, this post is not to encourage you to start swiping your cards right now. There are two sides of a coin, and thus a credit card is just like a tool - whether it's good or bad depends on how you use it. To those that have been scared by various literature that having a credit card is very risky and you can go bankrupt - yes, it's true, but it all depends on the user.

Friday, July 30, 2010

Cats or Dogs?

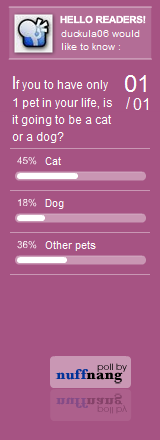
I made a poll not too long ago, so I think it's appropriate to conclude it after 1-2 weeks. After a turnout of 11 responses, here's the results:


It's quite surprising to me because I thought more people would love dogs, judging by how people treat dogs as a better companion than cats. Nevertheless, cats win this time round!


In my line of work, it's more usual for me to encounter dogs than cats. I've only have 1 household that keep cats (but they also keep dogs)...1 out of so many many household over so many years! But pets are cute actually, I've befriended quite a few dogs. Whenever I go over to the place, they would recognise me and greet me in the usual dog fashion :)


Here's some cute and funny pictures that I snapped using my lousy hp camera:


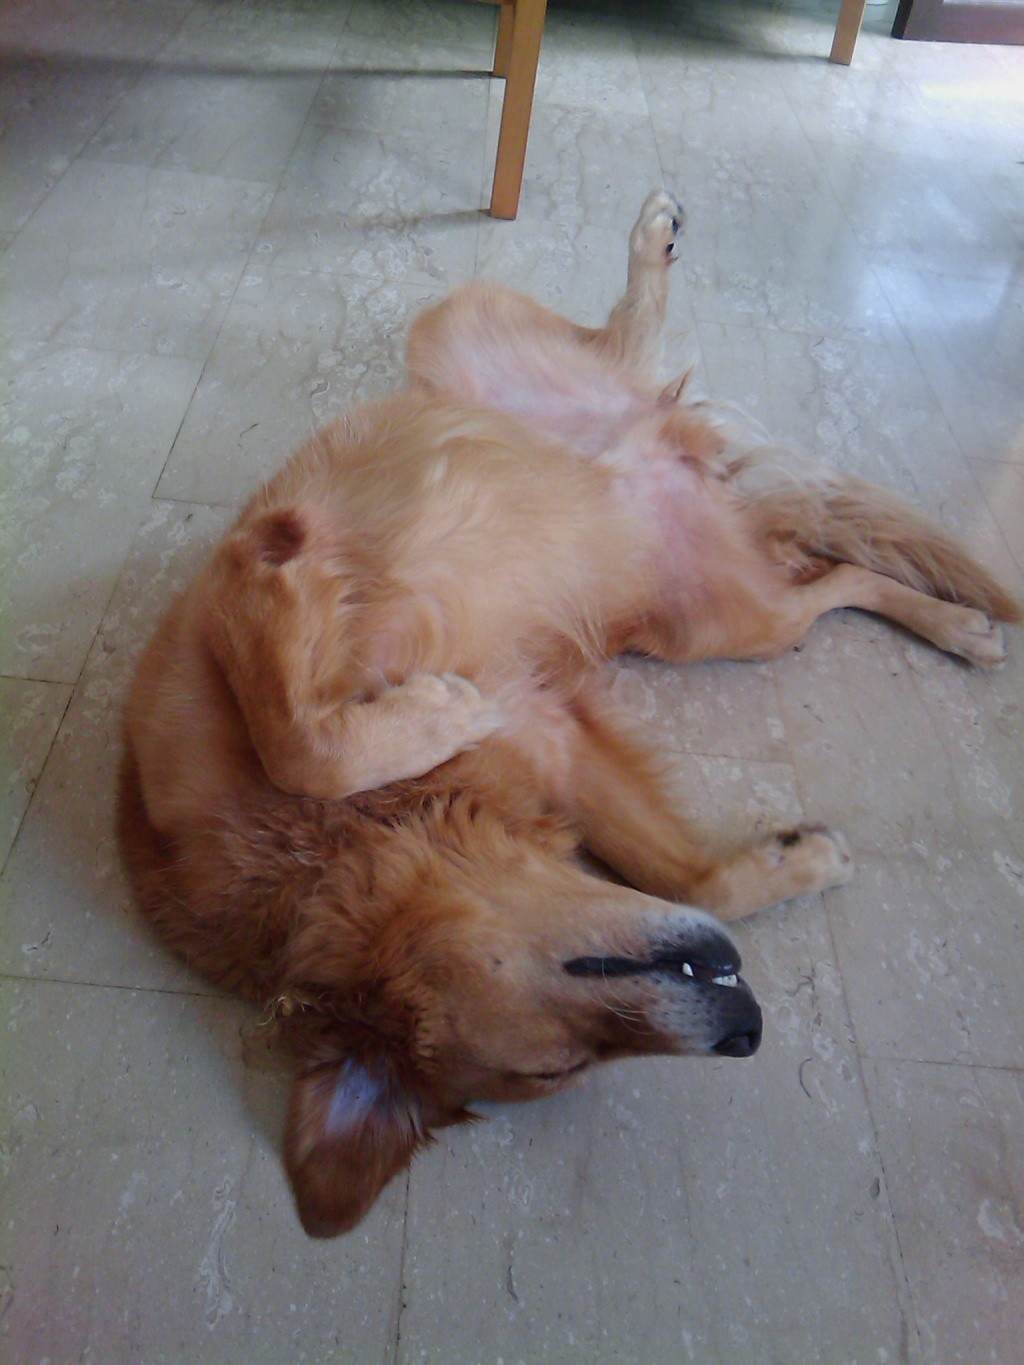
Erm...let sleeping dogs lie?


The above picture is a very funny picture I've seen of Mikey. When I first met him, he was growling at me. But after getting to know each other for sometime, he would greet me by grabbing his favourite toy and follow me around, before lying down to sleep near me (and the student). This is one of the funniest pose I've seen Mikey do. I thought cats would do this kind of funny pose, apparently I'm wrong :)


A bundle of fur in a corner of the lift

This is a very very interesting cat. She would follow people to the lift and would stay in a corner to sleep, riding the lift up and down. I call her the lift cat. She had caught me off guard twice, when after a tiring day of work, I entered the lift and see a bundle of fur all cuddled up in the corner of the lift. How can my heart not melt and give it a cat's rub?


Ah...the simple pleasures of life.

Tuesday, July 27, 2010

The Lioness

Recently I had put the ebook Aesop's fables into my hand phone to read during those little bits of time like waiting for buses and mrt. Since the stories are pretty short (most are around one paragraph) and full of meaning, I can spend the time reading a few stories at one go and reflect on them as I travel (I can't read while travelling on buses...makes me giddy).

Here's one that is striking to me. It's called the Lioness. Here goes:


A Controversy prevailed among the beasts of the field as to which of the animals deserved the most credit for producing the greatest number of whelps at a birth. They rushed clamorously into the presence of the Lioness and demanded of her the settlement of the dispute.

"And you," they said, "how many sons have you at a birth?" 

The Lioness laughed at them, and said: "Why! I have only one; but that one is altogether a thoroughbred Lion."

The value is in the worth, not in the number.


One good one is sometimes better than many lousy ones


It's particularly striking to me because it reminded me of the past folly that I've made when I'm a newbie in the market. I used to associate more with better value. Since I have limited capital, I would want to buy as many shares are possible with my capital - that would mean the shares I bought almost always pennies. The underlying thought process is very simplistic - why buy 1-2 lots of blue chips whereas you can buy 10-20 lots of pennies.


I did not see the worth of the stocks in its intrinsic value. Hence when I was introduced to the concept of value investing, I was suitably intrigued by it. It was easy to understand but I didn't think of it that way. It took several more losses in penny counters  before I was convinced that pennies are just not suitable for my liking. I prefer the relative stability of blue chips these days and am wary of anything less than 50 cts in price.


Of course, pennies appreciate much faster when it's their turn to dance. The flipside is that they depreciate much much faster too. It's a peace of mind choosing blue chips as you can really put in a large chunk of your capital and sleep soundly. However, among the pennies, I really hate the ass-chips. Personal feud....No more of such nonsense for me, haha!

Monday, July 26, 2010

Kindle firmware updates

Amazon's Kindle DX or Apple's ipad?


I had a kindle dx and I saw the ipad in action (I've played with it for a while), so I think I'm in a good position to comment on both. The most important thing I want to say is that the ipad is not the 'kindle killer'! Both of them serves a different function, I must stress. If you prefer to read books, the kindle is the only choice that you'll want to get because of the screen. The ipad uses backlighting LED screen to light up, so it's like reading off a monitor. Actually, if you have the iphone, it'll look exactly like that - a very smooth and clear display with adjustable brightness. I've not tried reading a book off an ipad but I can imagine after staring at it for 2-3 hrs in one go, your eyes can feel the strain even if you turn down the backlighting. Kindle uses a e-ink technology - it's hard to describe but it looks very good, almost like reading newspaper. Usually I forgot that I'm reader off the kindle and just read pages after pages for hours in one go with no strain. Unfortunately, you need a light source like a table lamp or natural lighting, just like reading a normal paper book.


Go on and zoom into the picture, it looks even more fantastic in your hands!


Kindle dx cost around 530++ SGD while the cheapest wifi, no 3G version of ipad cost around 760++ SGD. Kindle dx actually has a free 3G network worldwide (not sure if Singapore has it since I had the US version), so it does allow limited but free access to certain websites, though in black/white only. It's not meant for surfing the net, but it does allow for a very good exploration of certain things from wikipedia. Ipad is superb for surfing the net and I've not had such a pleasurable experience doing so from other devices. It's very intuitive and very visually stunning. It's really hard to let it go after playing with it as the colours are very vibrant and sharp. Really got to use it to feel it.


People will kill for this baby. The allure of apple.


Actually the main purpose of this post is to give back to the community that allowed me to know how to 'hack' my kindle dx. Amazon had a new firmware update which had the features that I always wanted (pdf zooming, if you want to know) in my kindle. However, since amazon did not officially launch the kindle in Singapore, I can't register it and hence cannot update the firmware. I searched for a way to register the kindle and found it here. It was a great sharing by 'Nifty' and I'm sure a lot of people would have thanked him tremendously, like I do.


The instructions are clear already enough. For those who had a kindle but wanted to register the kindle under your name, just follow the instructions clearly. I had problems downloading the files so I took the liberty to download it and upload it to another site myself, in case anyone had problems like me. The two files needed to make it work are found right here.


Would I get an ipad? I might. Sure, it's expensive, but it surely expands my fun :)

Thursday, July 22, 2010

How to catch the bottom?

It's hard to buy right at the bottom. From personal experiences, if I ever bought a counter right at the bottom - the elusive inflection point just before it turns up - it's just due to sheer luck rather than any godly skills in technical analysis or fundamental analysis. And because it's just luck, it's hard to replicate it consistently.


Reflecting from previous years in the market, I spent quite an amount of time and effort to learn the how to catch the bottom and sell at the top. Why the obsession over this? Don't the masters say that one must "Buy low and sell high"? Yes, they did, but they didn't say specifically that it must be the bottomost trough and the peakiest peak. Takes me some time to realise that... and I was wondering why I didn't come to realise it sooner. Silly mistakes made in the past are just that, plain silly. But at that moment of time, you wouldn't have the wisdom and experience to know otherwise. Optimistically, I take it as a learning process.


Knowing is quite different from doing, however. We all know that we have to lose weight but all the best laid plans set in the night before the morning jog will be laid aside when the alarm rings at 6am the next morning. Doing something requires more than just knowledge - it also requires a suitable dosage of motivation to start the engine going and another dash of determination to carry it through. But human beings being humans, there are always those who are good at starting things and bad at finishing them and vice versa.


Nah, there are perfect cubes around, like 8, 27, 64, 125...


Take the example of the very recent British Petroleum (BP). The oil leak incident at the Gulf of Mexico causes the share price to plummet. If you're interested in BP, and you're very convinced that the incident is just one-off (never mind the possibility of BP going belly up due to the sheer amount of compensation that is to come in the near future for the cleanup and claims), are you able to put down all your fears and buy it? Lingering at the back of your mind will surely be the formidable 'but' word - "the price is low down but...", "the oil leak is under control now but...", "the dividends are great at the price but....".


I think what I would do are the following steps:


1. Do a FA on the company in question. Read read and read reports on it and try to come out with a numerical value to the company, with the pessimistic scenario in mind.


2. Do a TA on it. Check for signs of bottoming and possible reversal signals before committing your capital on it.


3. Most importantly, start a chihuahua position on it, not a whale-size position straight away. A chihuahua position is just a small 'testing' point. Following the price after this initial position, you can choose the average up or down when the situation becomes clearer.


As a newbie in the past, I almost never follow point no. 3 - money management. Why is that? I was trying to save some brokerage fee by buying in one tranche rather than firing sparingly in several bullets. Don't the masters say, "More action, less wealth" or "Frequent in and out generates frictional cost"? Yes, but there's another group of masters saying that if you do a dollar cost averaging, your average buy price for the stock will be cheaper.


Aiya, so confusing...who to follow?

Tuesday, July 20, 2010

Ramblings

** "BIAS" is a special feature in my blog where I get to say whatever I want with scant regards for your feelings. I'm not politically correct in this feature, so go ahead, judge me."


Most of the time, my thoughts are on various topics. It's not enough to blog a full article about it, hence there will be times that I would have to 'discharge' my thoughts out so that I can stop mulling over it. This is one of the times. I wonder what is the reason for me to start this blog. I looked back and see if my initial reasons are still the same. It's still the same reason - it's for my own record. I needed the blog so as to channel my thoughts into written words (actually, 'cyber' words). If it helps me defray some of my costs for maintaining it, that's good. I'm definitely not going all out to make passive income from blogging. This principle will prevent me from blogging 'commerical' stuff to please sponsors or to attract higher viewership.


For those who had been my avid reader, I thank you for reading my ramblings.  Here's more ramblings:


1. I thought it's very interesting to see that parents are wishing that exams for primary 1 and 2 to be done away and yet there are other parents who signed their kids up for enrichment centres that have tests. I guess it all boils down to the perceived ability of the kid to perform well in exams. Why perceived? It's because when the kids are that young, there are no history to show that the kids can perform well academically, so it's all guess-work here. If I'm a parent who thinks that my kid is going to do well, I wouldn't want to do away with exams. Conversely, if I think my kid cannot do well, I would want to do away with it.


So what do I think about this issue, being no parent and having no kids now?


I think it's good that exams are done away. It'll really be sad if in the process of knowing your standing among your peers, you actually destroy the joy of learning. I don't mind so much if exams are easy, but if you looked at the recent primary 1/2 exams paper these days, you'll be in for a shock. It's definitely not easy at all. If that's the case, I do not see what's the reason for putting unnecessary difficult test to demotivate and demoralise primary school kids. But I think I can understand the parent's concern too - if there are no tests, then suddenly in primary 3 there's a major exams, how do you expect the kid to perform? Sigh...grades inflation - I think it's a structural problem in the education system, not something that can be easily solved. At one extreme, you do want to differentiate the good students from the mediocre, at the other you do not want to demoralise them.


We all tread a thin line of balance.


Good but useless advice


2.  I can think of many good but utterly useless advice. Here are some examples:


a. Buy low sell high
b. Do not spend money on unnecessary things
c. Do not buy stocks that are overvalued
d. Bring an umbrella if it's going to rain
e. Buy more in a bear market


Do you see the similarities between all these advice? They talk about a certain truth but they do not tell you how to recognise the truth and so it's becomes overly simplistic and utterly useless. Take the first one - "Buy low sell high". The problem is not with buying low and selling high as a concept, but rather how to recognize a low and a high. Take the second advice, "Do not spend money on unnecessary things". Again, the concept of not spending on unnecessary things is sound and good advice, but pray tell, what exactly are unnecessary things?


If you read enough books on financial stuff, you can recognise a good and useful book from a good and useless one from the amount of such advice dished out in the pages within.  At best, the former serves as a good reminder not to do foolish things, but at worst, it makes you read a lot without knowing anything.

Wednesday, July 14, 2010

When to buy?

I happened to see my buddy unicorn78's comments that he wanted to get some reits/divy counters but is not sure if now is a good time to get in. I gave that question a fair amount of thought because I've asked myself that question a few times too. So, instead of sharing with him alone, I thought it'll be good once I posted my views, the other more experienced market practitioners can share theirs in the comments.


As we learn more and read more about the market, I've no doubt that you'll definitely come across conflicting advice. One camp would say you should never average down your losses just to get out as it is more risky, the other would say you should buy more as the price gets lower to get a lower average price. Frankly, I've done both before. For longcheer, I averaged down as the price gets down until finally I can't take the losses anymore and cut off that gangrene in my portfolio at a huge loss. For HSBC, I average down and bought even more as the price falls, reducing a huge potential loss and it is now sitting around at breakeven level.


I think advice is one thing but the more important point in making the advice work for you is wisdom. You need to know when the advice is suitable. I believe all the advice works, given the correct condition. Thus, the hardest part is to know when to use which advice. So, that is my disclaimer for all my blog articles.


Here's what I will consider when answering the question of whether this is a good time to buy reits/divy counters:


1. For dividend yielding counters, I would want to look at yield of course. Once it hits a certain percentage, I would nibble a little. I never buy the exact number of shares I want in the first try, always in bullets. I've learnt enough in the market that there's no point timing the exact bottom - it's an exercise in futility. Follow snr bro's advice - buy slowly sell slowly. Depending on market condition (check TA), I'll break down the total batches in 2-3. Once I got in the first batch, I'll be a lot more stingy when entering the second batch, always preferring to look for the right TA set up before entering again, so you can say that my first batch is a test batch. Don't ever worry about transaction cost when buying in batches. I'll treat it as an insurance cost to prevent more capital loss than the minimum $25 paid for brokerage.

Personally, 5% is not enticing enough. There are banks preference shares that are a million times safer than reits/dividend counters with 5% yield. 7% is what I'm looking at. 10% (at suitable gearing) would be what makansutra would say, "Die die must try!"


What's the similarity between this picture and a 10% yield counter? Both have a "Die die must try!" stamp of approval on it


2. I find that reading up extensively before you buy can give yourself peace of mind when you are averaging down. The more you understand the situation, the more you can assess it and you can decide your course of action without fear. If I buy a counter which I did even know much, I wouldn't have the courage and conviction to buy buy to average down when the prices go down. So FA to me is just that - for the courage and conviction to buy when others are fearful.

Once you've read enough about the ins and outs of the counter, I'm sure it'll be easier to hold even when the market crash. In fact, I think you'll be wanting the market to crash to load up another bigger batch after your smaller tester batch.


3. The problem can be looked at in this way - if you wait longer, you miss out on the potential rally and perhaps several batches of dividends coming your way. Conversely, if you buy now, the market might crash and you might lose a lot of capital (albeit paper losses) but you get to have the dividends while waiting. Let's break down the problem:


a. Check the potential downside from the charts. Look at the possible support points. If the price is too far from support, maybe wait at support before buying a batch. Make sure the price at the support level satisfies the yield that you plan for. I don't compromise on yield because if I have to hold a dud for long, I would want to be adequately compensated for in terms of dividend.


b. How much is the upside? Again, look at the charts for possible resistance. Don't ever get near resistance level (unless you want to buy on breakout....I don't do breakouts anymore) because the possible downside risk to the nearest support might not be worthwhile.


c. How much dividend are you going to get? If you know your downside risk to the next possible support in (a) level and how much dividend you are getting in (c) plus the upside you might get from (b), I think you can get a risk/reward calculation whether to get it right now or wait. Especially useful when combined with the bullet system of buying any counters in batches.

Monday, July 12, 2010

To be a cat

I realised that I have a very relaxed stance towards investing my money these days. It's not a lack of interest on my part - I mean who wouldn't want to make more money right? It's more of a change in attitude in me. Perhaps it's the general lack of emotions towards my profits or losses that accompanied this change in attitude. This didn't happen overnight. It happened in bits and pieces over the years, accumulating perhaps like water dripping into a cup until the final droplet of water pushes the surface of the water beyond the boundary of the cup.


In place of viewing my charts and reading up religiously on annual reports, instead of discussing fervently about the entry positions and the merits and demerits of a particular company, I chose to rest and relax. Initially I felt guilt, like I wasn't doing my part in making the best out of my available time on earth. But as time goes, you see life and death of counters in the stock market and you see life and death of people on earth, and you cannot but realise that there must be a better use of time than being obsessed over all things financial. This epiphany must have hit me quite hard, because I always had a tight rein of things on monetary matters - trying to find the best deals, trying to make the most of my time, trying to beat this beat that...


This is not my cat. Though I say that, both have this seen-it-all behaviour typical of cats


...and then I looked at my cat, lazily grooming itself by licking her paws before snugging up her tail as a pillow and drifting into a comfortable nap in the afternoon. Loving cats makes me love watching time goes by, doing nothing.


In view of my current change in attitude, perhaps it's time to look more into instruments with little or no maintenance. For observant readers, you would have noticed that the list of books that I've read or am reading (found on the lower right hand corner of the blog) are filled with books of various topics with the exception of financial stuff. I just can't bring myself to read one of these books nowadays, having read them religiously for so long.


I think I'm getting less practical and more human now. I'm loving every minute of it.

Thursday, July 08, 2010

Retirement

I was intrigued by a newspaper report that in Europe, the retirement age is pushed back to 70 yrs so that the pension scheme that they had there will continue to function fully. I guess with a aging population, it's harder to support with a diminishing working class as the birth rates cannot continue to support an inverted pyramid for long. It's just too unstable.


Retire.


If you break up the word it become two parts - Re and Tire. Re means to do it again as in retry and reboot. Tire means to be exhausted, to be fatigued. The word sounds bleak doesn't it? To retire these days is not to sit back in your home, blessed with people who would support you. I think the image is going to be replaced by one which you have to work to support your own subsistence. Thus to retire means that you have to work again (in an environment that you are not appreciated and are lowly paid) and be fatigued by it all. Gloomy, isn't it?


I don't want to have such a bleak future. Thus, I think it would do good to think about retirement. I think the main concern would be health and money. It's good to think about a time when you can not longer function as well as you do when you're in your prime days. A passive income stream to support your own keep is great. A healthy savings to last beyond what you can spend is a blessing. And most importantly, good health to make it all meaningful and worthwhile.


Got to start planning.

---------------------------------------------------

After reading this again, I felt that I had left out something. I realised it now. It's no point having good health, good money for retirement. You need someone to grow old together too. May be your loved ones, may be your children, may be your best friends or even a cat :)

Tuesday, July 06, 2010

To milk or to slaughter?

Having sold a dividend yielding counter recently, I was thinking about the age-old problems that plagued me. I was suitably reminded of someone's analogy (bro8888's?) that a dividend yielding counter is like a milk cow. Every other time, a milk cow will give off milk, so that you can drink some and sell some, thus giving you a good cash flow. Alternatively, you can sell the milk cow to someone at a good price and get several years worth of 'future' milk money now, so that if there's a mad cow diseases floating around infecting other herds, your future cash stream will be secured because it's in your hands now. This comes at a cost - you'll lose your future cash stream and possibly the price of the milk cow might also increase in the future.


To milk or to sell - that is the question


Quite a good analogy to stocks, no?


The counter I sold recently was singpost. This particular tranche I had held for quite some time - around 3 years in all. I had bought it at a rather high price of $1.18, something that I had regretted for an equally long time. However, I made good on the stocks when I sold it at 1.13, with my dividends covering all my capital losses and making up an 'okay' profit.


The thoughts that ran through my mind was if I should hold on to it longer to get more dividends or should I just sell to lock in my profits to get my hands on cash, and live to fight another day. Here's my reasons for divesting:


1. At 1.18 entry price, I was not doing as good on my yield. Singpost gives quarterly dividends up to a tune of 6.25 cts per annum, thus giving me a yield of 5.3% per annum. Not bad, but not fantastic either, considering other lower geared but higher yielding alternatives out there. Therefore, I was inclined to sell it to get the cash to get into the other alternatives.


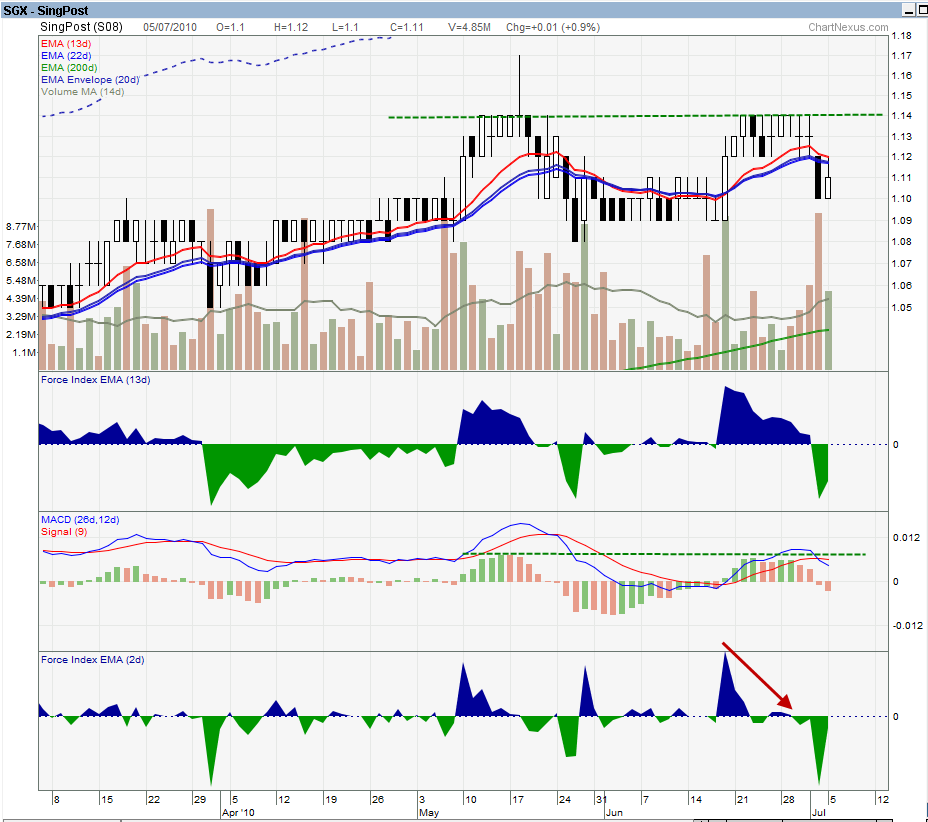
2. A picture tells a thousand words. Let's see what this picture tells you:

Singpost - daily chart

I wanted to sell at 1.14 but after queuing for nearly a week, I couldn't get it done. I just opted for 1.13. This chart was not particularly bearish, but the overall market condition was, so I didn't want to risk what I had out there and just took what I can out of the table. The price dropped due to XD. On hindsight, I could have got the dividend, sell at 1.12 and have both my cake and eat it too. But alas, things are always much clearer after it had happened.


3. I told myself that I would want to 'trade' this counter again, with this as the second round. The time frame for trading this is actually quite long, which is fine for me actually. I'll want to trade it when the signal comes and to hold it for dividend yield when the price reaches around 90 cts level. At 0.90, the yield will be near 7% - that would be something worth holding for.

Tuesday, June 29, 2010

CAGR II

Recently, I was given an opportunity by a reader to explain more about CAGR. It's not a brand of cigar. It's refers to compounded annual growth rate - a calculation to find out the compounded returns per year (note that this is different from simple interest rate). I actually wanted to share how silly this calculation is about but I had a feeling that I've written about it donkey years ago. After searching, I realised I did write an article about CAGR here, so I'll just highlight or perhaps add some points to it.


Frankly, I've not used CAGR for years because of I realised that with one calculation, the whole story can be quite distorted. Basically the calculation of CAGR depends on three variables - Future value, present value and time period. The most significant gripe I have about CAGR calculation is the fact that you can get hugely wide differences in value by just changing the variables. Essentially it boils down to a GIGO (garbage in garbage out) system where the output depends firmly on the input that you put it.


CAGR CIGAR is a stick used for smoking, giving a pleasurable feeling afterward


Take a look at this example. Let's say these are the figures for yearly profit from year 1 to year 4 respectively:

10, 15, 20, 25

Present value: 10
Future value: 25
Time period: 3
CAGR: 35.7% per yr


Here's another example of yearly profit from year 1 to year 4 respectively:

10, -2, 45, 25

For those who are synchronous with me in thought would have realised that the CAGR for the two examples are exactly the same. Why? The first example and second example looks very different but the three variables that affect CAGR calculation - namely present, future value and time period - are all the same.


So, what does that leave us?


1. Firstly, you must realise that the CAGR just draws a straight line between the start value (present value) and the end value (future value) and ignores all the ups and downs in between them. In a non-linear world, this assumption is just plain bullshit. I can make a good CAGR by carefully selecting my base year and my final year, so do be careful of it. Statistical calculation must be treated firstly as a blatant lie.


2. Secondly, it would be better to accompany CAGR calculation with the actual values of the data points in between the present and final values. To make it better, I would suggest a graph. It's like doing linear regression calculation in A'lvls - you must accompany each calculation with a scatter plot. This will give a bigger picture of the meaning of the CAGR value calculated.


3. Lastly, I simply do not use it anymore. From experience, projecting the past into the future is at best a guesstimate because the reality could be more optimistic but usually more pessimistic. Since it's a guesstimate, there's really no need to put a numerical figure to your guesstimate. I do not use it anymore because I fail to see the value of such calculations in fattening my wallet, though it might well do to fatten my ego.

Sunday, June 27, 2010

You need both rainy and sunny days to make life's rainbows

** "BIAS" is a special feature in my blog where I get to say whatever I want with scant regards for your feelings. I'm not politically correct in this feature, so go ahead, judge me."


Time seems to fly these days. It seems like it's the opposite of what Einsten's theory of relativity had proposed. You know, in that theory, if you travel as fast as the speed of light, time seems to stop from your point of view. In work life, it seems that if you work very very hard, time seems to fly even faster. Day and night zooms by, punctuated by meal times and the occasional travelling and before you know it, Monday goes and Friday comes again, thus ending the week.


Since there is really not much activity in the market (okay, except for my sell order that I had been consistently keying in everyday but didn't get filled), I thought it'll be good to talk about things that I'm grateful for and things I'm not so happy about. Here goes:


An unhappy cake. Have you seen a cake that wants to be eaten?


Things I'm not happy about:

1. I spent my morning reading through the Sunday times and saw an article about CEO of SMRT saying that the mrt trains at its peak are carrying 1.4k passengers, compared to its 'crush load' of 2k passengers. She then compared to the peak carrying load in Tokyo and HK and implied that the trains are not as fully packed and Singaporeans can squeeze in if they choose to do so.

I think if she takes a break off her car for 1 month, and try to take the MRT to work everyday, squeezing in with the crowd in the morning and again in the evening, she can better appreciate the implications of her statement. The stress related to being cramped in a tiny morsel of space day in and day out cannot be described to a person who had not experienced it before.

I hate it when people in authority starts comparing to other countries to 'bring out' the goodness in our system. Things are not so easily comparable. I can similarly cherry pick things that are good about other countries to 'push down' our system of doing things here too.


2. I was woken by a sharp diarrhea this morning way before my alarm rings. Must be some nonsense I've eaten last night.


3. Some horrible horrible inconsiderate people are honking their car horns so early in the morning. I'm sure whatever problems might be in front of them can be solved by calmly walking over and talking to the person, or simply by waiting. Honking your car horn doesn't make things any better. When I was a learner driver, I had my fair share of it. It made me worse as I get even more nervous. I'm sure whoever is honked at would feel the same too, or that they are simply immune to it. Either way, honking the car doesn't get things done...perhaps it only serves to wake up some people around the neighborhood.

I remembered a joke from my army daze. A group of us are sitting in the bunk, trying to escape the evil all-seeing eyes of the CSM. One of my buddies asked what should be done if you're driving and the car in front of you starts to slow down. He's studying for his basic theory so he's asking some possible questions.


a. Slow down
b. Speed up and overtake him


Did anyone choose option (a)? Well, not contented, another of my buddies started wisecracking and said that we should honk first, then slow down and honk again. There you go.


I like this picture a lot. Simple and to the point.


Things I'm grateful for:

1. I went to Robinson sales at Singapore expo with my girlfriend yesterday. It was such an interesting experience! There was a concurrent MPH warehouse sales so we went over there first, where my gf bought 9 books (it's considered a few...I'm sure she'll carry more if I didn't force my way with her). I guess she can spend her whole lifetime reading her already immense collection of assorted books lying all over her room and threatening to spill over other parts of her home. Silly girl :)

The books are priced at $8 each for 1 general book, and $35 for 5 general books. The collections are quite varied and I haven't even walked 50% of it. I think they are ending today, so go and check it out if you like a good bargain.

The Robinson sale was fantastic too. Bought some Adidas shirts at over 60% discounts. All sorts of things there, but be prepared for long queues :)


2. I'm grateful for the early morning showers that makes the day much cooler and more pleasing. I was joking to my student one day that we should all go down to Orchard road to grab some floating iphones and hermes bag when one of these high intensity, high duration rain comes again :)


3. Wonderful technology - blue ray. Was at a brother's place watching some 'brue lay' movies and was once again amazed at the crisp clear pictures. I must have said it more than once that I'll be happy just watching the subtitles because they are so pleasing to the eye!


4. School holidays will be over! I can finally get to rest in the morning and resume my vampirish schedule which I think I'm better suited for. Begone early morning classes, welcome night classes!

Tuesday, June 22, 2010

One weekend at Fullerton Hotel

I went over to Fullerton Hotel over the weekend for a break from work. Work had been getting more and more unbearable, so I think a mid term break from all of it, even if it's for a while, is good for my mental well being. Since I've never been to a local hotel before, I thought of going there instead of the slightly more troublesome trip to my favourite Batam. Batam is good for those long stretches of idle days...something I can ill afford now.


Anyway, I signed up for the 1 night stay there, which cost me $340. The package includes a $88 rebate for any amount of money spent in Fullerton (it can be the Courtyard, the bar or the Jade restaurant), so I think it's pretty worth it. Me and my gf are celebrating something over there, so we also get to have some chocolates and a bottle of wine complimentary from the hotel. There was some misunderstanding, so they didn't really send the bottle of wine and chocolates up to our room during our stay there, but they made it up by giving us a pack to bring them home. Quite impressive service.

This is about the only proper picture taken off my hp. The rest are just too shaky to be publicly displayed.


Since Sat was the NDP rehearsal at the Padang, there were plenty of fireworks to be seen. I can't really see them from the hotel room (not dying to see them anyway) but I can definitely hear them. During the evening, as I was waiting around in the swimming pool (it's open air), I managed to spot a few soldiers parachuting down from the sky too. Quite interesting because I've not seen them except on television.


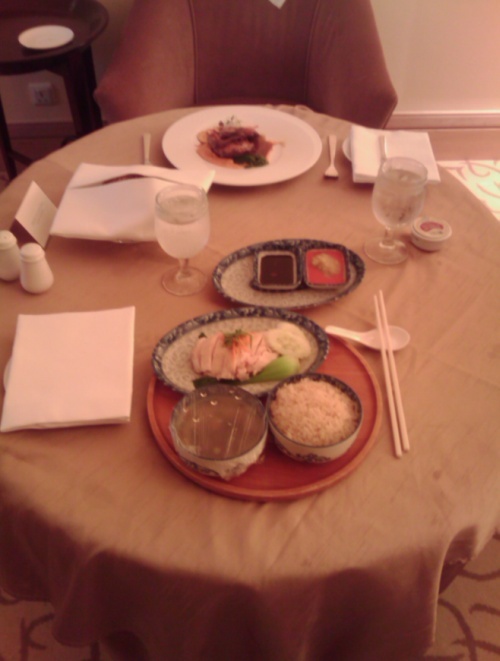
We asked from room service dining. It was quite a good experience because usually when we dine in the hotel room, I was just given a tray with the food. For Fullerton, they did the entire table routine with proper tablecloth and setting, complete with glasses of water and napkins. I was suitably impressed with this, being the mountain tortoise that I was. You really don't know what is good until you've encountered it.


Erm...it looks more impressive when you're there, with the sight and smell thrown in


Even though one night is a tad short to me, I thoroughly enjoyed myself there. I was watching television, reading and basically just resting my entire weekend. I even managed to sneak in a lunch appointment with the brothers here, so it's definitely one of the most memorable weekends that I will remember. I cannot recall when I have my weekend totally devoid of work. Definitely worth it.


That's how life should be right? Spending money to buy back happy memories to savor forever.

Thursday, June 17, 2010

The forgotten habit of reading

** "BIAS" is a special feature in my blog where I get to say whatever I want with scant regards for your feelings. I'm not politically correct in this feature, so go ahead, judge me."


In my job, I talk with many young people. I walk away with the grim knowledge that most of them do not have a habit of reading. I'm not just talking about reading textbooks for academic purposes, but also reading for the joy of doing so. From what I observed, girls read more than guys, though it might be mainly fashion magazines or other lighter fair like 8 days etc. I think one of the main contributing reason is that there are many distractions that are far more exciting than just plain reading.


I was just telling one of my students that I had just bought a kindle dx just three weeks ago. He asked me how much it costs and I told him it's a few hundreds. To this, he exclaimed that he would never spend such money on books. I guess that pretty much sums it up about the youth these days. They would rather spend money to engage someone to teach them then to read it up themselves. It's quite horrifying when I heard that most of them will just throw away the manual for any gadgets they bought and just jump straight into it. Perhaps they are so confident of their ability to trial and error any functions that their gadgets possess (they are afterall, the IT generation).


But why are they so disgusted with reading? I've no idea, but I guess it's good for my job. Most of the stuff I teach can be found in the examples given in the textbooks, so I suppose that if they do read it up, I might not be that busy anymore.


To me, reading is the best way to gain the knowledge and experiences of those that came before us. Culture is retained in the literature and passed down from the past to the present. If you would just read, you'll find that you do not have to keep re-inventing the wheel. I remembered when I was learning FA, I had a goal of reading one finance book per week - that makes it 52 books per year. That was back in 2008. I was reading voraciously on accountings, financial statements analysis and those books by guru investors, and I was greedily lapping it all up. It was until I had finished most of the shelves in the library that I slowed down. These days, I am much more selectively in what I read, choosing instead to re-read some of the best books that I had filtered down through the years.


My gf always wanted shelves of books occupying an entire wall in our home


Just for the records, here's the books that I devoured from 2007 to 2009. I'll highlight the ones that I would want to re-visit again and again.


Books read in 2007

1. Five point something – Chetan Bhagat
2. How to become stupid – Martin Page
3. The curious incident of the dog in night-time – Mark Haddon
4. The stupidest angel – Christopher Moore
5. The way of the cockroach – Craig Hovey
6. Legally correct fairy tales – David Fisher
7. It’s kind of a funny story – Ned Vizzini
8. Jacob’s ladder – Brian Keaney
9. Politically correct bedtime stories: Modern tales for our life & times – James Finn Garner
10. Cathy’s book – Cathy
11. Metamorphosis – Franz Kafka
12. Label – Louis de Bernieres
13. The successful investor – William J. O’Neil
14. Rich dad poor dad – guide to investing – Robert Kiyosaki
15. Do you want to make money or would you rather fool around – John D Spooner
16. Vault career guide to investment banking
17. Financial Statements - Thomas R. Ittelson
18. The four pillars of investing: lessons for building a winning portfolio – Dr William Bernstein
19. Accounting Demystified: A self teaching guide – Loita A.Hart
20. Five rules for successful stock investing – J Wiley, Joe Mansueto, Pat Dorsey
21. The little book of value investing – Christopher H. Browne
22. The little book that beats the market – Joel Greenblatt
23. The unwritten law of business – J.W. King, revised by James.G.Skakoon
24. Stone age company – Sally Bibb
25. The rules of wealth – Richard Templar
26. The laws of simplicity – John Maeda
27. The 5 keys to value investing - Jean Jacques


Books read in 2008

1. Warren Buffet Speaks - Wit and Wisdom from the World's Greates Investor - Janet Lowe
2. Winning - Jack Welch/Suzy Welch
3. The Dividend rich investor - Joseph Tigue/Joseph Lisanti
4. The little books of common sense investing – John C bogle
5. Everyman and his common stocks – Laurence H. Sloan
6. Investment madness – John R. Nofsinger
7. Lessons from the legends of wall street – Nikki Ross
8. Understanding comics – Scott McCloud
9. Free cash flow and shareholder yield – William Priest/Linsay McClelland
10. The ultimate dividend playbook – Josh Peters
11. The five rules of successful stock investing – Pat Dorsey
12. Why smart people do stupid things with money – Bert Whitehead
13. Building the perfect portfolio – Curtis J. Montgomery
14. A concise guide to macroeconomics – David A. Moss
15. Little black book of connections – Jeffrey Gitomer
16. The little book of value investing – Christopher H. Browne
17. The Tao of warren buffet – Mary buffet
18. Monopoly rules – Millind M. Lee
19. Buffettology – Mary buffet / David Clark
20. Common stocks and uncommon profits – Phil. A. Fisher
21. One up on wall street – Peter Lynch
22. The Warren buffet way – Robert G. Hagstrom
23. Anyway – the paradoxical commandments – Kent M. Keith
24. Cut to the chase – Stuart R. Levine
25. The Intelligent investor – Benjamin Graham
26. The bull hunter – Dan Denning
27. The black swan – Nassim Nicholas Taleb
28. The market guru – John Reese/Todd Glassman
29. Liar’s Poker – Michael Lewis
30. Confessions of a wall street analyst – Dan Reingold
31. The Citibank guide to building personal wealth – Leo Gough
32. The essays of warren E. Buffett – Lawrence A. Cunningham
33. Morningstar guide to mutual funds – Christine Benz
34. Benjamin Graham on value investing – Janet Lowe
35. A random walk down wall street- Burton G. Malkiel
36. Even buffet isn’t perfect – Vahan Janjigian
37. Origins of the Crash – Roger Lowenstein
38. Reminiscences of a stock operator – Edwin Lefevre
39. Killing sacred cows – Garett B. Gunderson
40. The real warren buffet – James O’Loughlin
41. 100 cats who made a difference – Sam Stall
42. The little book that makes you rich – Louis Navellier
43. Debt – Juliane Otterbach
44. Saving – Juliane Otterbach
45. V for Vendetta – Alan Moore, David Lloyd
46. Full of Bull – Stephen T. McClellan
47. This is not a book – Michael Picard
48. My Formula! – Thomas Matthew
49. Value Investing – Sebastian Chong
50. Financial statements for non-financial people – Ron Price
51. A primer on money,banking and gold – Peter L. Bernstein
52. The little book that saves your assets – David M. Darst
53. The Joseph cycle (2004 edition) – Simon Sim
54. Animal Farm – George Orwell
55. I.O.U.S.A – Addison Wiggin, Kate Incontrera, Dorianne Perrucci


Books read in 2009


1. Investing against the tide - Anthony Bolton
2. Pit Bull - Martin Schwartz
3. Fooled by Randomness - Nassim Taleb
4. When genius failed - Roger Lowenstein
5. Real tips, real money - Leong CT/Leong SH/Dr David Tay
6. Candlestick charts - Clive Lambert
7. Sell and sell short - Dr. Alexander Elder
8. Come into my trading room - Dr. Alexander Elder
9. Trading for a living - Dr. Alexander Elder
10. Silver Surfer Requiem
11. Free market madness - Peter A. Ubel
12. Sales Bible - Jeffrey Gitomer
13. Avengers Disassembled - Brian Michael Bendis/David Finch
14. Successful Value Investing in Asia - Tony Measor
15. Where are the customers' yachts? - Fred Schwed, Jr
16. The little book of bull moves in bear markets - Peter D.Schiff
17. Keynes and the Market - Justyn Walsh
18. Warren Buffet and the interpretation of financial statements - Mary Buffet & David Clark
19. The physics of superheroes - James Kakalios
20. Motoring Basics
21. Your money or your life - Joe Dominguez and Vicki Robin
22. Bailout - John Waggoner
23. The Millionaire in you - Michael LeBoeuf
24. The 5 lessons a millionaire taught me - Richard Paul Evans
25. How to trade in Stocks - Jesse Livermore (& Richard Smitten)
26. The Wall street Self defense Manual - Henry Blodget
27. Teach yourself to Live - C.G.L. Du Cann
28. How to become a property millionaire - Azizi Ali
29. Cats - the book of the musical - Harvest books
30. The little book that builds wealth - Pat Dorsey
31. Success in the education business - Vincent A. Gabriel


So there!

With my Amazon Kindle, I'll be reading much more fiction and classics that I had always wanted to read, but had difficulty finding in the library. These days, it's hard to find new knowledge in the financial books that I read. After all, there's only so much things to learn about finance. Most of the books will be just talking about the same ideas but phrased in different forms.