Sunday, November 14, 2010

Preference shares Part III

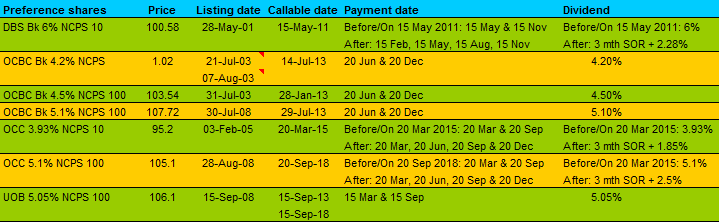
I've always wanted to compile a list of all the preference shares offered by banks since 2008, but never really got the time and inclination to do it. That is until some anonymous reader of my blog prompted me by asking me some questions about the preference shares. I did some quick research to answer the questions and realised that there just isn't any place where I can compile all the data in a single post. I think I should do that for personal reference.


I started collecting information about the 7 preference shares that are already listed in SGX. Soon, there'll be one more addition to the family by DBS. I shall skip all the technical details about what actually is a preference share, since I've mentioned at length in other posts. For quick reference, here's the two posts I made on preference shares:

Preference shares part I 

Preference shares part II

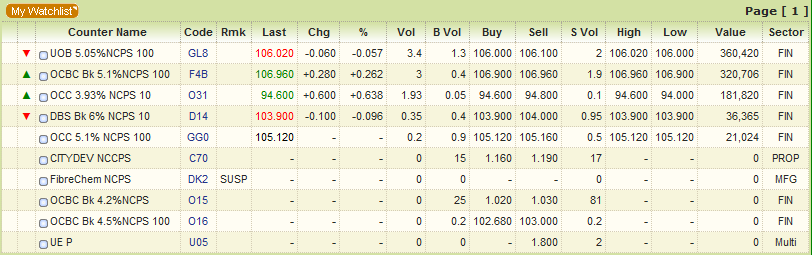
Here's a compiled list of all the 7 preference shares below. Please do pay attention to the remarks below the table, as they contained important information relating to the preference shares.


Remarks:

1. All the preference shares listed above have par value of $100, with the exception of OCBC Bk 4.2% NCPS which has a par value of $1.00.

2. For OCBC Bk 4.2% NCPS, there are two listing date. For the first tranche listed on 21-Jul-2003, it is issued at a price of $0.995. For the second tranche listed on 7-Aug-03, the issue price is $1.0027. All the other preference shares are issued at a price of $100.

3. I typed out information related to the DBS preference shares here, OCBC here and UOB here. Please double check the information yourself. It's late at night and I'm sleepy.


I think what's important here is to pay close attention to the callable date and the dividend payment policy. Especially the dividend policy. The callable date is important because it determines when the party might end. For example, DBS 6% NCPS 10, the callable date is on 15-May-2011. This means that on that date or thereafter on every dividend payment date, the bank might recall back the preference shares by paying the holder the par value of the preference shares, which is $100. If you bought it at $100.58 last Friday and they recall it on 15-May-2011, you get payment on 15 May 2011 only (too late for the 15 Nov 2010 payment because it had gone XD, thanks to WR for pointing out my mistake), hence you'll get less than the $6 per share. At the same time, you'll have to incur a capital loss because the bank will give you $100 for each share you bought. Since you bought it at $100.58, you'll stand to lose $0.58 per share


That's not all. After the callable date, if the bank did not recall the preference shares back, the dividend policy will also change. Instead of giving 6% pa on the par value (i.e.$100), they will give you 3 month Swap Offer Rate (SOR) + 2.28%. The 3 month SOR as of last Friday (12th Nov 2010) is 0.268%. The highest since 2008 is around 2% and the lowest, well, is right now.


Let's say I'm the bank. If by 15 May 2011, the 3 month SOR hovers around the same level, say 0.3%, then instead of giving each preference share owner 6% pa, I'll be giving them 2.58% pa (0.3 + 2.28 = 2.58). That is much lower than the 4.7% preference share that DBS is going to launch soon. Will I recall them back? Probably not, unless I need the money (I didn't bother to find out exactly how many 6% pref shares are issued, compared against the 4.7% one) because I can secure the debt (selling preference shares is sort of a debt) at a cheaper cost and use it to generate profits. Let's see how it turns out by May 2011.


Some of these had two callable dates, and I didn't list out those callable dates that had passed. I just want to say that the banks do not have to recall at the callable date. It's just a possibility to consider. I'll do some more analysis on each preference shares because I think it's quite interesting to see their total returns, assuming they will be recalled back at the earliest possible callable date.
Thursday, November 11, 2010

Sabana Shari'ah Compliant REIT

There's more IPO coming up and more REIT type of IPO, right after the launch of the mega one by MIT. Unfortunately, though I bidded for that in the offer period, I didn't get a single lot at all. Let's hope this one - Sabana Shari'ah Compliant REIT works out well for me.


This is actually an industrial reit managed in a manner compliant with Shari'ah investment principles and they can only invest in Shari'ah compliant real estate and real estate related assets. It holds 15 industrial properties across Singapore and is the only Shari'ah compliant reit listed in Singapore - possibly the largest in the world by total assets. What's interesting about Shari'ah compliant reit is that muslims can apply into this. Strictly according to their religion, there are certain investments (even insurance) that does not sit too well with their religious teachings and principles, hence they are not allowed to invest in them. By setting up this reit, it opens up a new instrument for them to put their money in. Sort of to tap the Middle eastern market, so to speak.


Shari'ah guidelines state that non-permissible activities cannot exceed 5% pa of the gross revenue of the reit. Non-permissible activities include activities like conventional financial and insurances services, gaming, non halal production, tobacco related products, non-permitted entertainment activities and stock broking in non-complaint securities. Takaful insurance coverage have to be sought where available and financing, investment and deposit facilities have to be shari'ah compliant, if not, after seeking approval, the conventional kinds will do. Go on and google about Takaful and Shari'ah. It's a very elegant way to do ethical investing.


They should be doing road shows to entice institutional investors to get into their placement tranche before deciding on the IPO price. The minimum and maximum offer price is $1.00 and $1.10 respectively. Based on the minimum offer price, the forecasted yield for the reit in 2011 and 2012 is 8.45% and 8.48% respectively. NAV value is 0.94, so obviously the IPO price is above the NAV by around 6.4% to 17%, depending on the offer price. Gearing, defined as total liabilities to total assets stands at 33%, which is pretty okay. AIMS and CIT, both industrial reits, have gearing at 34% and 39% respectively, so this sabana one is quite normal I suppose.


Sabana reit have quarterly payouts, on the last day of March, June, Sept and Dec. However, the first distribution after listing will be on March 2011, payout latest by end of June, so says the prospectus. 503,994,445 units will be offered in total, of which 428,494,445 (85%) will be for placements to institutions. Another 44,500,000 (8.8%) will be for managers and employees and the rest 31,000,000 (6.2%) will be for the retail investors like you and me.


In comparison, GLP offered 1,173,244,000 shares, with 102,375,000 (8.7%, but could be less, I didn't subtract those given to employees/managers) offered to the public. MIT offered 594,913,000 with 80,445,000 (13.5%) offered to the public. I didn't get any shares from MIT and got 1 miserable lot for GLP. I think it's going to be tough getting something for Sabana because the amount allocated for retail investors are even less than half that given by MIT for retailers. That's my honest opinion.


Strategy: 


My rule - don't hold IPO for more than 1 day. If I've less than 5 lots I'll just sell on the debut day of trading and be done with it. Since the price range is more like MIT than like those penny 20 cts IPO, the first day gains should be like 20% rather than 40%. Say it's 1.10 offer price, 15% will be 1.27. I'm happy to run at that price and any more is a bonus. I'm not greedy at all.


If however, I'm given more than 5 lots, I'll sell half on first day, and hold on the rest for a while. At 8+% it'll be quite good holding it, so I'm not scared of it falling further. The price is supported by the yield so it shouldn't fall too much, if at all. There are indexes which are Shari'ah compliant, so since Sabana reit is a biggie in term of total assets, I'm sure the indexes will get their hands into it. I'm of course assuming that the placement is not enough for the big boys, so they will try to get their hands in open market, much like GLP upon listing. That might be catalyst for it to go up further. Could be time to dispose of the remaining lots by then.


Talk so much, get it first then talk more.

Mothership is here

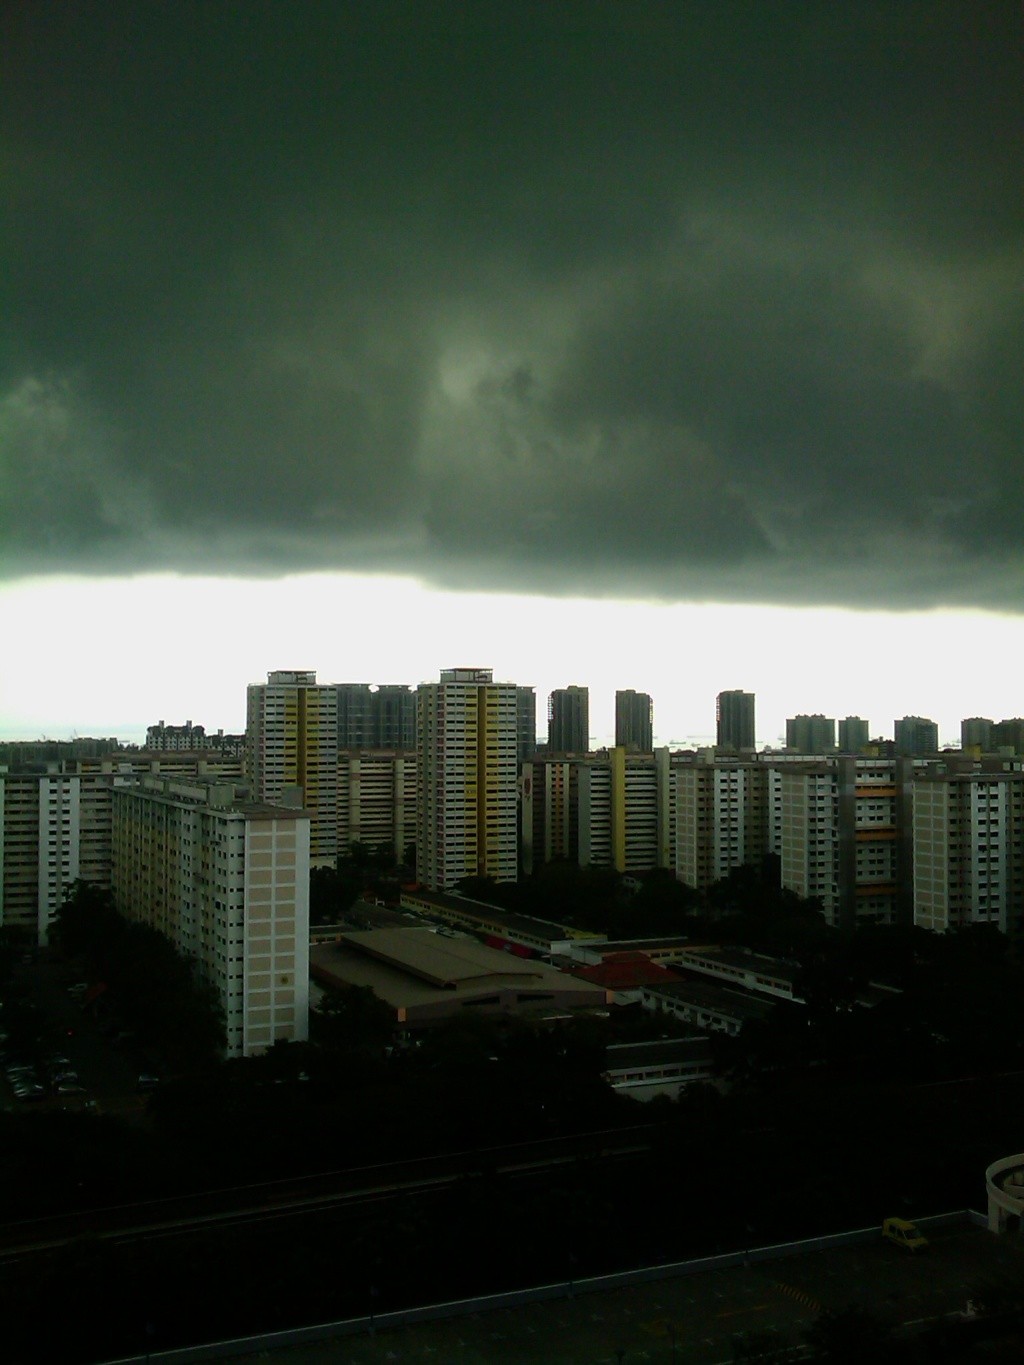
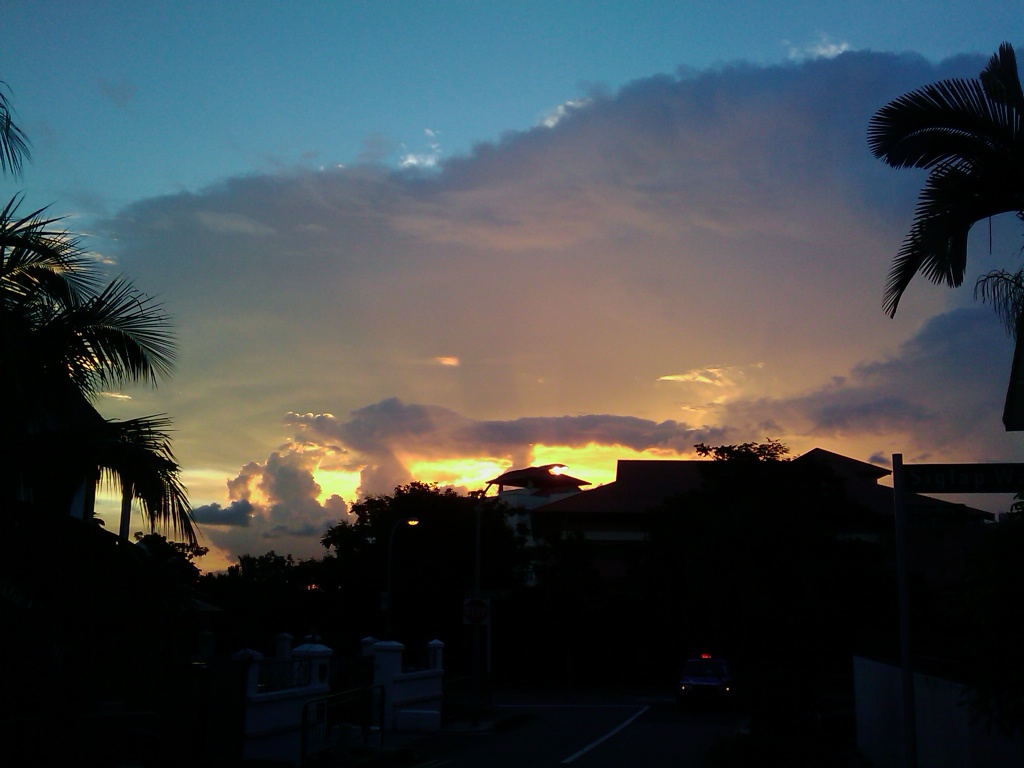
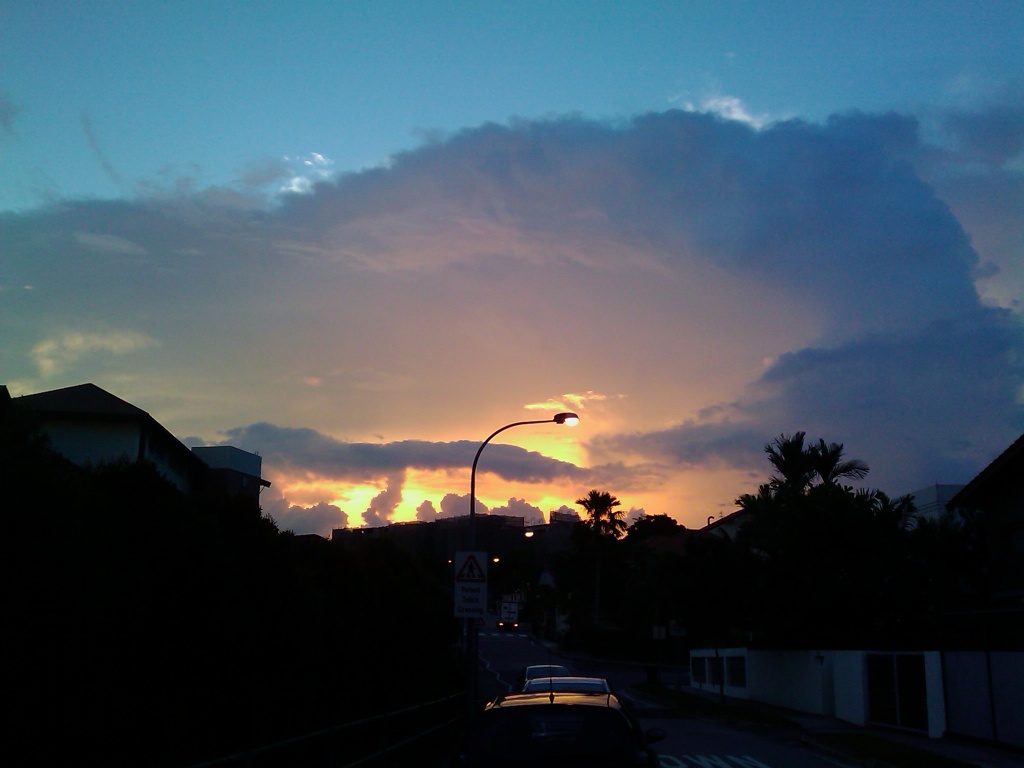
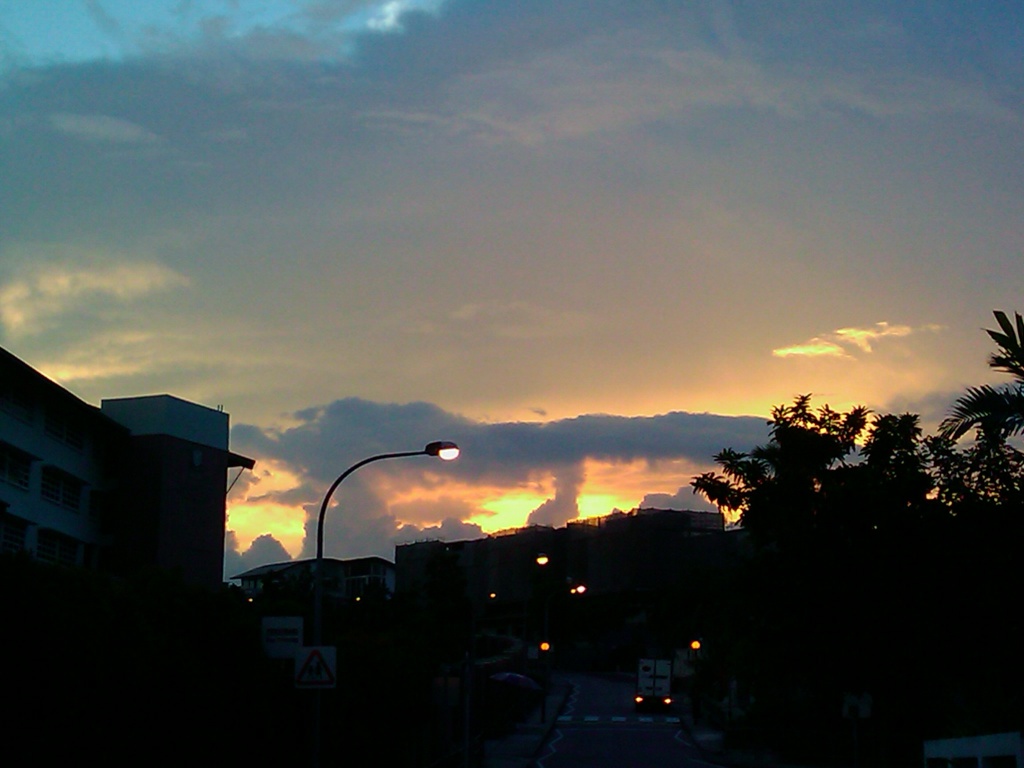
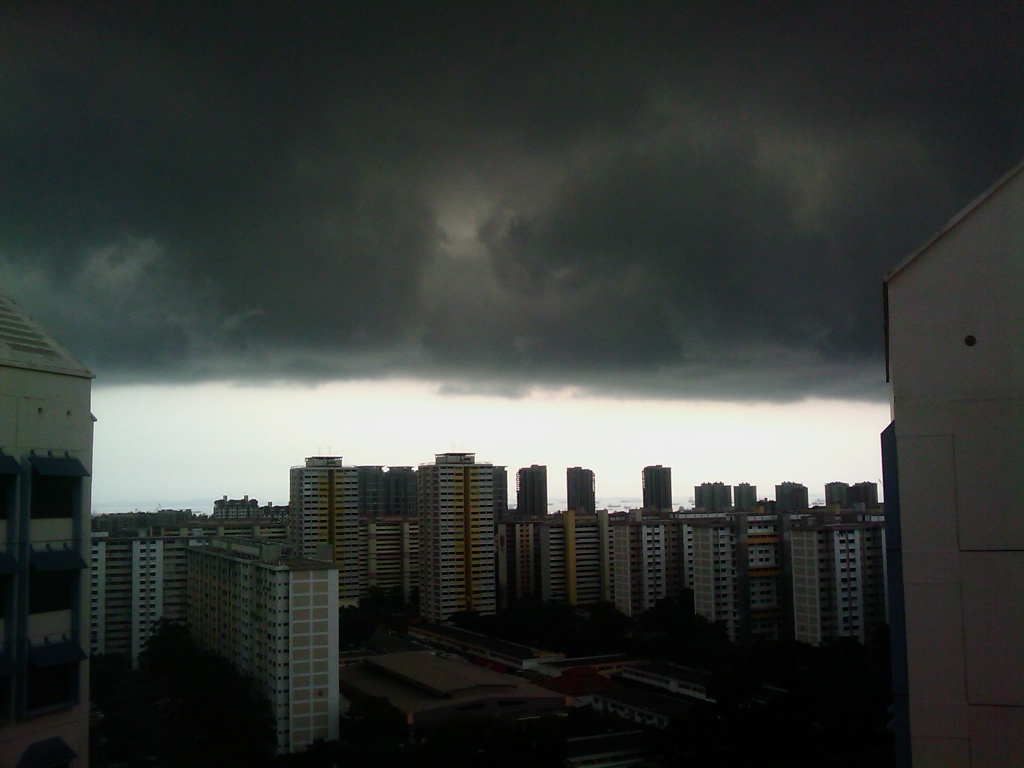
Nature throws its fury onto earth. Amazingly scary, looks like alien mothership is descending on top of me. Here's 2 pictures that I took just out of my window. No, I didn't photoshop anything.


See the little bright light in the centre of the picture? Didn't see that when I took the picture.


It's quite scary when you're there in person

Wednesday, November 10, 2010

Good deal for fixed deposit

I was surfing blogs recently when Singapore Blue Chips (I call him sbc for short) made a very interesting post. It's regarding this bank, ICICI bank, that is giving a very good interest rates for its fixed deposit account with them. ICICI bank has only one branch in Singapore at Raffle Quay and is one of the newest foreign bank setting up shop locally.


I was checking casually, not 2 weeks ago, when I was trying to see if there's anything to recommend to my parents. They are not investors and savings plans for them is a joke at this point in time. For short term, almost risk free, good returns only. As I was checking out the different banks, I realised that the local banks are giving us a pittance for the sum of money deposited in their banks. Here's a breakdown for a sum of  100k, SGD denominated, 3 yrs maturity period, fixed deposit by the various banks (dated 8-Nov-2010):


UOB: 0.7% pa

DBS: 0.7% pa (their website did not have the data for 3 yrs, so the rates are for 2 yrs)

OCBC: 0.7% pa

HSBC: 0.45% pa (their website did not have the data for 3 yrs, so the rates are for 1 yr)

Standard chartered: 0.75% pa (for 60 months, it's 1.10% pa)

Citibank 0.45% pa

May bank: 1.15% pa


You can see how pathetic the options are for fixed deposit. It really pays to shop around rather than think that they are all the same everywhere. You can get a huge range of interest rates just by shopping around. So, imagine the shock I had when I read the post by SBC regarding the interest rates offered by ICICI bank. Take a look:


It's frakking 2.20% pa - twice as much as the highest rate given by the whole list given to you earlier. At 2.20% pa, it even beats the SIA bonds offered to the retailer not too long ago. That has a maturity of 5 yrs, given a return of 2.15% pa. It's a very good deal, in my opinion. So, if you have spare cash that you can't put anywhere, you might want to consider putting it into ICICI bank for 3 years. It's as safe as local banks because it's guaranteed by the same act that governs the deposits in Singapore. Might want to check out what's the guaranteed amount though, that is due to change by end of this year, I believe.

Monday, November 08, 2010

What makes a fulfilling day?

What makes a fulfilling day? It's a happy problem to think about, especially now when I'm moving at a slower beat. You know, some days are just more fulfilling than the rest because you finish the day, lying on the bed just before you sleep, thinking that you've accomplished quite a few stuff. You feel warm and snugly and think that if life is like this all the time, it would be great.


I thought about what could be a fulfilling day for me. Here's what I thought:


1. Having a great outing with good company. this can really make me jump for joy. A great outing would be those that time seems to fly by and before you know it, it's time to go off. I had many many great outings with the folks in the cbox and it'll always be etched in my memory. I remember fondly those 'roasted pig' outings at Beng Hiang especially, haha!


2. Good food. Good food is amazingly morale boosting. I remember when I was having a very hectic 5 classes day, having a good meal at the end of it all makes me feel satisfied and utterly contented. Maybe that's why a good outing always involve food because dinning together is such an important way to get close together. When I'm alone, I just feed - usually the $2.50 economical 'lice' that is stomach filling but not really satisfying. But if you eat too much, then you've got to exercise off that extra weight, so you've got to have some....


3. Exercise. It can be a slow jog or some weights or even a leisurely walk at night, soaking in the quietness and solitude that the night offers. I've been starting up on some exercise program recently and it's making me more alert when I'm awake and more sleepy when I'm tired. Which brings me to the next point...


4. A good night sleep. Or an afternoon, but preferably both. Having a restful night is one of the best thing that defines the day because you'll wake up feeling so refreshed and alert and ready to take on the day's challenges. On the flip side, if you can't sleep well, no matter how great the day's program is going to be, you'll probably won't enjoy it as much. Sleep is important. Having proper sleep discipline is what I wanted to do in the future. I believe it's important to one's long term health as well.


5. Do some work, preferably those that can earn you some money. Maybe it's just me, but a fulfilling day is one in which I can earn some income. Blogging is one way to get it...it's perfect - I get to write what's on my mind and crystallise it in words (it's very very therapeutic to me) and I get paid. Paid peanuts of course, but still, every little bit helps. My main work offers much more financial income but having too much of it is not efficient. Honestly, it's just self-driven slavery. But the point stays, having some income producing work makes a fulfilling day. Key word is actually 'some'. My work always make me feel happier and much more satisfied. Perhaps that's why I'm not feeling so good these days...my endorphin producing work is lessening...


6. Read. After getting myself a kindle dx, I've been reading like a 18 year old boy thrown into a palace full of scantily clad harem girls. Maybe it's more like a salivating alien spotting a group of marines because I'm devouring books like crazy. The fulfilling kind of reading is not to speed read, but to immerse yourself into the book so deeply then the next moment you look up from the book, one hour had passed. If I didn't do anything else, at least this is something that I do consistently every night before I go to bed. Almost without fail. It's almost a luxury to be able to read half a day without the normal interruptions that life often throws at you.


7. Watching some tv, series, youtube or movies. This is to be taken in light moderation, because I don't like to spend too much time watching tv. But a good show can leave in me a very reflective mood and gets me thinking about lots of stuff. I think reading and watching are the two best way to feed yourself mental food to grow as a person. If you find that you are still the same person 10 years ago, then you've not been reflecting a lot. Watching a great show is like looking at a piece of art - it suddenly hits you that this and that can actually be connected in such a way and the possibilities will just leave you thinking about more stuff. Recently I'm watching battlestar galactica....as far as I grok, it's the best sci-fi ever.


I think if out of this 7, I can hit 3 each day, that would be a very joyous day already. Time is the great equalizer of all, because everyone will have 24 hours no matter who you are. How are you going to spend your 24 hours so that if you will live a life as fulfilling as it possible can, and without regrets? I leave you to that thought.

Saturday, November 06, 2010

Don't work. Avoid telling the truth. Be hated. Love someone.

I think there's great value in this speech. I reproduce it entirely from facebook where it is circulating. I think everyone should read it once to see if it makes sense to you. I love parts of it, though not all. This is written by Adrian Tan, author of The Teenage Textbook (1988). He was the guest-of-honour at a recent NTU convocation ceremony. This was his speech to the graduating class of 2008.


I must say thank you to the faculty and staff of the Wee Kim Wee School of Communication and Information for inviting me to give your convocation address. It’s a wonderful honour and a privilege for me to speak here for ten minutes without fear of contradiction, defamation or retaliation. I say this as a Singaporean and more so as a husband.


My wife is a wonderful person and perfect in every way except one. She is the editor of a magazine. She corrects people for a living. She has honed her expert skills over a quarter of a century, mostly by practising at home during conversations between her and me.


On the other hand, I am a litigator. Essentially, I spend my day telling people how wrong they are. I make my living being disagreeable.


Nevertheless, there is perfect harmony in our matrimonial home. That is because when an editor and a litigator have an argument, the one who triumphs is always the wife.


And so I want to start by giving one piece of advice to the men: when you’ve already won her heart, you don’t need to win every argument.


Marriage is considered one milestone of life. Some of you may already be married. Some of you may never be married. Some of you will be married. Some of you will enjoy the experience so much, you will be married many, many times. Good for you.


The next big milestone in your life is today: your graduation. The end of education. You’re done learning.


You’ve probably been told the big lie that “Learning is a lifelong process” and that therefore you will continue studying and taking masters’ degrees and doctorates and professorships and so on. You know the sort of people who tell you that? Teachers. Don’t you think there is some measure of conflict of interest? They are in the business of learning, after all. Where would they be without you? They need you to be repeat customers.


The good news is that they’re wrong.


The bad news is that you don’t need further education because your entire life is over. It is gone. That may come as a shock to some of you. You’re in your teens or early twenties. People may tell you that you will live to be 70, 80, 90 years old. That is your life expectancy.


I love that term: life expectancy. We all understand the term to mean the average life span of a group of people. But I’m here to talk about a bigger idea, which is what you expect from your life.


You may be very happy to know that Singapore is currently ranked as the country with the third highest life expectancy. We are behind Andorra and Japan, and tied with San Marino. It seems quite clear why people in those countries, and ours, live so long. We share one thing in common: our football teams are all hopeless. There’s very little danger of any of our citizens having their pulses raised by watching us play in the World Cup. Spectators are more likely to be lulled into a gentle and restful nap.


Singaporeans have a life expectancy of 81.8 years. Singapore men live to an average of 79.21 years, while Singapore women live more than five years longer, probably to take into account the additional time they need to spend in the bathroom.


So here you are, in your twenties, thinking that you’ll have another 40 years to go. Four decades in which to live long and prosper.


Bad news. Read the papers. There are people dropping dead when they’re 50, 40, 30 years old. Or quite possibly just after finishing their convocation. They would be very disappointed that they didn’t meet their life expectancy.


I’m here to tell you this. Forget about your life expectancy.


After all, it’s calculated based on an average. And you never, ever want to expect being average.


Revisit those expectations. You might be looking forward to working, falling in love, marrying, raising a family. You are told that, as graduates, you should expect to find a job paying so much, where your hours are so much, where your responsibilities are so much.


That is what is expected of you. And if you live up to it, it will be an awful waste.


If you expect that, you will be limiting yourself. You will be living your life according to boundaries set by average people. I have nothing against average people. But no one should aspire to be them. And you don’t need years of education by the best minds in Singapore to prepare you to be average.


What you should prepare for is mess. Life’s a mess. You are not entitled to expect anything from it. Life is not fair. Everything does not balance out in the end. Life happens, and you have no control over it. Good and bad things happen to you day by day, hour by hour, moment by moment. Your degree is a poor armour against fate.


Don’t expect anything. Erase all life expectancies. Just live. Your life is over as of today. At this point in time, you have grown as tall as you will ever be, you are physically the fittest you will ever be in your entire life and you are probably looking the best that you will ever look. This is as good as it gets. It is all downhill from here. Or up. No one knows.


What does this mean for you? It is good that your life is over.


Since your life is over, you are free. Let me tell you the many wonderful things that you can do when you are free.


The most important is this: do not work.


Work is anything that you are compelled to do. By its very nature, it is undesirable.


Work kills. The Japanese have a term “Karoshi”, which means death from overwork. That’s the most dramatic form of how work can kill. But it can also kill you in more subtle ways. If you work, then day by day, bit by bit, your soul is chipped away, disintegrating until there’s nothing left. A rock has been ground into sand and dust.


There’s a common misconception that work is necessary. You will meet people working at miserable jobs. They tell you they are “making a living”. No, they’re not. They’re dying, frittering away their fast-extinguishing lives doing things which are, at best, meaningless and, at worst, harmful.


People will tell you that work ennobles you, that work lends you a certain dignity. Work makes you free. The slogan “Arbeit macht frei” was placed at the entrances to a number of Nazi concentration camps. Utter nonsense.


Do not waste the vast majority of your life doing something you hate so that you can spend the small remainder sliver of your life in modest comfort. You may never reach that end anyway.


Resist the temptation to get a job. Instead, play. Find something you enjoy doing. Do it. Over and over again. You will become good at it for two reasons: you like it, and you do it often. Soon, that will have value in itself.


I like arguing, and I love language. So, I became a litigator. I enjoy it and I would do it for free. If I didn’t do that, I would’ve been in some other type of work that still involved writing fiction – probably a sports journalist.


So what should you do? You will find your own niche. I don’t imagine you will need to look very hard. By this time in your life, you will have a very good idea of what you will want to do. In fact, I’ll go further and say the ideal situation would be that you will not be able to stop yourself pursuing your passions. By this time you should know what your obsessions are. If you enjoy showing off your knowledge and feeling superior, you might become a teacher.


Find that pursuit that will energise you, consume you, become an obsession. Each day, you must rise with a restless enthusiasm. If you don’t, you are working.


Most of you will end up in activities which involve communication. To those of you I have a second message: be wary of the truth. I’m not asking you to speak it, or write it, for there are times when it is dangerous or impossible to do those things. The truth has a great capacity to offend and injure, and you will find that the closer you are to someone, the more care you must take to disguise or even conceal the truth. Often, there is great virtue in being evasive, or equivocating. There is also great skill. Any child can blurt out the truth, without thought to the consequences. It takes great maturity to appreciate the value of silence.


In order to be wary of the truth, you must first know it. That requires great frankness to yourself. Never fool the person in the mirror.


I have told you that your life is over, that you should not work, and that you should avoid telling the truth. I now say this to you: be hated.


It’s not as easy as it sounds. Do you know anyone who hates you? Yet every great figure who has contributed to the human race has been hated, not just by one person, but often by a great many. That hatred is so strong it has caused those great figures to be shunned, abused, murdered and in one famous instance, nailed to a cross.


One does not have to be evil to be hated. In fact, it’s often the case that one is hated precisely because one is trying to do right by one’s own convictions. It is far too easy to be liked, one merely has to be accommodating and hold no strong convictions. Then one will gravitate towards the centre and settle into the average. That cannot be your role. There are a great many bad people in the world, and if you are not offending them, you must be bad yourself. Popularity is a sure sign that you are doing something wrong.


The other side of the coin is this: fall in love.


I didn’t say “be loved”. That requires too much compromise. If one changes one’s looks, personality and values, one can be loved by anyone.


Rather, I exhort you to love another human being. It may seem odd for me to tell you this. You may expect it to happen naturally, without deliberation. That is false. Modern society is anti-love. We’ve taken a microscope to everyone to bring out their flaws and shortcomings. It far easier to find a reason not to love someone, than otherwise. Rejection requires only one reason. Love requires complete acceptance. It is hard work – the only kind of work that I find palatable.


Loving someone has great benefits. There is admiration, learning, attraction and something which, for the want of a better word, we call happiness. In loving someone, we become inspired to better ourselves in every way. We learn the truth worthlessness of material things. We celebrate being human. Loving is good for the soul.


Loving someone is therefore very important, and it is also important to choose the right person. Despite popular culture, love doesn’t happen by chance, at first sight, across a crowded dance floor. It grows slowly, sinking roots first before branching and blossoming. It is not a silly weed, but a mighty tree that weathers every storm.


You will find, that when you have someone to love, that the face is less important than the brain, and the body is less important than the heart.


You will also find that it is no great tragedy if your love is not reciprocated. You are not doing it to be loved back. Its value is to inspire you.


Finally, you will find that there is no half-measure when it comes to loving someone. You either don’t, or you do with every cell in your body, completely and utterly, without reservation or apology. It consumes you, and you are reborn, all the better for it.


Don’t work. Avoid telling the truth. Be hated. Love someone.

Friday, November 05, 2010

Life in monochromatic hues

I'm having some difficulty adjusting myself to a more relaxed pace. It's quite interesting because when I was having such a hectic schedule, all I wanted was to have nothing to do. But as I am currently in this slower pace of life, what I wanted was to be busy again. It's hard to please, don't you think? I recognise that I'm complex and sometimes, certain mood takes over me and I'm self-contradictory. Occasionally.


How do I know that life is slowing down for me?


1. My handphone battery suddenly lasts much longer than normal. I used to charge it everyday because of the amount of sms that I sent and the data roaming that uses up a fair bit of battery life. However, as of now, I haven't charged my handphone for nearly 2 days. It's coming to 38 hours of no-charging already and the battery life is still a good 50%. Even my handphone is slowing down.


2. I no longer had to scan my emails. I get many many emails a day from brokers, roughly 100 per day on weekdays. I cannot physically check every one of them because I don't have the time to do so. But recently, I am checking more frequently than my emails are coming in. I haven't really got down to reading each and everyone of them but it's getting there.


3. I'm blogging much more often than in the past. When I'm not occupied by normal routine, I think a lot and reflect a lot. I think because of this, I had much more things to say than in the past when all I'm occupied was to get home and have a good night's sleep. This is, of course, not necessarily bad. To be able to indulge yourself in your own thoughts is quite an enjoyable thing, every now and then. Everything in moderation is good.


we all have our down and vulnerable moments


I'm not really complaining that I've nothing to do. It's just that perhaps this is the first time I noticed that things are slowing down for me. I can't remember why I didn't have this feeling earlier because the life of a private tutor is like a farmer - there are times that you work like crap and after harvesting your work, you plant the seeds and then...you wait. And this is only less than 1 week of rest and relaxation and I'm feeling like this, which is weird. I will definitely ride through this lull period, as I always have. I'm highly experienced in this kind of boom bust cycle because technically, I'm always retrenched towards the end of the year and when the next year starts again, I'll have to work my way up to the previous year salary and perhaps more if I want some bonus.


I just want to encourage my bro to take things in stride, don't fall into depression and we'll take care of you in what ways we know. So, cheer up and I'll do my best to help out :)

Thursday, November 04, 2010

A rose by any other name smells as sweet

** "BIAS" is a special feature in my blog where I get to say whatever I want with scant regards for your feelings. I'm not politically correct in this feature, so go ahead, judge me."


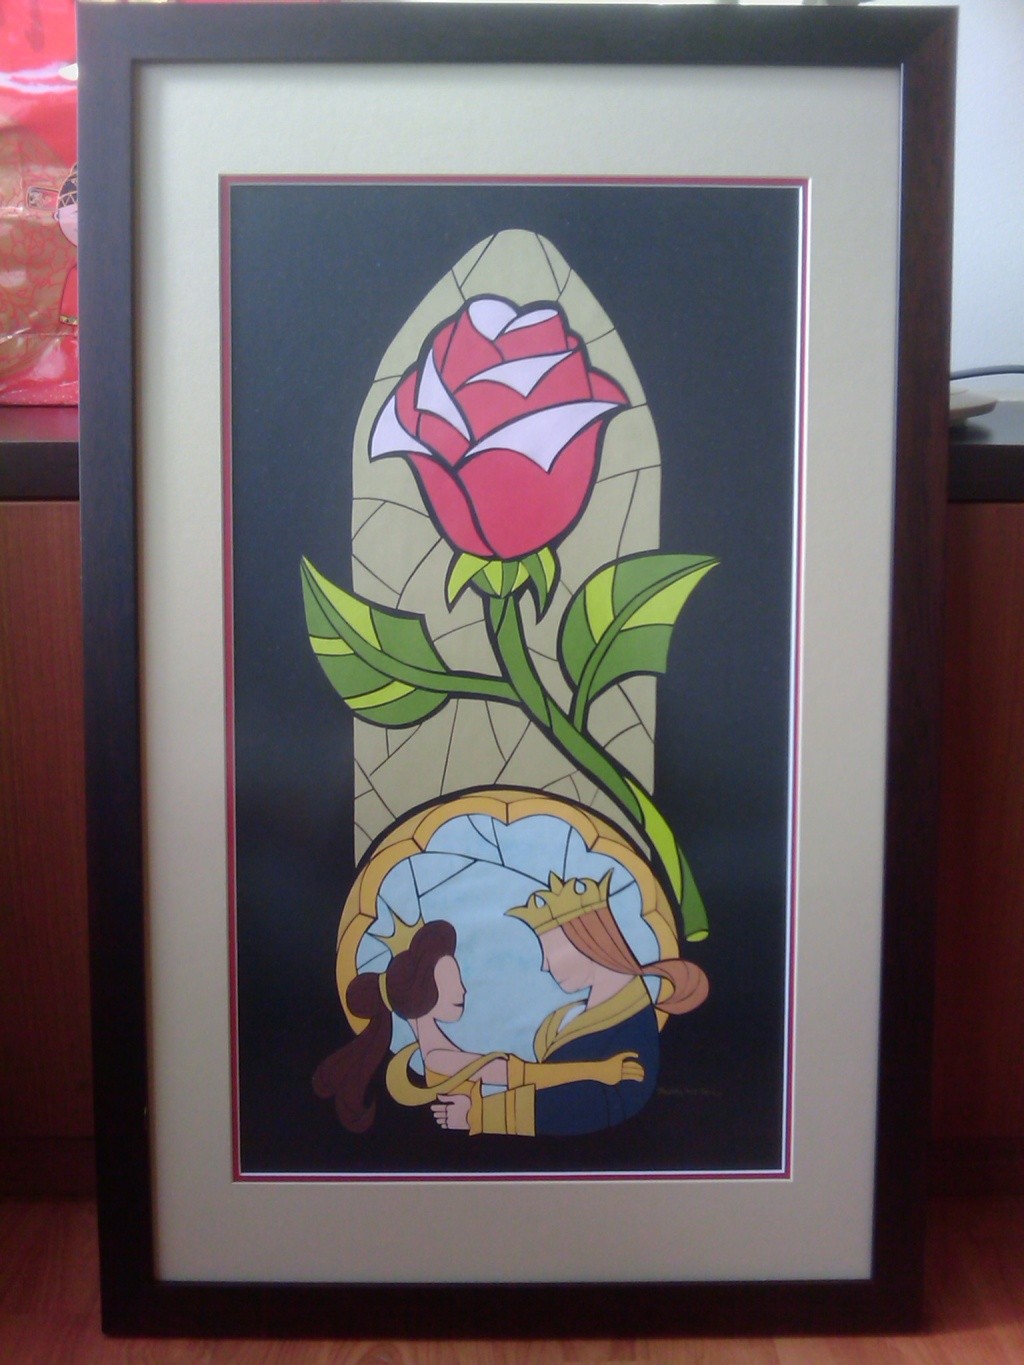
During my wedding, I put up a portrait of a rose à la beauty and the beast instead of the usual picture of me and my wife. It had attracted quite a fair bit of attention and even the banquet manager asked me about it. Actually we wanted to bring it up to the stage to talk about it but I thought it's just too troublesome, so here I am to blog about the origins of this mysterious portrait, haha! I can't remember exactly the date but I did remember the year in which it all happened. It was in 2006 when I first decided to do up this project.  We loved beauty and the beast and the ideal behind the whole story and I promised my wife that on the day of our wedding, we would have this picture of beauty and the beast out there for everyone to see.


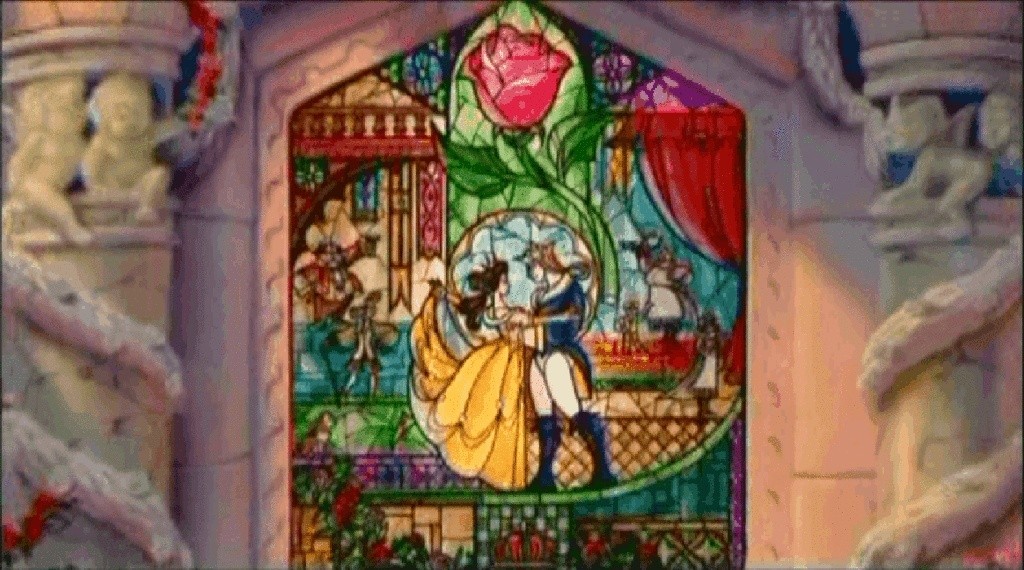
4 years had passed and I didn't do much about it until the start of this year 2010. I started conceptualizing the idea in 2007 and had a good idea of what to do. I wanted to re-create the glass stain effect but using cut pieces of coloured paper and pasted onto a black cardboard.  The end result should look somewhat like the picture below. However, I can foresee the difficulties involved and decided to do a scale down version of this, so I just took out the key and central idea of the picture, which is the rose, beauty and the beast.


The original idea is like that, but I realised it's too difficult to pull it off


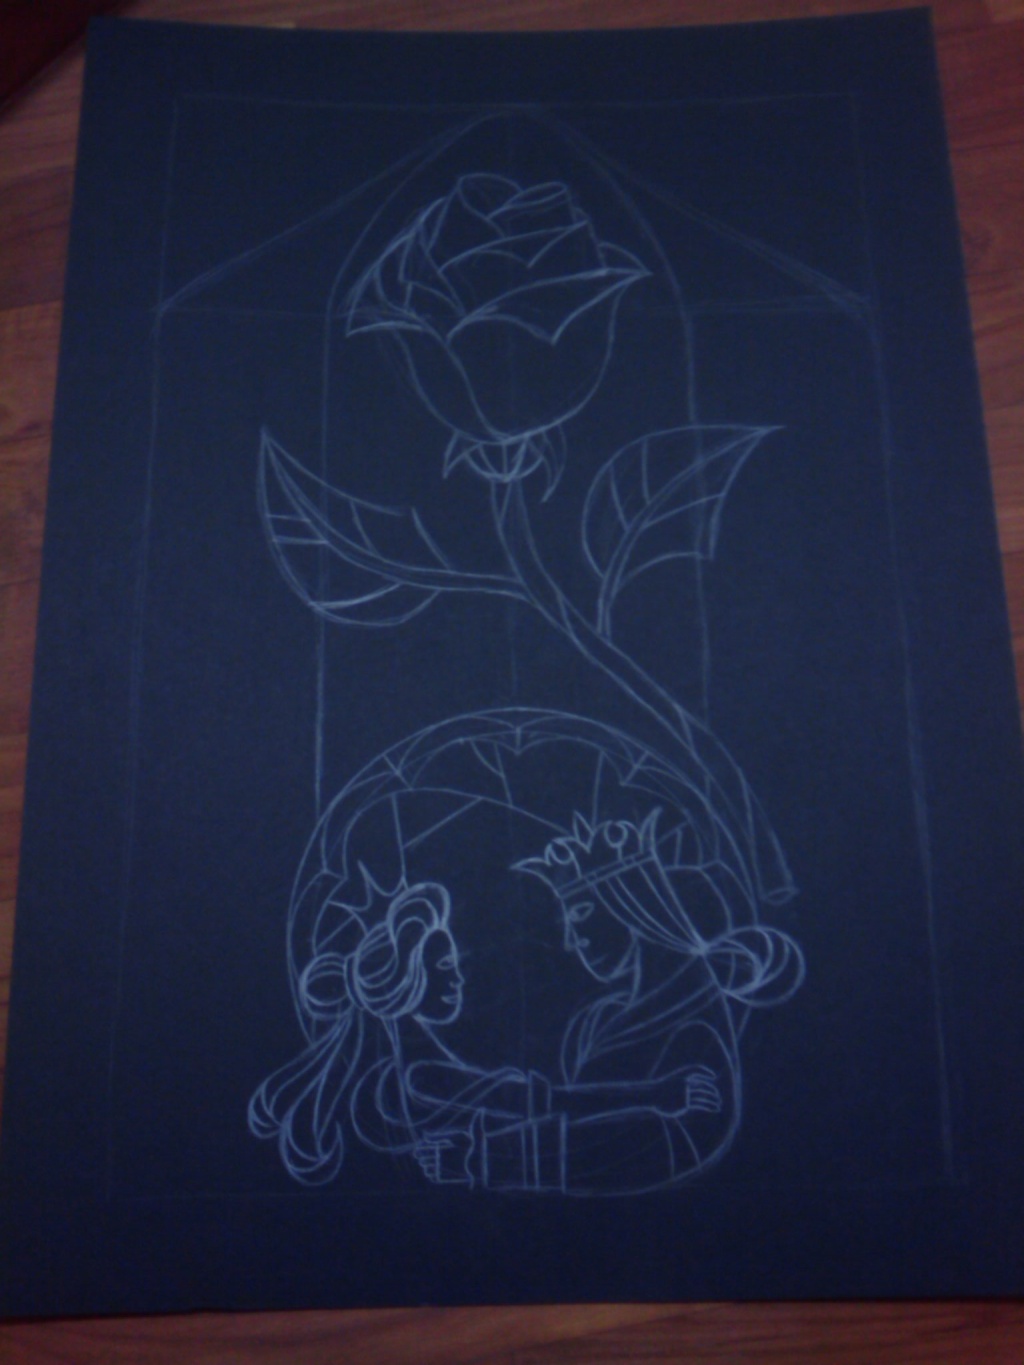
I bought the piece of black cardboard in 2007 (I kept the receipt!) and bought the materials needed, but it wasn't till earlier this year before I actually started doing it. All the while I was procrastinating because I'm not confident that I can pull it off. That was before I even had the idea of marriage so I think it's understandable. But as I'm more sure of our eventual marriage, I can't delay it further. I sketched out the general outline of how the whole project should look like:


Sketched out onto the cardboard. Decided to just focus on the central idea of the picture.


I decided to do up the rose part first. It's quite screwed up, on hindsight because I was experimenting with how to actually cut pieces of paper and paste onto the outline sketched onto the cardboard. I finally decided on using tracing paper to trace out the outline again, then transferring the lines onto the coloured pieces of paper, cut it out and paste it. In a way, I'm creating my own carbonated paper by using tracing paper. Here's a few pics of the rose part. I loved the brilliant colours!


Thereafter I went to reservist... it took me quite a few more months to get my ass back to work on the project again. I think having done the rose part is itself a motivation for me to continue. I've no idea on how the overall project would look like because I'm doing section by section and deciding what colours to use based on the overall feel of the colours combination. As I continued to the beauty and beast section, I screwed up again. This part of the project requires a different skill set from what I did for the rose part. The cut pieces of paper are so tiny that it's very difficult to cut properly (I can't even hold it using 2 fingers). I don't even want to think about how to paste it since I can't hold it properly. In the end, I've to make do with a toothpick to position the cut coloured pieces of paper onto their proper places on the cardboard.


Having done the hardest part of the project, the rest is smooth sailing. I agonized over the choice of colours to be used for the backdrop on the rose section to give overall compatibility in colours, and eventually I settled on this particular olive green colour. Quite pleased with myself :)


The final look of the project looks like this:


My mum helped me to select the colours for the frames and the margin around the picture. This is what is seen on the wedding night itself, displayed on an easel.


How's that for a 4 years project? haha :)

Wednesday, November 03, 2010

Supporting the family

** "BIAS" is a special feature in my blog where I get to say whatever I want with scant regards for your feelings. I'm not politically correct in this feature, so go ahead, judge me."


This is from a author of a children book that I like very much. It's called Different dances by Shel Silverstein. The funny thing about children books is that they are never really meant for children. That's what I learnt when I started reading about sci-fi and watching sci-fi series (Battlestar Galatica, if you must know) - the background just serves as a context for telling something important, so you can mask the seriousness of the issue by putting it in any backdrop. As a result, I always loved children books because they are really simple and full of nice pictures to look at.


I think I can really understand the stress of a single income family. There's not only the physical work that comes with working hard to provide for the family, there's also the mental stress involved. I can emphasize with the strip because I also think there are three groups of people to take care of. They are:


1. Your immediate family, which includes your spouse and children. The strip only shows 2 kid, but if there's more than two kids coming along, the man will 'sink' faster.


2. Your parents. Actually the strip also didn't include both sides of the parents, so that's two extra person on top of the man. Again, I think the man would sink faster than what is really shown here.


3. Yourself. I think that this is usually the most neglected of all. Maybe it's just me, because I tend to neglect myself and put others above me. I got to learn to be a little less responsible and pamper myself more.

CPL

Capitaland CPL

For self reference.

Weekly:


Daily:


Tuesday, November 02, 2010

50k challenge - repeated!

Yesterday, I've finally put in the last bit of money to top up my savings to 50k for the year. Somehow I've felt that this year differs greatly from the previous year. I've blogged about my feelings after I've achieved the 50k challenge, so I thought I should do it again now. Here's the few things that I find which differs from what I felt last year:


1. Achieving the 50k challenge doesn't give me as much satisfaction as before.


Somehow I felt that the satisfaction part is missing. Perhaps I've already done it before so the sense of achievement is no longer present. But I think most likely I find that my 50k challenge is no longer a challenge because I've been there done that. I've also set myself a greater target which I've blogged about here - 100k. I don't think I can do it by next year, but hopefully if all goes well, within the next 2-3 years. Crazy right, 100k? Well, if it's not crazy, it's not a challenge isn't it?


2. Reaching there isn't as hard as last year


I remembered last year that I had to struggle greatly to reach my monthly savings target. Since it's progressive, it means that as each month goes, it gets harder and harder to reach the target. It's quite stressful and I have to complain and whine about it to my ex-gf (present wife, haha!). However, this time round, I already had a very clear and realistic idea of what I can do and what I cannot do. I don't remember pushing myself too hard to reach my targets...it's more like drifting towards a general direction instead of swimming furiously there. I think this state of mind is a more sustainable one that the one I had last year. I should also mention that I had a lot a lot more fun this year than I had last year. I definitely spend more money this year and pampered myself a lot more. It's better to reach your target happy rather than limping through it in pain.


The climb to the summit this time round is a lot more enjoyable than the previous year


I think I'm having a glimpse of what it must have been like to be financial independence. I can work when I want to now instead of working to make a living. It's a kind of joy and 'lightness' in the heart that is hard to describe. I think I'll take a break for a week or so until I'm bored, then I'll start lightly to earn some income to spend for the next two months. You know what? The best thing about the 50k challenge is that I do not have to save any amount after I achieved that target. If I earn $100, I can spend that $100 freely without worry. Sorry if this sounds weird, but I usually don't have this luxury at all.


Having gone the offensive to work and save 50k, it's time to defend the 50k from being used up by daily expenses. I will try my very best not to use it at all except for the purpose for which it is meant for (i.e. marriage which also includes a honeymoon, housing and flat). As long as I work a few hours per week, it shouldn't be too much of a problem to cover some fixed expenses and a little more for my own spending. But I think I deserve a break and I'll worry about it one or two weeks later. Or until I'm bored, whichever comes first :)

Monday, November 01, 2010

My 2 new credit cards

As I opened my mail box together, I was pleasantly surprised to see two thick packages sent to me. As suspected, there are the 2 credit cards from Citibank that is mailed to me when some very persistent salesmen tried persuading me to sign up for credit cards. Since that guy is so sincere and very helpful, I decided to give him the commission by applying (I heard that they will get something by sending in an application form, regardless of whether it is approved or not) for 2 cards, knowing fully that the applications will be rejected.


Hence, when I received the cards, I was quite surprised. To those readers who have been following my posts, my only credit card is the POSB everyday card. Somehow, after been rejected from various banks, I got that POSB card application accepted, then followed by another strings of rejection. Until today that is.


One of the cards is the dividend card. I read through the brochures that there's some cashback given in the form of cheques when you accumulated enough. Something like that. This makes it quite similar to my POSB everyday card except that for the POSB card, you don't have to wait for the rebate to be sent to you since it's already 'stored' inside the card and you can use it to offset your bills anytime.


This is the dividend card. I can't find the Joy x10 card, so I assumed it to be newly launched


The other seems to be a new card by Citibank, called the Rewards card Joy x10 or something. It's those cards where they don't give you cash rebate but rather points. The difference is that this card gives you 10 points for every $1 spent, hence the moniker "Joy x10" I think. I think we can broadly classify credit cards goodies by two groups - one accumulates points in exchange for vouchers or gifts. The other gives you cash rebates, so that if you spend say $100, they will give you 50 cts back in cash. You can use the cash for anything you want.


Which one do I prefer? The cash rebate of course. With the cash, you don't have to be tied up by their reward program and you can use it anyhow you like, so cash is definitely better than rewards point. I'm very happy to keep using my first 'love' POSB everyday card because it serves my needs pretty adequately. I guess I'll just be using the Citi cards when it gives me discounts off my dinning bills, which is one of the good advantages of using credit cards. If you're like me who had problems getting even one tiny card no matter hard you try, you'll appreciate the discounts a little more. However, I'm actually more happy that the institutions are seeing me as more credit worthy now than before, which is always a good thing.


Will I spend more now that I've three cards under my name? Nah, don't think that's very likely. I'll probably save more by having more discounts, haha!

Friday, October 22, 2010

My first IPO - After Action Report

Despite being in the market for like 4-5 years, I've never played any IPO before. I used the word 'play' because since all IPOs are described in the prospectus as the best company ever listed, and there are no history of any price to do any TA, the only way to make a buck is to punt and to speculate. I applied for the Global Logistic Prop Limited (known as GLP) and got myself 1 lot. Actually it's half a lot because I shared with my father, who don't have any account with CDP, hence he can't apply it.


The IPO price was top of the range at $1.96 per share, but there's a pedigree name behind it - GIC. Since Ah gong is giving us money in the market, I say we take it. I believe many others are thinking along the same line too, so just whack and see how many lots we'll get. At least for GLP, the retail tranche is much bigger than MIT, so for those who applied, most will get at least 1 lot. Nothing much but better than nothing. On the other hand, I've not heard of anyone who got MIT. I applied for around 30 lots but got back nothing.


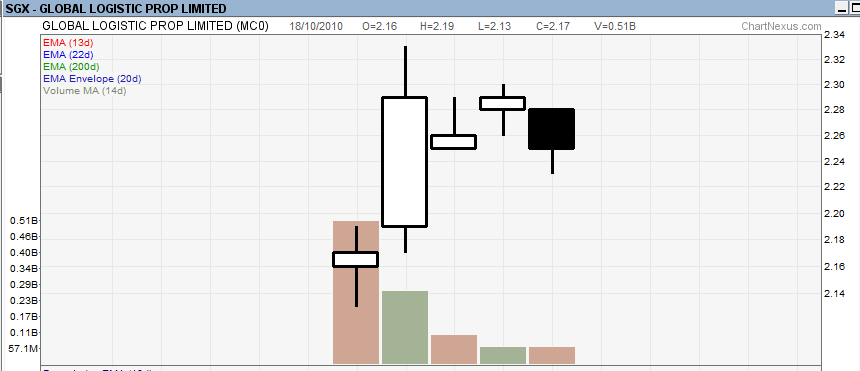
I eventually sold it at 2.17 very early in the morning, about a few minutes after 9am. I had studied the past IPO performance and decided before debut trading that this is unlike the pennies IPO (around 20cts to 40 cts range). Those have around 20-30% gains on the first day before sliding down. GLP should be around the performance level of Tiger airways (IPO price 1.50, highest of the debut trading is 1.60), which is around 6-7%. Taking 7% of the IPO price of GLP, I get around 2.10, so that's my target price.


Price of GLP for the last 5 days


I woke up early in the morning at 830am to prepare myself to sell it off and was surprised to see that there are many married deals (marked with x next to the transactions) even before market opens. The married deals are around the range of 2.10 to 2.15 so I knew it must be a hot IPO. Since the opening price is already above my target price, I just queued at the next bid at 2.17. Within seconds, I got my order filled and I'm out of the game.


All in all, it was quite an interesting experience since I've never had an IPO before. I got 9.19% after all commission charges and application fee and taken into account, which is not a bad deal even though I got only $90 out of it (half of which is shared by my father). The price can continue to go up, but it doesn't affect me because I'm happy to exit at a price higher than my target price. This kind of punting game wouldn't make me richer nor poorer, so it's best not to think too much about it.


I think I've enough of IPO for now, since I didn't get any MIT. There are a few more IPOs coming up, and no doubt they will be hot. But I don't think I'll subscribe to them. Let others take the thrill. Interesting, there's no seller's remorse nor buyer's 'high' after this IPO. It's just slightly irritating because I've to wake up earlier than normal to watch prices tick on the market so that I can sell. I think I've changed a lot since I started this stock market thingy.

Thursday, October 21, 2010

Quit whining and start going

The wedding is seriously stressing me up. There's so many things to be done and suddenly I felt that I was the only one handling things. I wasn't the one who wanted to have it and now it feels that I'm being pushed to do the bulk of the adminstration and left to pay the bills too. It's a show that I am forced to do and nobody seems to enjoy it. Still, I must step up to the challenge and soon it'll be just another notch in my belt.


In view of the stress building up, I started doing my "things to do" list, broken up into different priorities and mentally dividing them into things that I can control and things that I cannot control. I realised that the most frustrating ones are those items in my checklist that I cannot control and have to wait for others to catch up with me. This is something that I realised about myself - I don't like to wait for people to catch up and I like to determine the direction and pace of things. As such, being a lone ranger will be easiest for me and least stressful while being a team player I will have to play the role of leader or the leader will have to move faster than I can do. I think this is an important realisation for me because I'm so used to doing things my way, so I definitely need to learn how to relax and let things flow their way.


Drink some wine and whine, then have a hangover and cry


I think the ups and downs of the stock market made me more 'zen', in the sense that I can just snap my fingers and get on to business (okay, not as easy as I make it to be, but it's much better than say, 5 years ago). Very good training ground for stress management and basically training to divorce yourself from emotions.


I also realised that complaining gives a limited release from the pressure. It's like treating the symptoms of the illness but not really the problem that causes the symptoms. The better thing to do is to treat the cause of the problem and remove that source, and that's what my "to-do" list is for. You can whine and whine and people will understanding and say good things to you to make you feel better, but at the end of the day, you still have to pick up the pieces yourself. So I say save the energy to complain and get to the business straight. About the only use of complaining is to release that pressure lid slightly so that the stress buildup will not cause an explosion within you.

Tuesday, October 19, 2010

3 steps to success

As my work load lessens, I suddenly have the time to think about the crazy busy period that had just passed. 'Suddenly' because all the non-milestone exams (those not in A'lvls, not in O'lvls) finish on the same week, so I ended up having a lot of free time which I need to get used to. It was very liberating to end my workday with still so much daylight left.


I started to think about the differences between the better students and the not so good students. It's been a perennial problem for me to analyse each batch of students, hopefully to derive and distill some qualities about them that I can inculcate to myself and to others. I think the same qualities apply to success in general, rather than just academic success. Gf and I analysed it broke it down to just 3 steps:


1. Reading


Reading gives you brain nutrients, just like eating food gives you body nutrients. (Hmm, how about soul nutrients?) It's been my constant complaint that young people don't read these day. As a consequence of not reading, you find that the only source of information they get will be from things from internet (talking about the facebook and youtube variety) and perhaps TV. Without this habit of reading, it's hard to improve yourself beyond the beta version of the worldview that you had when you left formal schooling. If I have a kid, I'll definitely try to put in this habit because I think it's a very good determinant of success, especially so in formal schooling years. You'll be surprised that most students do not even read their textbooks, preferring to have someone to tell them the information (like me) or just ask someone. Silly isn't it?


I think reading will give you different sorts of mental models to apply to problems. Each 'subject' like maths, psychology, economics, philosophy, science, accountings...all gives different ways of thinking about things. Recently, I found that fiction is very very satisfying too and I had been neglecting that for years (I never read fiction again after secondary school).

----------------------------------
I came back and re-write this part because to make it more general, the first step is more of a learning attitude than just reading more. You can learn more by talking to people, reading about it from books or from internet as well.


2. Reflection


By reflection, I mean to think about events or information that bombards us everyday. In terms of education, it's to think about the worksheet you had just done and see why you got it wrong and if there are are places to improve on the answers. I remembered that I used to do a problem twice in different ways just to see which method is more efficient (it's a geeky sort of amusement for me as well). For example, there is a geometry rule that angle in a semi-circle will form a right angle triangle. When I read about it, I refused to believe it. So, I really drew many circles and started proving to myself, empirically though, that each of these rules are true. It was years later on when I realised that the knowledge that you had isn't yours until you had to fight for it.

I don't believe that it's really true, until I proved it to myself


I find that the reading good books makes reflection easier. If the information in the book leads to easy understanding, it leads to easy absorption and assimilation. Thereafter, it's easier to link up previous ideas that you have inside you to build up the connections between your mental models.


3. Action


Thinking and not doing will not lead to anything. There's a very interesting discussion in the cbox about the book title - Think and Grow rich. Of course thinking alone will not lead one to becoming richer, and most people would stop at the thinking phase. Getting down to do it is actually the last step.


Three simple steps to success, but it's not easy to do it at all. The steps can be re-iterated to get the desired results, like 1 and 2 can be looped until a desired solution is formed, or 2 and 3 can be looped until the desired results is produced, but you can't skip any of it.

Friday, October 15, 2010

Lending of scrips deposited in CDP

I'm once again interested in lending my scrips deposited in CDP (central depository) to earn some interest. I checked the borrowing rates, it's 6%. The lending rate is however lower at 4%. I suppose CDP will take the cut for being the middleman. I'm interested partly because I read that there are new rulings by the new chief at SGX regarding borrowing/lending of scrips, but I didn't read too closely. Something like making it easier for retailers to borrow scrips for shorting. Currently there are like 600+ stocks you can borrow for the the purpose of shorting.


After doing some casual research, I realized why I didn't sign up the last time when I was interested. You can only lend out eligible securities in the stocks held by CDP. Eligible securities is defined as securities:


a) where price is less than S$1, fifty thousand (50,000) or more units; and

b) Where price is S$1 or more, S$50,000 divided by price rounded up to the next units.


In any one of the Securities found in Appendix A of this circular.


That's quite a lot to begin with. I looked though my holdings and I don't seem to have so many lots of the same counter, so I dropped the idea. But for anyone of you who had a lot of scrips stored in the CDP, you can make them work a little harder by lending it out to anyone who wants to borrow it at a rate of 4% per year.


Looks as easy as that. Click a few buttons and get money sent to you


The fees for the lending of scrips can be calculated by the following formula:

Lending Fee = Rate % x Loan Value x Days / 365

Where Rate % = Prevailing lending rate
Loan Value = No. of shares x share closing price at end of each day
Days = Loan duration


I'll quote an example given by CDP for the purpose of illustrating the application of the formula. I certainly have no use for it now, but in the future, who knows? I'll just put it here for my future reference.


If the loaned securities are 10,000 XYZ shares and the lending rate is 4%:


Start date of Loan : 1/10/2001 (Effective date)


Return date of Loan : 4/10/2001 (Expiry date)


Closing price on 1/10/2001 = S$10.00 Market Value of Loaned Securities = 10,000 x S$10.00 = S$100,000


Closing price on 2/10/2001 = S$10.20 Market Value of Loaned Securities = 10,000 x S$10.20 = S$102,000


Closing price on 3/10/2001 = S$10.40 Market Value of Loaned Securities = 10,000 x S$10.40 = S$104,000


Daily fee computation

 
Fee accrued on 1/10/2001 = 4% x S$100,000/365 = S$10.96


Fee accrued on 2/10/2001 = 4% x S$102,000/365 = S$11.18


Fee accrued on 3/10/2001 = 4% x S$104,000/365 = S$11.40


Lending fee = S$10.96 + S$11.18 + S$11.40 = S$33.54

Thursday, October 14, 2010

Warning bells are ringing?

With STI coming to 3200, I can almost hear the silent (and maybe not so silent) cheering for the market by people in the forums or in this cbox. With the number of unique users in the blog climbing up steadily, it meant only one thing - that we're back in the bullish period again. Have people started selling their mothers and mothers-in-law to get a bigger stake to play the game? I think not, but perhaps we'll see it coming soon.


One of the most obvious signs of market overheating is when newspaper start reporting, with bullish tones no doubt, that market had reached yet another high. This is precisely the warning bells that one must be aware of when staking your money in the stock market. Call me a perm bear if you will, but I would rather be cautious when others are so fearlessly chasing the oh-so-high prices. I don't know how people can whack the recently launched Yamada Green resources to make it reach above 60+% on debut, above IPO price. I've not seen such things for a very long time since I'm in the market. The last I saw such things, I was a newbie chasing after high prices and being the last one to leave the party, holding the hot potato.


What are some of the warning signs:


1. Newspaper reporting people with no knowledge or skills, perhaps students, playing the market and earning thousands in a day. Some might go as far as thinking of quitting their jobs to go full time because it's such easy money. When the majority are making money in the market, it's really time to leave the party.


2. You'll see many IPOs rushing to launch itself. Companies are not stupid - why sell equities when the times are bad and they can't get good money for them? Government related companies might try their luck too. Singtel IPO was just before the dot com bust, if you remember.


3. You go to public area and see people reading books on market. Esp trading books, because it's perceived to be easier than investing fundamentally. In truth, it's not, and it requires just as much hard work as investing. I remember watching a couple at mac discussing what stocks to buy for the coming week, the table full of charts and figures.


4. You see champions talking on TV and forums, well, like champions. The moment they remove fear out of their discussion, as if the market will continue this way forever, full of confidence because all their recent picks are all winners - ah...we had better slowly exit before the mad rush out of the party begins.


5. Analyst started using PE ratios instead of PB or NAV in their reports. I started an article on this way back  when I noticed the terminologies used in reports vary according to times. They must have something to write, so the emphasis to sell their point will vary according to the times.


I'm a net seller these few months, taking out more money than putting them into the market. If the market allows me to remove stuck positions, I'll gladly and gratefully do so with no remorse. In the meantime, I'll be very careful before adding new positions. Based on bro8888's latest article on the different types of animal, I think I'm a cross between a bo chup bull and a bearish bull wanting to be a bullish bear. Yea, I'm complicated.

Tuesday, October 12, 2010

Up and coming IPOs

As market marches upwards, we'll see IPO in fashion again. What's scary is that my parents asked me about it too, as they mentioned that their money in the bank is idling, so they might as well make some use of it. If my non-investing parents are saying this, there must be others who are eager to do it too. Ignoring my tingling spidey sense for now, let's see if it's worth a shot at it. I'm not interested in the fundamentals of it, but as the IPO suggests, It's Probably Overpriced. It's definitely not for keeps too. Trading? That's not enough data to do anything from it, so let's analyse it from statistical point of view.


No companies worth its salt would want to do an IPO when times are bearish, because their shares would be sold at a lower valuation than in a more bullish environment. The fact that we're seeing the gahmen selling off their stake in the upcoming IPOs must be indicative of bullish times. Whether that party would end soon, I don't know, but since I'm already at the party, might as well take some calculated bet. I did a post on IPO before, it's found here. In it, I stated that the chances of doing a quickie (defined as selling on first day of trading) is quite high. Let's add three more data points:


As can be seen, the most recent IPO samples that we had did very well on their first trading day before crashing down. This can be seen on their charts. The 4th one on the lower right is TTJ, IPO price 0.200, trading on 1st April 2010.


Taking the first day data, I calculated the gains made by making an assumption - the selling price is made at the lowest price of the first trading day:


Leader Env - 7.1% gains
Consciencefood - 31.8% gains
Yamada green - 61.4% gains
TTJ - 5% loss


It seems like the chances of making a loss is quite slim.  However, since all the trading price of the IPOs mentioned are around the range of 20 cts, but the upcoming IPOs are not in the penny realm, perhaps the gains would more muted.


Not a lot of shares are out there for GLP, so I think it'll be a catch 22 situation. If you get it it's no good, if you don't get it, it's good. The IPO closes on 14th Oct, 2010 at 10am and begin trading on Monday 18th Oct. If you're interested, you can go to ATM to apply or better yet, do it at the comfort of your own home using internet banking. Just go to the DBS/POSB account, log in and look for investment services on the left column. Then go to electronic security application (ESA) and click yes on the questions at the bottom of the screen. Follow the rest of the instructions and you'll see GLP, priced at 1.96.


Good luck!

-----------------------------------------------------------

Personal quick reference:

GLP : Deadline for IPO application 14th Oct 2010, listing date 18th Oct
MI :Deadline for IPO application 18th Oct 2010, listing date 21st Oct

Monday, October 04, 2010

How to kick start your savings plan?

Quite a number of people asked me how I managed to save in such disciplined manner. The equation of saving never changes: Savings = Income - Expenses. You can either increase your income, decrease your expenses or do both at the same time. I prefer the first method of increasing your income, because seriously how much can you cut from your expenses? There will be a limit to the numbers of needs that you can convince yourself to change to a want, and the flow of life will just increase your expenses especially once you have a family. As mentioned in a previous post, I estimated that you need roughly $2,650 expenses to have a comfortable life. Let's say you don't intend to have such a comfortable life and cut it down to $1,500. If you're earning 2k per month, I'll still say it's hard to save a lot by cutting expenses. The better way is still to see how you can increase your income instead.


But the purpose of the post here is not to give ways on how you can increase your income. Everyone's talents and strengths (and chances) are different, so you got to be self-aware of what you can do. If you're good in sports, maybe can you teach swimming on weekends to earn some extra bit. If you have excellent skills in bakery, perhaps you can sell some to neighbors and take orders during festivals. The point is that there's always something you can do if you put your mind to it. The best way is to monetize things that you do habitually into an income stream. You think about it.


I believe that if you do not know where you stand now, it's hard to set a suitable goal forward. I feel very uneasy when I asked these few questions to myself:


1. How much do I spend on food per month?

2. Out of the food expenses, how much did I spend it on restaurants?

3. How much do I spend on transportation?

4. Out of the transportation expenses, how much did I use it on cabs?


And questions like that. It makes me uneasy because from the money that I earned, I have no idea where it went to. I lead a very blurry life between 2003 to 2007 because I have no idea where my income goes to. At the end of the month, it seems like the money I get 'disappears' and I looked forward to the next paycheck. When I do have a sum of money, I will feel rich and buy myself something expensive to reward myself for the work well done. This goes on for years and despite working hard, I've nothing to show for in my bank account.


I felt increasingly uneasy until I finally took action to remedy it. The very first thing I did is to sort out how much money and assets that I have right now. In other words, I need to find out my net worth - how much assets I have and how much debts I owe. Since I do not have any debts at that time, it's just a matter of adding up the amount that I have in all my bank accounts, money in the money market fund, net value of my stock investments, cash surrender values of my whole life plans and CPF. I put it in an excel spreadsheet to see the changes from month to month so that I know to a great amount of accuracy (it's not 100% for sure, there will be some 'losses' but that's okay) where my money is sitting at the end of every month.


After doing up my net worth, I proceeded on to the monumental task of constructing my cash flow statement. In my line of work, my booked earnings is divorced from the cash that I actually get per month. This means that on one spreadsheet, I've to record down how much work I did on that month and on another spreadsheet, I've to record the actual amount of cash that I received. I also started recording my expenses to have an idea of how much I spend. I'm detailed in my recordings, because I would put in the amount that I spend and the categorized item (e.g. food, transport, parents, insurance etc) with a short comment. So if I spent $50 at Tony Roma's restaurant alone, I would put it under 'Food' catergory, with the comment "Tony Roma - alone". This is to track my expenses so that I know how much I spend on what at the end of each month.


Now isn't that very similar to companies too, where they have their earned revenues and cash flow statements? I thought it's the very same thing and started thinking of myself as a company and I'm the CEO of myself. I started doing this networth, cashflow, income statements after reading intensively about financial accounting to jumpstart my interest on investing as opposed to trading. 


Once all my 3 personal statements are up, I really sat down and started analyzing what went wrong with this 'company'. Why is it that I can make an income every month but at the end of 4 years, I've nothing much to show in my bank accounts? Now here is where the expenses can come in very handily. I think by looking at the cold hard facts of your expenses per month, you can see where all the leakages are in all its glory details. Perhaps you've been spending too much on drinks, perhaps you've been buying too many clothes, perhaps you've been ebaying too much. This fact finding exercise will remove all traces of faulty mental accounting that we will do all the time. Oh, I got a bonus this month so it's okay if I spend it on this plasma tv. Oh, I got some trading profits, it's enough to offset some losses I had and the change can be used to buy a new gadget. Some mentioned that this detailed tracking is too much for them...well, I would say it depends on how much and how desperate you want to know. I did a very detailed account of close to 6 months before doing a less detailed one from now onwards because I already know my spending pattern. The interesting thing is that initially I wanted to do it for only 3 months to have an idea but eventually it became such a habit that I extended the 'trial' for almost 2 years now.


I think after the fact finding exercises to determine where you stand currently, a plan to remedy it should already be materializing in your mind now. If you have the discipline to write down your all your expenses for 3 months and above, carrying out the plan to change your spending pattern should be a walk in the park. I think most people would give up on the expenditure recording part.


I came to the realization that I am not spending a lot of money on myself, and most of my expenditures are actually on three things - food, transportation and parents. Hence to limit my expenditures would be foolhardy, because there is a limit to how much I can cut. The only way forward to improve the financial health of me as the company, is to increase my topline - my earnings. I also realised that I can afford the little things here and there to reward myself (as I've always suspected, I'm a very horrible slavedriver to myself). I can well afford it and I should do it so that I can stay longer in this game. Having a very concrete understanding of my financial circumstances, I also made a few plans to have a merger & acquisition exercise towards the end of this month, an acquisition on property towards middle of next year and perhaps spinoff a new company (or two) in about 2 years time. All these need huge capital expenses and being a private company, I can't sell shares to the public at all. So what do I have to do?


The plan is easy enough though the execution is not at all. Just bloody save 50k per year for 2-3 yrs. There you have it - the method (work and save), the motivation (preparation of life's milestones) and the killer (me).


To summarise this very lengthy post:


1. Have an idea on where you stand financially at this moment

- Do up your net worth and cash flow, including the expenditure statements

2. Analyze your statements

- See where the leaks are and how to remedy them

3. Set progressive goals 

- Set action plans on how to reach these goals

Sunday, October 03, 2010

The little things

In my job, I can get to see really wonderful scenes of nature unfolding as I walk along the streets. The world is my office and the flowers, the trees and the living things are my colleagues. Recently, I've been taking out my mp3 player in my bag and started listening to it while walking alone to work. Being alone and being lonely are really two different things. You can be alone but never feel lonely, or you can be surrounded by people yet lonely. I think loneliness is a state of mind.


Anyway, equipped with my multi purpose handphone, I get the urge occasionally to take some really breath taking sunsets. This particular one takes place while I was walking along to another workplace around evening time. You can always tell that you'll have a beautiful sunset by looking at the orangey glow (if it happens) around that time. If the cloud cover and the angle that that the last rays of the sun is just right, the whole sky will be flooded by an orange glow which is perfect for taking pictures. Here's a few that I took quite a while ago:


The cloud looks like the temple of ancient Greeks, with the three pillars supporting the roof. Hey, looks like MBS??


After a few minutes of walking, the great drama of the sky plays out further


Breath-taking isn't it?


The pictures are breath-taking enough even with my sucky handphone camera, so can you imagine the real scene unfolding in front of me? This is really one of the things that I liked about my job. My gf always say that I'm simple minded and is easily amused/contented by little things. I agree. If we strip away the nonsense that surrounds our life, the little things are all that matters isn't it?


Did I tell you about the activity that I will do after a rainy day, especially at night? I learned of this from my very kind hearted gf, who will pick up snails that happen to stray away from their grassy territory into the man-made pavements. There are many people walking on the pavements and occasionally you'll see a crushed snail whose life is snuffed out by a big giant foot. I wonder why nature made snails with shells that are so easily crushed...it doesn't serve them any better by sailing along so slowly either. Imagine you are walking along the streets, ambling gently perhaps window shopping, then a huge feet just came from nowhere and crushes you to death. Quick death no doubt, but such a wanton waste of life.... As such, I will do my part to pick up snails that happen to be in the pavements. Pluck them out of the pavements, and teleport them to their intended direction (I hope) towards a grassy patch. They will be all frightened and retreat into their backpacked home but at least they will be safe.


What's the purpose of this blog post? Nothing, haha :) In a rare rojak of events that happened, I am not working on a Sunday so I can afford some luxury thinking about the little things that happened in my life. If you see someone picking up snails after a rainy day at night, it could well be me.

Friday, October 01, 2010

SIA bonds oversubscribed

Sfry, a regular at the cbox, put up a link on the enthusiastic subscription of the recently launched SIA bonds. The bond carries a coupon of 2.15% pa and matures over 5 yrs. To subscribe for it, you need to have a minimum of $10,000 though you can buy off the market (it starts trading on 1st Oct 2010) at around $1k, depending on the price.


I'm just wondering why there are so many subscribers to this. I think one of the main reason is that people are getting the super lousy returns from savings deposits of 0.125%, so this SIA bond of 2.15% seems like heaven sent. Retail investors must be very frustrated with the measly returns they get from the banks, given the low interest rate environment. Recently I was also shocked to learn that the fixed deposit rates for a particular bank gives the same returns for 5k to 1mil if you compare the same periods of lock-up. I thought that the more you put it the better the returns? Apparently not anymore.


I believe that there are so many equally stable alternatives to the rather undesirable SIA bond (to me, at least), but the difference lies in the liquidity of that particular alternative (or the lock up period, so to speak):


1. CPF


Bro8888 mentioned in one of his post that his colleagues asked him if this is a good idea to invest their monies in. He mentioned that by putting it in the risk free SA account, you can get 4% already, so what's the big deal right? The bad thing is that by putting extra money into the CPF, you can put in but you can't take it out, so careful planning have to be done. This is definitely not for people who needed to use the money in the short term because the only time you can withdraw the money is when you touched the withdrawal age, which is increasing all the time. CPF is also subjected to 'government risk', so changes in the policy regarding CPF will affect all CPF members.


2. Preference shares


If you take a look at just those preference shares alone in Singapore, there are quite a few gems that offer greater returns than the SIA bonds.


Disclaimer: Do read up more on the preference shares, their yield may not be what is displayed on the name


Again, with higher returns comes greater market volatility in terms of price. I remembered seeing the price of these preferred shares plummeting in the deepest of the crisis. Just take a look at the historical charts of these preference shares and you can see it. Personally I didn't see it as something bad, unless you happen to want to cash out during the deepest crisis. I see it as a chance to get more below the par value, so when they start redeeming your bonds at par value, you not only get the coupon payment throughout the holding period but also book a good capital gains. But do buy those from companies you can trust. The capital guarantee upon maturity is only as good as the standing status of the companies.


Take a look at the OCC 3.93% NCPS 10, trading at 94.60, it's quite a good one compared to SIA bond. First of all OCC stands for OCBC...Singapore banks, so I think it's as safe as SIA, if not safer. 3.93% yield is on the par value of 100, since the price now is 94.60, you'll actually get a yield of 4.15%. NCPS stands for non-convertible (or cumulative) preference shares, meaning that you can't exchange it for ordinary OCBC shares nor can the payments be accrued to the next payment date should they decide not to payout on this payment date. The payments are not guaranteed, unlike the bonds, but it's almost as good as a guarantee. You can read more about the details here. Do read more about it, because I know that some preference shares change their yield after a certain date, so it might not be the 3.93% coupon rate displayed on the name of the counter.


Most of the other preference shares are trading at 5-6% yield, even after taking into account their price which is trading at higher than par value. Can really take a look at these alternatives seriously.


These are the few alternatives that I can think of. Of course there are other investments that gives dividend yield much greater than the 2+% given by SIA bond, but those are different classes of assets with different risk altogether. I would gladly wait for more bonds to be traded on SGX to see if there are better investment ideas now that SIA started the ball rolling. Price matters a lot in all cases because buying even the most riskiest product at a super cheap price can turn out to be a profitable and not-so-risky experience. I would wait for SIA bond to go around 0.70+ to get a 3%+ yield before entering. Don't laugh at me, it just might happen within the next 5 years .