Friday, July 04, 2014

Is it worth it financially to reduce taxes through donation?

In Singapore, if you donate to Institutions of a Public Character (IPC), you'll get a 2.5 times deduction of the amount donated to your chargeable or assessable income. This tax deduction period of 2.5 times is extended in 2011 and will last until 31st December 2015.


I was teaching a student about tax because it's covered in the syllabus. The syllabus is actually quite simplistic, so I took the liberty to incorporate real life elements into the picture so as to show her what is the tax situation here in Singapore. I mentioned about the use of donations to reduce chargeable income and it carries with it a 2 times deduction to chargeable income. Well, I was wrong...they changed that to 2.5 times already and apparently I wasn't updated about that information. While teaching her, I was wondering if it's worth it to make donations to IPC such that your tax amount is reduced to more than the amount donation, including all the 2.5 times mutiplier.


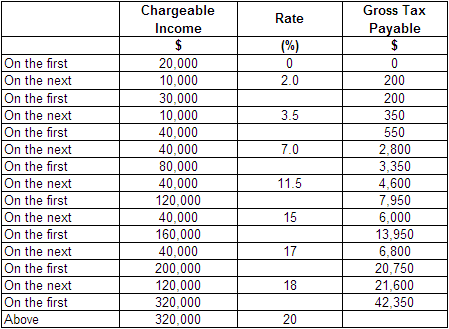
Here's the rates of tax for year of assessment 2014:


As you can see, the top tax rates for the highest income bracket is 20%.


For every $100 of donations, you get 2.5 times deduction to chargeable income, so that's a $250 deduction off your chargeable income. Below is the table that shows the amount of deduction to your taxable income, taking into the tax rates for different income brackets.


Chargeable Income (up to) Income bracket Deduction to tax
$30,000 2.00% $5.00
$40,000 3.50% $8.75
$80,000 7.00% $17.50
$120,000 11.50% $28.75
$160,000 15.00% $37.50
$200,000 17.00% $42.50
$320,000 18.00% $45.00
> $320,000 20.00% $50.00

The conclusion is something I didn't expect. If you're in the highest income bracket of 20%, earning more than $320k in year of assessment 2014, your $100 donation to IPC comes out to be $50 deduction to your tax. For those having lower income bracket, the final deduction to your tax is even lower than that. Before all these calculations, I would expect that there is a break even point where if you donate sufficiently large amount, you'll get to a point where it becomes financially worth it to do so. Nah, you're smart but the system is not stupid also.


Before you start flaming me, I'm just curious whether it's worth it financially to donate so that we can offset taxes. There's plenty of reasons to donate to a cause that you support, and knowing that it's not worth it to do so financially shouldn't stop you from doing it for other reasons. If anything, this small deduction to your tax is the cherry topping on top of your cake - let it be another reason, but not the sole reason, to donate to a worthy cause.


Okay, nagging doubt in my mind is resolved. 

Thursday, July 03, 2014

Starburst IPO

I happened to chance upon this soon to be IPO-ed catalist listed company called Starburst. I must have found what they are doing interesting because during my last reservist, I went to a indoor range with artificially controlled lighting (that means you don't have to wait for night for night shoots) and was suitably impressed with the construction and professionalism (I think they are run by CISCO) of the people there.


Business

Starburst is a Singapore based engineering group that specializes in design and engineering of firearms-training facilities. They have a track record of 15 yrs in the industry. Their 3 main business segments are


1. Fire arm shooting ranges - They design, fabricate and install their proprietary anti-ricochet ballistic protection systems for indoor, outdoor and modular live firing range, close quarter battle houses and method of entry training facilities. It's not stated anywhere that they are involved in the firing range that I went to in my last reservist, but from the pictures provided in the IPO prospectus, I'm quite sure they are involved.

2. Tactical training mock ups - They design, fabricate and install those simulations scenario, like sniper tower and counter terrorism operation training

3. Maintenance services and others - Basically design, supply and fabricate structural and architectural steel works, also maintain facilities.


Among the 3 segments, this is the one that is recurring in income. The other two are one-off and therefore their revenues are going to be lumpy. They stated that they are going to increase their maintenance services segment so as to provide more earnings visibility. I think that's a good move. The other business segments doesn't provide that kind of assurance to investors.


Revenue breakdown FY2013 FY2012 FY2011
Firearm shooting ranges 14639 (69.6%) 16188 (93.4%) 21211 (93.3%)
Tactical training mock ups 3460 (16.4%) - 351(1.5%)
Maintenance services and others 2946 (14%) 1149(6.6%) 1172(5.2%)

Ratios

Take a look at their ratios:

FY2013 FY2012 FY2011
ROE 33.7 47.7 72.6
Profit/revenue (net margin) 41.5 37.3 26.4
Revenue/Asset (asset turnover) 0.523 0.930 1.120
Assets/equity (leverage) 1.554 1.376 2.451
EPS based on post IPO share base 3.49 2.59 2.41

The kind of business they are doing certainly have huge margins! You're talking about 26 to 41% net margins here! ROE is a strong double digit for the last 3 years. I think in FY2011, the ROE is artificially raised because of the higher leverage which they used (look at their assets/equity of 2.451 in FY2011 vs 1.554 in FY2013).


EPS of 3.49 cts in FY2013, and their IPO price of $0.31, means that their PER is about 8.8 times, which is not excessive. What's the weighted average PE of STI index? It's 15.1, according to this. Starhub has a PE of 19.4 while DBS has a PE of 11.3, to give you a feel of the PE ratio of different big companies you know. The NAV before adjusting for the IPO proceeds is 12.94 cts, so the P/B is about 2.4. ST Engineering, a company with about the same industry as Starburst, has a PE of 20.4 and a PB of 5.29.


Revenue

FY2013 FY2012 FY2011
Revenue $21,045 $17,337 $22,734
Profit before income tax $10,107 $7,641 $7,145
Cost $10,938 $9,696 $15,589
Finance cost $82 $135 $308
Project/production cost $8,412 $6,682 $11,558
Net profit $8,729 $6,464 $6,013


Revenue is lumpy, given the variability of the contracts they can secure in their order books The cost seems very contained, giving them a very high profit margins. The majority of the cost is the project/production cost, accounting for about 70 to 80% of the cost. Take note that a majority of their employees are foreign workers (77% as of 31st Dec 2013), so they are also going to face the same issue as all SME with regards to the labour policy and shortage. 


Cash flow


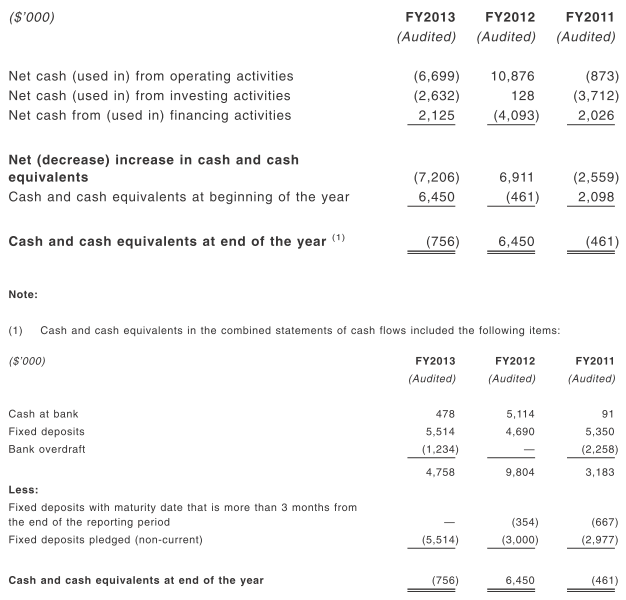
Operating cash flow is again lumpy, and highly dependent on whether they secure projects. The payment for the projects are based on percentage of completion, and the contracting party can retain 10 to 20% of contract sum upon completion of works in order for them to assess shoddy work or work-yet-to-be completed. I guess that's standard practice, like all construction firms. I'm not very good at analysing cash flows, so I won't even try. 

FY2013 FY2012 FY2011
Assets $40,212 $18,650 $20,291
Current  $24,690 $13,134 $15,471
Non-current $15,522 $5,516 $4,820
Liabilities $14,331 $5,096 $12,011
Current $8,953 $2,923 $10,070
Non-current $5,378 $2,173 $1,941
Total equity $25,881 $13,554 $8,280

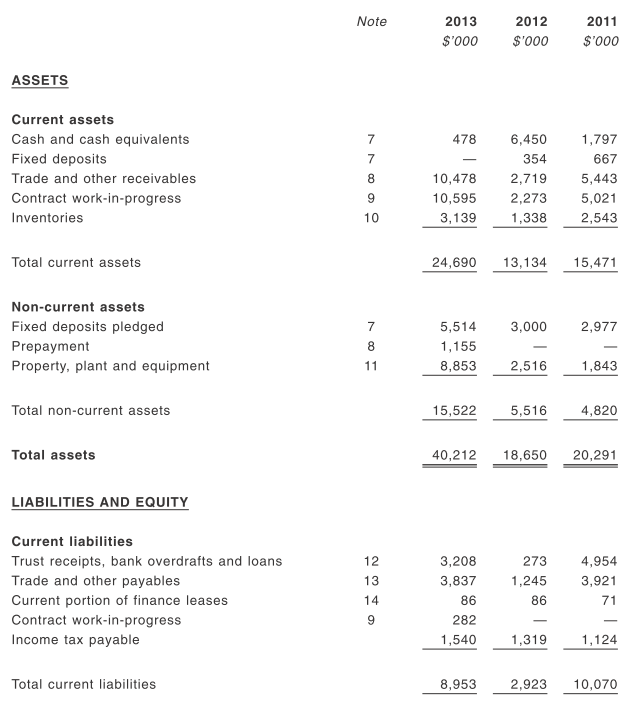
But based on their balance sheet, their current ratio is pretty healthy. But not all their current assets can be liquidised to pay off short term debts. Let's see the breakdown of their assets:


I think most of their operating cashflow in FY2013 is locked up in the form of contract work in progress and also other receivables. Once they convert that to cash, their operating cash flow should improve greatly. But in the meantime, I don't think they have issues with paying off any short term debts. Their receivables turnover for FY2011, FY2012 and FY2013 is 55, 16 and 10 days respectively. They said it's attributable to their stringent internal controls policy...okay, anyway, it seems really alright.


Dividends?

Any dividends? They are giving out at least 20% of their profit after tax as dividends in FY2014. Their order book for the firearm shooting ranges and tactical training mock ups is 19.7 million, which will be translated into revenue over the next one year (it's about there, if you add up the trade and other receivables and the contract work-in-progress for FY2013, you'll get about 20 million). As for maintenance services, they said that it'll be approximately 26.1 million, which will be translated over the next 1 to 19 years. I don't think you can add up 19.7 million to 26.1 million to give you 45.8 million in order book for FY2014. I'll just divide 26.1 million by 19, THEN add to the more or less confirmed 19.7 million, to give a estimated revenue of FY2014 as 21 million. That's also about the same revenue as that earned in FY2013.


Their net margin is about 40%, so that means their profit after tax in FY2014 is about 0.4 x 21 = 8.4 million. 20% of that will be distributed as dividends, so that's about 1.68 million, or 0.672 cts per share. The offer price is 31 cts, so that's going to give us a dividend yield of around 2.17% pa. Ah, you have to compare with ST engineering, which gives a yield of about 1.8% pa. This is after all a 'growth' company, so don't expect lofty yields of 5 to 6%. You should be looking at capital gains instead.


Competitive advantage

They listed down their local competitors, namely Cubic Range (listed in US), Meggitt Training systems (pte), Microcircuit systems (pte). The industry is such that a main contractor will bid successful for a project, then they will sub tender to others, so there's a fair amount of cooperation  between all the competitors. As for Cubic range, I read through their annual reports but it's not a fair comparison since they do a ton of other things as well. If you must know, their latest net margin is about 1.4% only, compared to Starburst's 30 to 40% net margin. 


There are of course other competitors internationally, since Starburst is also going overseas in middle east to bid for contracts.


Their main advantage over the others seems to be that they can fabricate and install bullet containment systems using their proprietary IP. I don't know how great that is, but from their net margins, it does appear to be quite unique. If only I knew about the margins of the other players...


The defense industry is likely to be very recession proof. I just don't see defense budget being cut...at best it'll be kept the same. And we're talking about big players - government or defense ministry - who command huge budgets. I think it's a good industry to be in with huge barriers of entry. You can't just apply to build such things because you need to have a good track record and have the relevant certification level, and Starburst's 15 years of experience in the industry should count for something.


Why are they doing it?


The two founders are going to hold 80% of the shares, with the remaining 20% of the shares (all 50 million of them) for the public. In the IPO, only 4% (a mere 2 million) of the public tranche is for retailers in the IPO. The remaining 48 million are up for placements. As usual, the controlling founders cannot sell their shares before the six months period is up. They must also hold at least 50% of their holdings for another six months. 


A big part of the proceeds (all 45% of it) is going to be for acquisition of leasehold land and buildings. The next big part (37%) is for general working purposes. I just don't know why they want to IPO it. Perhaps the two founders want to take back their capital and liquidise their holdings (don't they all?)


Worth getting?


I think this is fairly valued, and certainly not a sucker's deal. But the problem is getting enough of it to matter during the IPO. In the IPO, it's likely to be very hot, given the low 4% available for us mere mortals to bid. With 20% of available shares available for trading in the first 6 months, I think this is going to be those illiquid counters with huge movements. I'm going to take a second look once it's properly listed and all. Closing is on 8th July 12 noon. Trading will start next Thurs, 10th July.

Monday, June 30, 2014

My salted fish had turned over

First of all, sorry for the long hiatus. This had been a crazy June holiday, so all my free time is sucked up into never ending work. I'm very glad that June holidays is over, to the dismay of all school teachers in Singapore, lol!


Recently, I noticed that one of my salted fish had turned over (咸鱼翻身). Yup, you heard me right - that's when a stock that you had bought long long ago, and had dismissed it and wrote it off because of some mistakes in judgement but nevertheless held on to it, and is now suddenly revived. This particular salted fish is very fragrant because it had been salted since April 2010. I had bought it at an all time high of 0.270 and subsequently averaged in at 0.240, giving me an average buy in price of 0.255.


Wow...why did I buy it then? It's based on some rumors that I had long forgotten. It didn't materialise, and thereafter the stock crashed and burned but I still had on to it after all these years. Reason? It's a good reminder for myself not to buy stocks with rumors. I'm glad I've not made the mistake then, so in a strange fashion, it's quite a good tuition fee paid.


The company had been paying dividends, so it helped to reduce the cost of bearing the stock. After collecting dividends every year, it amounted to around 11% of the capital sunk in, so it's not that bad. I initially thought of cutting losses, but since I do not require the capital locked up (it was a rather small amount), I just held on to it. More like a reminder to myself rather than an aversion to realise paper losses. I must say I'm quite relentless in cutting stocks.


So, what's the rumor that's propelling this unloved penny to a parabolic capitulation now? It had recently announced that it had made placements shares arrangement (at around 0.160+) with two big investors to dilute the total holdings to around 20%. If you ask me, that's a pretty huge investment in a 'okay' company. One of the two investor is none other than Sam Goi, better known as popiah king, who is quite an astute investor and businessman. I wonder why he got into this, and with such huge stakes in the company as well. Usually share placements are frowned upon since it leads to dilution of everything, including dividends. But the market had absorbed this seemingly bad news quite unexpectedly by capitulating upwards.


Yeah, but who cares...I get to exit and pass the buck to another better player lol

Friday, June 06, 2014

The holy trinity of returns, risk and liquidity

There's been much talk about the CPF rates being very low. About 2.5 to 4% depending on which account you're talking about. It's kind of hard to get higher returns than that while maintaining the same risk as that of a fixed deposit. What risk am I talking about here? It's the risk of capital losses. And I'm not just regurgitating this - I've actual experience in maintaining a retirement fund for my parents, so I know what I'm talking about here.


My parents are not risk takers. The riskiest kind of investment product that had in the past (without losing money) are endowment funds from some insurance companies. You put in a lump sum at the start and wait for the term to mature, then you take out a sum greater than the lump sum you put in at the beginning while still giving you assurance that if anything goes wrong with you, you'll still get paid when it matures - that's basically how endowment plan works. This tranche of money that my parents had, they initially wanted to put in a fixed deposit offering maybe 1.2 to 1.3%. I thought I can do better than that, and offered to give them a higher return and also offer them capital guarantee too but they have to tell me a few months in advance if they need the money back. In other words, they are buying a bond from me, with me as the party guaranteeing that amount invested with flexible maturity date.


The magical point of all portfolio - to balance returns, risk and liquidity. Can't have it all.


The portfolio consists of preference shares from banks and some high grade bonds with strong corporate (and government backing, so they say). No equities at all because given my parent's requirements (they really just want their initial capital to be safe and liquid). How's the projected returns? It is expected to give around 3.6%, with capital losses incorporated (Most of the pref shares and bonds are bought above par from the secondary market at SGX, so when it's recalled back, I'll lose some capital). Can I push it above 3.6%? Yes, but something will have to go. The risk of capital losses increases with the portfolio yield. I can get some very high yield bond (e.g. from Olam) but if something happens, I'm the one bearing the losses because I'm the guarantor. Bo hua for me.


So yes, I totally get it that if CPF returns is 6 to 8% pa, then it can't be capital guaranteed. We have to balance portfolio returns, risk and also liquidity and you just can't have it all.


But not easy doesn't mean that CPF board should take the easy way out to beat inflation by raising the minimum sum. I think more options can be given to CPF holders to participate in the growth of their retirement funds. I would really be happy to see more growth in the bonds market offered to retail investors. If you're talking about normal bonds, you need at least a quarter of a million to participate - and how many people has that kind of money to spare? If SGX can break up the size of the offer into smaller chunks (in 1k lot, for example), it'll be a great move towards helping retail investors adjust their respective portfolio returns with the risk of capital loss.


More selfishly, I think it'll be good for people who don't have CPF (like me) to plan their retirement funds their own way.

Wednesday, June 04, 2014

So far so good

I've been using YNAB, a software that allows me to track expenses and all my cashflow in different accounts with great precision and accuracy, since Aug 2013. Almost a year now. It works very good for me because there's so many times that I've missed out on something and I didn't know about it until the end of the month when I did my month-end accounting and found out that things don't add up. I'm very sure I would have missed these errors if I persisted in using my spreadsheet way of tracking expenses. I'll still highly recommend it to anyone who is serious about budgeting and tracking expenses. Don't buy it now though...wait for a great offer to come (at Steam, that online platform to get games), which is a matter of when and not if.


Thought I'll do a half year update how my savings percentage is like, given the new found accuracy. In the past, my spending is relatively low. I'm not truly independent yet and a lot of expenses are paid for by my parents. Though I gave them allowance to offset some of this, I'm quite sure it's not enough. Why? I don't have to pay for rental (for a room). I don't have to pay for my own breakfast and dinner. If there's a problem with some household items, I'm not the one paying. When the toiletries are almost finished, it'll magically refill and appear. In short, a lot of expenses are paid for by others. Hence, it's hardly a miracle to have my savings percentage (relative to income, of course) at 70 to 80%. Of course, I always know it's not going to be realistic going forward.


After a few financial bombs that nearly wiped out all my savings, I got myself married, bought a resale flat, paying for a pre-owned car and started paying for things I never had to pay for in the past. Nobody is paying for me now, as it should be. Everything in, my year to date savings percentage hovers at 47%. (If you're not self employed like me, don't compare - I don't contribute to cpf. So, if you include your CPF contribution as well as your employer's contribution, in addition to your own savings from your take home pay, you'll probably beat me or even out.) This statistic is not going to be useful until I finished year 2014 and tabulated everything, because there is just too much variability in my income stream and also my expenditure patterns. There's some big ticket items in the second half of year 2014 that occurs annually (like insurance premium, road tax etc) so it might lower down my savings percentage. On the other hand, my peak season occurring around Aug to Oct might boost my income too. 


Going forward, I'll try to keep my savings percentage at around 50%. It can be higher but not lower. I already shared my monthly expenses - everything in, it's about 3.5k per month. Hence, it's very clear to me that my income better be more than 7k to have that kind of savings percentage. In fact, during my peak months, it better be much more than 7k so that it can even out those drier months. Life's a bitch when your pay resets (though not necessarily to zero) every year and you have to work hard to reach the same pay as before, and work even harder if you want to earn more than the year before. No complains here - I chose this myself.


My savings target of 30 to 40k seems right on track. Savings percentage is a tad lower than projected, but still alright. Will have to see it again at the end of year 2014. So far so good.

Saturday, May 17, 2014

The Amateur and the Pros

This is a post inspired by our Man of Leisure here.


If you've heard a amateur and a pro playing from the same music score, you'll find that there's a difference. Sure, the amateur can hit every note, even on time, but there's a certain degree of interpretation which defines the amateur from the pros. I don't profess that I'm a good musician (I'm not, I don't even play the piano nor how to read scores), but you'll find that you can play around with 3 things:


1. Notes (C, D, F# etc)

2. Volume (how hard you press the key)

3. Time (fast, slow, timing between notes)


Take some time and listen to the two youtube clips below and listen for yourself. One is from Synthesia and the other is from a pianist, Mira Lee, that I discovered on youtube like a day ago.


Synthesia music: Technically sound, but musically emotionless


                                   By Miri Lee: Can you feel that the music is different?


In learning any instrument, you first learn to play the score according to the beats. You don't miss a beat, you just follow exactly as read from the score. Once you know how to play a song mechanically after playing many many times, you earn the right to 'feel' the music. You play certain groups of notes faster (to build momentum) or you play certain notes louder (to build intensity), or certain notes softer and slower (to build suspense). A pro is someone who interprets these nuances and tweaks an otherwise mechanical score into something that has 'feelings'. An amateur? He just plays the notes according to the score, each note with the same volume with each abberation needing to be corrected.


I don't think anyone compared trading with playing music. Well, now you do. Trading is not much different. You have price, volume and time. Amateur might just use the same indicator mechanically. If it's a little different from the perfect signal, you don't trade. You haven't earn the right to have 'feelings' yet. But once you're a pro, you notice the nuances in the volume or the velocity of the price movement. Sometimes, you feel the market. It's hard to describe to someone how come you know certain things might happen (even if you do try to explain, you don't really think of it rationally like that at that moment of recognition). 


Can we apply the same concept to public speaking? Let's see:

1. Words and pitch

2. Volume

3. Time


Every one can read a script, but not everyone can speak like a radio DJ, even if the script is written by one. You just can't pull it off like that. If you listen to the pros speaking, you'll realise that they speak with certain stress on different words of a sentence. They vary their voice too, sometimes louder, sometimes softer. They can also speak faster or slower to create certain effects. What do an amateur do? They just read off a script.


An amateur is so focused on the magic indicator to use on a chart, where to get the score of the song they want to play and the professionally prepared script for the speech they are giving, while the pros are busy playing, feeling and trying out things. Worlds separate them apart.


Is there such a thing as an amateur or a pro on the road to financial freedom? I'm not talking about those who had already reached their goals, but talking about those still on their way. Maybe there is. Just listen to the music from the same musical score that we all play on our piano ;)

Wednesday, May 07, 2014

Comfort is the place where dreams die

I love Greek mythology. So in the past, hence it is now. There are many many parallels that you can draw from them. Some serve as warnings and some as inspiration. This one that I'm sharing is quite a well-read one. This is the specific part about Homer's Odyssey.


Odysseus, after losing his ship and his entire army, drifted in the open sea for days until eventually rescued by Calypso in an island called Ogygia. There, Odysseus spent 7 years living a life of comfort and peace, with food and lodging all provided for by Calypso. Now, Calypso isn't an ordinary mortal; she is the daughter of the titan Atlas, which makes her a goddess in her own right. She offered to make Odysseus an immortal and grant him the gift of eternal youth if he stays on the island forever with her.


That is not to be. Odysseus wanted to go back to Ithaca to reunite with his wife Penelope and that is his life's goal. He is not to be swayed from his goals. But he did took 7 yrs to muster up all his courage and conviction (also with the 'persuasion' of Zeus's messenger, Hermes), to leave the safety and comfort of the island of Ogygia to brave the open seas and god knows what may come in his journey back to Ithaca.


That is Greek mythology. But a lot of these mythology are as relevant in life today as they are in the past. Are you like Odysseus, drifting in the sea of the unemployed and eventually rescued by your current employer? Are you also spending long years of relative comfort and peace in your job - boring mediocrity yes, but it does pay the bills doesn't it? Who is going to send Hermes to rescue you from your rescuer, so that you can go on and brave the open seas again in order to reach your life's goal? The Hermes today usually comes in the form of a life changing event - perhaps a close shave with Death, perhaps a recovery from a life threatening illness or maybe a conversation with an inspiring person in a strange land. They can advice or counsel you, but like Odysseus, you will still need to act on your own.


Think about whether your current life is aligned with your values. If not, do small acts to move towards somewhere that is more aligned with your values because that is the secret to being happy and being satisfied with life. If Odysseus can take 7 years to leave a comfortable position to brave the world again, so can you. He is a hero because of his choices and in spite of his circumstance. Always push your limits and move towards the relatively uncomfortable place, because that's where maximum growth is to be found.


If you stay too long in comfort, who knows, maybe that's the place where dreams die.


Tuesday, April 29, 2014

Invest in yourself first before investing in stocks

I'm not in favor of young people getting into investments in general. It's so prevalent now that it's almost fashionable to say that you're into stocks when you're at a young age. What business do people who are still studying have in the stock market? None, in my opinion. They should focus on what they should be doing, which is studying. To me, there's a time for everything. I'm quite sure I'll get flamed for this post, haha! This is not what most people would like to hear. What?! It's bull market now and you ask me not to invest?!


For most people, the bulk of the capital to even begin investing comes from paid work. If you don't even have a proper salary yet, you shouldn't even begin investing. Focus on getting a proper salary first. If your salary isn't high, then invest in yourself and get yourself to the next banding of pay scale. If your salary is low, no matter how much you scrimp and save, you're always on the 1st gear and can't really accelerate your path towards financial freedom. Saving 100% of $10 is not going to beat saving 10% of $1000, so your limiting factor to reaching financial freedom is not your investment power but your salary. You'll find that spending time and effort to increase your base salary will work more wonders and than relying on investments,unless you're exceptional. But everyone thinks they are exceptional and not average... I think it's much easier to increase your salary by $100 per month than to increase your passive income by $100 per month.


After you raised your base salary to as high as it can get, then look towards saving a greater part of your salary. This first tranche of money is going to work hard to bring in future streams of money, so make sure that you can save. If you can't save a significant portion of your salary, then maybe you should concentrate on improving yours savings percentage first before you think about investments. Get the basics right and build up the base for your investments to work. Also work on reducing your expenses. Increasing your savings is really just one simple equation : increase your income and/or reduce your expenses. By increasing both your income and reducing your expenses, you will be able to save exponentially.


Once you've done all this and set aside some money for emergency funds, bought some insurance and budget aside some cash for near future spending like marriage, housing and renovation, then we can start to talk about investing. In summary, before you start investing, maybe you should invest in yourself and work hard to see if you can increase your salary first. That is more likely to be safer and surer than any investment you make in the stock market.

Friday, April 25, 2014

Re-framing the savings problem

Sometimes, to convince people, you have to re-frame the problem to fit into domains that motivate that person rather than motivate you. I saw a lot of bloggers posting ways to save money, which is all well and good as an individual, but shouldn't work too well if they are a couple. I know that as a fact because months can be spent before I buy a single article of clothing, but for my wife, money can be spent on a variety of things before the month is up. It's just different motivation system. I feel motivated spending on savings, but others might be more motivated spending on things or things that promote relationship building, like an afternoon tea in a hotel with a group of friends, or shopping trips with her friends etc.


Nothing wrong with that. It's only something wrong when you try to convince the other party that they should save money in ways that don't really motivate them. Financial bloggers (some, anyway) are really one kind of weirdos who don't mind whipping out their hand phones after every transaction to jot down their expenses and finding joy tabulating their spreadsheet every month end. But not everybody strives to be like that, nor should they. And who is to say which way of living is the better one? Delayed gratification for the future or enjoying immediate rewards by sacrificing tomorrow?


Here's a few ways to re-frame some problems encountered by couples. It will appear unapologetically stereotypical, but that's because it's based on my subjective experience as a guy. Specifically, a weirdo financial blogger guy.


Toast set. in Singapore can range from anything between $2 to $6.


1. Boy wants to save money by insisting on toast sets in a kopitiam. Girl wants to try an atas breakset set in a restaurant that sells basically the same thing but easily cost ten times the normal kopitiam's price.

Instead of persuading by means of saving money, re-frame the problem by saying that it saves calories by sharing the atas breakfast set instead of ordering one each, essentially halving the price. This is a good compromise to satisfy both the girl's need to spend money on relationship building activity, as well as the boy's need to save up.


2. Girl switches the air con, printer, fan and the lights on, even when not around. Boy tries to tell the girl not to do so because it wastes money and jacks up the electrical bills.

If saving money is not the motivation, then re-frame the problem to one of saving the earth. Appeal to the humanitarian and Captain planet's side of her. Imagine another tree is chopped down, another degree in temperature rose up, all because you didn't switch off the appliances when not in use.


Let our powers combine!


Well, you get the drift. Don't take this as a problem actually. These are, well, incidents, that makes life all the more interesting. It'll be quite dull if everyone thinks the same thing, isn't it?

Monday, April 21, 2014

MR loh!

I've recently finished the last leg of my national service, the much coveted MR (Mindef Reserve) parade. It has been a very long journey - 13 yrs to be exact - since I was enlisted as a recruit when I was just 18. Some of the people whom I've met when I was 18 was still with me when I went MR. Frightening thought, isn't it? How many 18 yrs do you have? I knew these people for half of my life! What's the feeling of MR? Is it like achieving financial independence or sending the last cheque to HDB because you're finally done with your housing loans?


It's a mix of feelings, actually. There's a tinge of sadness because I don't really mind reservist, especially when you get to enjoy a different pace of life. There's a certain simplicity in army life that I quite like, though I would never sign on as a career soldier because I don't think I'm suitable. There's also a feeling of accomplishment that I've finished this portion of life as a Singaporean male. This is something that not all the people can get to live through. I know how some people hated all things army, but it's still a sort of experience, isn't it? I'm glad I got to experience army life as a Singaporean male.


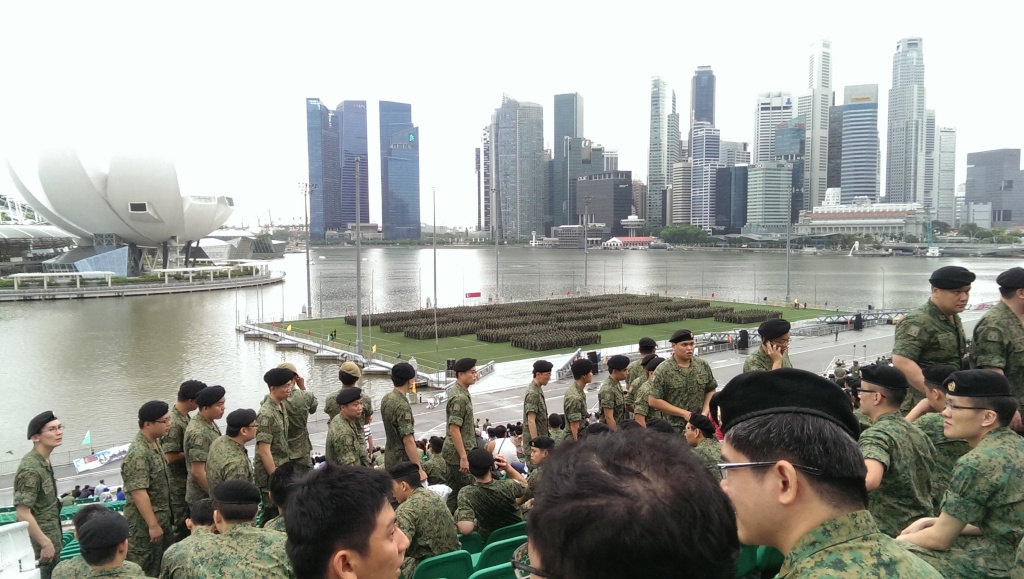
My unit is special - MR parade at marina floating platform


There's a few things that I'm grateful for in my 13 yrs of service to the nation:


1. Due to some changes in my unit that I'm posted to, I got to experience different sort of management under different commanding officers. I've been though one that is very pro micromanagement and information only flows one direction - from top to down. This is the unit that I've been with since NSF (national service full time) days and I don't really like them. Very rigid. Disciplined? Yes, but only when we need to show it when there are people around. I had a feeling that I always need to pretend that I'm busy so that I won't be 'arrowed' to do some nonsense work because I've finished my work faster than the rest.


Thankfully a small group of my friends got posted out when the former unit was disbanded. The management of this new unit is more hands off, preferring to let individual small groups take over command, while they follow a general orders from higher ups. Is it disciplined? Less so, but there's a great advantage to empowering people from bottoms up. The people in this unit is much more motivated. You see people volunteering to do shit jobs so that the majority can move on in their program schedule. You see people doing extra and giving feedback so that the unit can improve in future events. You even get unit pride so that you don't 'lose face' when doing unit's capability assessment test. Basically, I got a culture shock when I went in because nowhere in my army life had I seen such camaraderie and esprit de corp. This unit went on to get the best NS unit ever in Armour formation, and I'm proud to say that I'm one of their members.


There's life lessons to be learnt from this two opposing views from two different management teams, don't you think?


2. I'm extremely thankful that I have a group of friends that I've known for 18 yrs. When you knew someone that long, you no longer need any pretense. There's no need to talk about the weather and other trivial stuff because these kind of small talk had long gone stale in the first few years of knowing them. These are the people that I've gone through thick and thin with, both in terms of their waistline and also the kind of challenges faced when in service. You knew them so well that you know what they are going to do in the morning when they wake up (brush teeth first or change uniform first?), and who are the ones that will snore and the ones you can always count on for some chocolates or biscuits when you're outfield during exercise. They are perhaps the only group of people who have seen me in various state of undress. If I've not known them for 18 yrs, it would have been creepy. Very creepy.


They are the group of people that you would fight for. Never mind the lofty ideals of serving the nation - that's just pure propaganda. When you're deep in shit, you don't think about serving the nation. You think about not letting your buddies down.


It's great to know these guys.


3. I'm glad that I've been through NS. It's really an eye opening experience that I wish all people can get to experience. But you need to keep an open mind, otherwise everything that doesn't fit your 'normal' experiences will make you unhappy. Angry, even. My philosophy in life is to get as much experience as possible, and not necessarily the good ones only. Just as you need rain and sunshine to make a rainbow, you also need good and bad experience to enjoy life's rainbows. If you go through life like that, then everything is like an achievement waiting to be unlocked in the game of life.


Fired a real bullet from a real rifle - Achievement UNLOCKED.
Thrown a hand grenade without killing yourself - Achievement UNLOCKED.
Not having a proper shower for 14 days -Achievement UNLOCKED.
Shitted outfield? - LOCKED


It just adds on to the variety of experience that life offers. And no matter how much I complain when I'm actually in it, I'll miss those pesky mosquitoes in the jungle and peeing in the bushes, and eating combat rations. These are the things that you will remember in your life, because it's so different from routine.


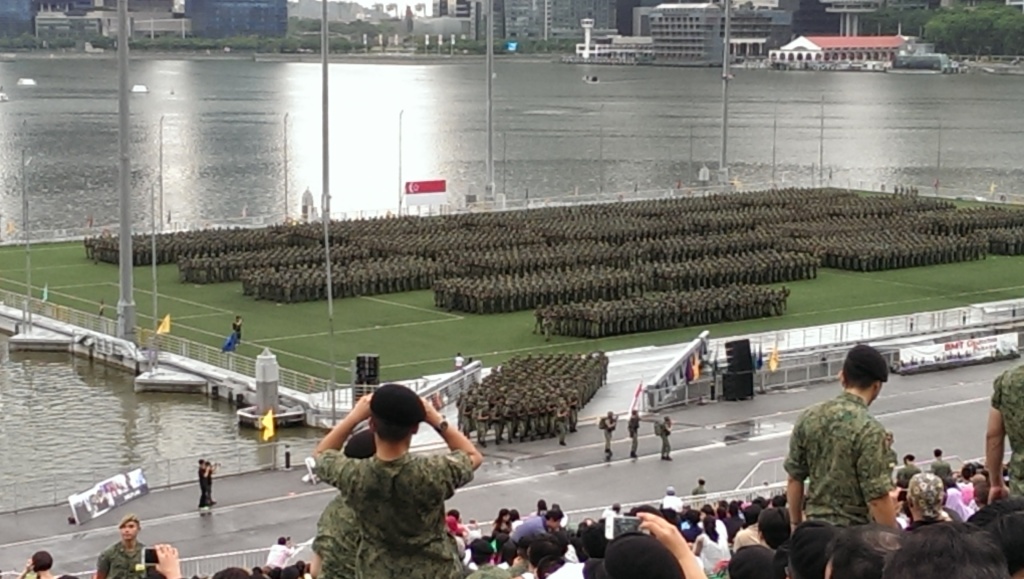
The BMT recruits are marching out. We've finished out portion and are just watching the parade as a spectator. Kind of strange because this is the first I've watched it as a spectator. Usually just a participant marching.


As a great round up to the whole NSF to NS to MR experience, I've to participate in a big scale kind of MR parade where BMT (basic military training) newbie recruits are graduating to their next phase in their army life while older soldiers like us are graduating to a pure civilian life outside. Passing the honorable duty of defending the nation from one generation to another.


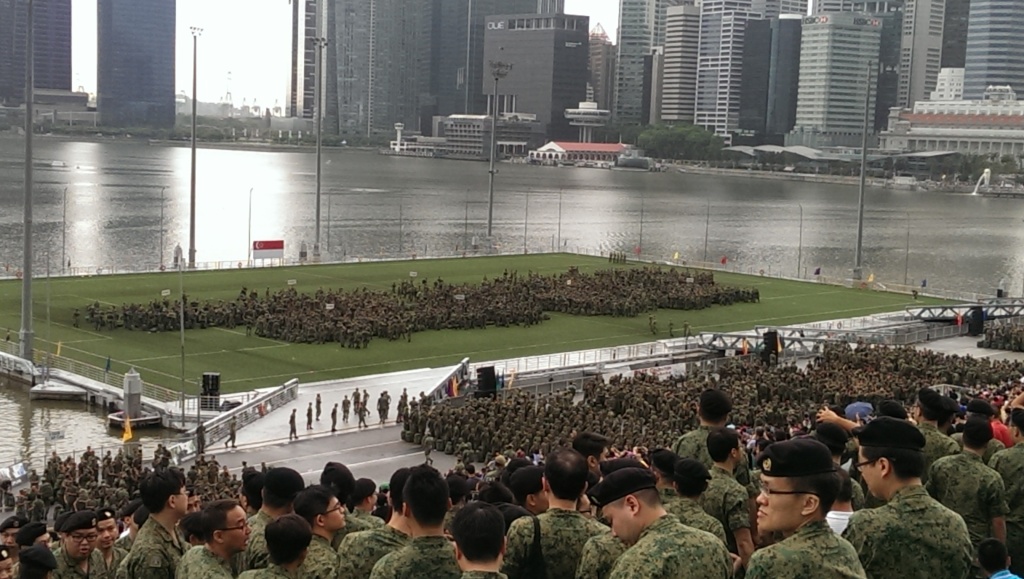
BMT recruits a celebrating their Passing Out Parade (POP). 12 more years to go, newbies.


Last parade of my life carrying a rifle, wearing skeleton battle order (SBO) and a beret and it had to rain. Heavily. Oh well...just take it and suck it up like a soldier.

Wednesday, April 02, 2014

How to party a chaotic good character with a lawfully neutral one?

I read an interesting article from wall street journal by Charles Murray here. In his article, he wrote that punctuality, orderliness and thriftiness are the top three personal habits that may make or break your relationship with your other half. I totally agree. Usually these 3 things are the ones that me and my wife would argue about when we first started our journey together.


We're like polar opposites, so maybe that's why we are attracted to each other. There's something magical about being with someone who is quite opposite from you - all of us will end up having our horizons and experience expanded, if you can tolerate the initial upheaval of your 'system'.


In terms of punctuality, I'm the one who lives by the clock, while she's the one who don't keep time. If we have an appointment at 10am, I'll be ready at 9am, while she's just getting ready to be 'ready' at 9am. This causes much friction while we're dating because I seem to be always waiting for her. But after a long time, I think we're used to each other's sense of time. For me, time is absolute and immovable, while for her, time can be stretched. She has come to realise the value of being prepared ahead of time because of several experiences where she is almost late for some important functions. For me, I've learned to take it easy because even if I'm early, most of the time, the other party will be late anyway. No real harm is done.


Orderliness: In short, I'm the tidy one and she's the messy one. Every day, we'll be fighting a battle of order against chaos. She'll take out stuff from the drawers and leave it lying around, while I'll be busy keeping up to put it back in. It's quite comical and hilarious sometimes. I get energy from having things in a orderly  manner; she don't. After I explained to her, she compromised by keeping certain areas tidy while I keep my eyes closed on other areas. That works very well for us.


Thriftiness: I'm the thrifty, misery one and she's the spender, generous one. She can complain about me being tight about money but when it comes to making financial decisions, I'm the one with all the facts and data at hand and will guide or take her through. I can complain about her spending a lot of money but when it comes to giving, or charity, or helping others she'll take the lead and show me how to be hospitable. I think I can certainly learn a lot from her, just as she can from me.


Being with your polar opposite doesn't always turn out in a good way. Some marriages are broken because of irreconcilable differences. I can imagine how some people cannot embrace diversity and always insists that they are right. If that's the case, then finding someone closer to yourself might be easier to handle in terms of relationship issues. My alignment is lawfully neutral while hers is chaotic good. Not the perfect match alignment wise, but very very versatile in terms of party mix. I think because we mix around so often, I'm slowly changing to chaotic neutral while she's changing to lawfully good. Not a major change but certainly perceptible.


I think the key to a good party combination, regardless of alignment or personal habits, is to be empathetic. If you can put yourself in the shoes of others, you can be with (almost) anyone. Compromising doesn't mean that you're wrong, it just means that you value the relationship more than who's right and who's wrong.

Monday, March 31, 2014

What's good about owning a car?

I had a car for about 2 years now and I dare say it's one of the best things I've bought. This is in sharp contrast to other financial bloggers, who are mostly too quick to dismiss car expenditure as something frivolous and definitely under the category of "wants" and not "needs". I thought I should share what's so good about getting a car in Singapore, rather than just focusing on the dollars and cents, which is pretty much anyone who frowns upon owning a car will say.


Firstly, the bad stuff. Everyone knows that to own a car in Singapore, you need the ultra expensive COE, which entitles you to own a car for 10 years at a cost of about 70k these days, and that's not including the cost of the car. Definitely not cheap. The running cost of my car per month includes the following:


1. Season parking (about $70)
2. Parking at other places ($50)
3. Fuel ($230)
4. Insurance ($90)
5. Maintenance (about $60)

Total: $500 thereabout

So the running cost is about $500. I haven't added in the cost of getting the car yet. I don't think I want to spend anything more than 40k on a car, inclusive of COE. So that means I'm effectively priced out of buying a new car. I went to the second hand car market and got a car for 32k, and that car can still last me for 4.8 yrs before I need to scrap or renew my COE. I paid half of it in down payment and borrowed the rest, so effectively my total cost is about $34k. This is way within my budget, and I really think it's affordable for people who wants to get a car.


Total cost: $500 + $360 (installment for car loan) = $860


Let's just bump it up to $1k per month. I chose to pay 50% and borrow the rest, way before it's mandatory to do so. But think if you're not buying any flashy cars, getting 4 wheels that allows you to move from one place to another should cost around $1.2k per month, everything in. Since I'm sharing the cost with my wife, I think I need about 2-3 more classes to offset this expense. That's pretty alright - essentially I work more so that I can work easier, and that doesn't include other fringe benefits that I'll mention right away.


What's the good thing about owning a car then? I can't speak for everyone, but owning a car is great on several levels for me. Now obviously not everyone works in the same kind of work as me, so the experience for different people differ.


These are the good things about owning a car:


1. You can go to several places in one single trip. Often times, it's impromptu and not planned.

True, you can get a cab, but it's just not the same. Sometimes, thinking about all the hassle of getting a cab to this place, then another trip to another place just make it so troublesome. I ended up just going to one single place to do all my entertainment, groceries and shopping. It just severely restricts your range of mobility because of the hassle of public transport. You can't say I'm spoiled because my family never owned a car before and I've been taking public transport for the bulk of my life, whereas I only had a car for only 2 years. The 2 years is enough to convince me that I should have gotten a car sooner, not later.


2. Saves you lots of energy

Commuting by public transport is tiring and drains my energy level. In a normal workday, it's possible for me to change bus/mrt at least 3 times. It's much more tiring if I've to stand and jostle with the crowd during peak hours. At the end of the day, I'm totally dead from all the energy spent. I don't know about you, but spending my time jostling with crowd drains my energy tremendously. Maybe I'm an introvert, that's why. With a car, I'm relative still full of energy even at the end of my most tiring workday. I don't always get to drive (mostly, my wife drove), so I can compare the difference between taking public transport and a car.


3. Saves me lots of time

Having a car can half my travel time, usually more. A trip from my home to a student's place can take 1 hour. The bulk of the time taken is spent just waiting for the bus/mrt to come. I'll say about 20 mins can be spent just waiting. A longer wait is necessary if you have to change buses/trains. The second biggest time waster in public transport commuting is all the stopping. You have to get to A to B, but in between there are multiple stops for passengers to alight and board. That takes up a lot of time, especially during peak hours. The huge time saver for travelling by car means that I can pack another lesson or two in a day. I think that alone can justify the running cost of the car. I didn't even include taking assignments that is further away from home, but pays a lot more, and is only possible with a car.


I get it that people want to retire early, reach financial freedom, then do whatever they want to do with their lives. Perhaps work life is so terrible that any moment spent working to earn a living is a thought so terrible to stomach. But instead of living a life after retirement, you can also live a life while working towards retirement. A car is just one example where the intangible benefits far outweighs the cost - it might be any other things. Heck, the only reason why I didn't commit to buying one earlier is because I was so put off by the 1.2k per month expense. To this day, I regretted not getting it earlier. I could have spent the same money and got either a better car or a car that I can drive far longer before renewal of COE/scrap.


Don't be blinded by numerical value. Financial bloggers are, by definition, more conservative than the general public. My advice to all financial bloggers is this: Just live life a little. Being a little more risk taking is still less risky than most people, so chillax.


Thursday, March 27, 2014

Which method of savings will you adopt?

I wonder how many people feel the same way that I did. Whenever I'm busy earning more money, I spend much less time outside shopping or eating at restaurants, so my income shot up and my spending shot down. This resulted in my savings rocketing skywards with a boost in earned income and a drop in expenditure. Conversely, when I'm more relaxed and have more free time because work winds down, I spend more despite my lack of income. So savings suffered a massive plunge.


Don't they warn that it never rains but pours? Well, I guess it's the same for my savings too. There's either huge savings, or there's very little of it. Maybe it's just an anomaly for those who are self-employed. I guess for salaried employees, there's very little variability in income. In fact, they have fixed pay but variable hours, so the busier they are, the less they earn on an hourly basis. Not good to be too busy, haha!


I know how to save more money. My way is not to save more by cutting down on expenditures. The reason is that I know that I'm not a spender. I know this is because I've been tracking my daily expenses for so many years. Cutting down on expenditure is a legit method of savings - I'm not denying that, but I dare say that it won't be the main driver in getting my savings up. I know that because I know myself by reviewing the records that I keep. The better way for me to grow my savings is to earn more money. This might not work too well for all, because there could be some people who would reward their hard work by spending more money. The net effect is just running harder on a treadmill - you run faster but you didn't move an inch forward.


I do know that if I spend more time earning money, I will have less time and inclination to spend money. It might not work for everyone, but it works for me. I think when you read about people saving more money through different ways, you got to figure out the best way that works for you. This will require you to know how you react in different situations. If you don't, then you got to experiment and give each method a try. You can't just take a general guideline and follow everything to the T, because you're ultimately not the person who came up with that guide. Whatever works for others might not work for you. And if that method is not suitable for you, you'll give up easily.


I know that my wife won't spend money that she can't see, so the best way for her to save up is to squirrel a part of her income away to some account that isn't easy to withdraw. If she can't see it, she won't spend it. There are also some people who live life dangerously - they save more if they are forced into situations they compels them to. For example, these type of people will buy a condo (regardless of whether they can afford it now), then go and find the money to upkeep it. It works for them tremendously, maybe because they can see why they are working and saving so hard for. If I do that, I'll probably lose sleep.


I'll leave you with this famous quote from Sun Tze- "Know your enemy, know yourself ; A hundred battles, a hundred victories". The biggest enemy towards building a healthy savings habit is yourself. Either from lack of self-knowledge or the inability to control yourself.


Tuesday, March 25, 2014

How to ride through the bicycle of life

I went for a course on learning how to ride a bicycle recently. The course last for 2 days and I just completed the course on Monday. It was great! The experience is well worth the money ($190 per person, including rental of bikes) and is further enhanced by the fact that I'm doing it together with my wife. Coincidentally, both of us didn't manage to learn how to ride a bicycle when we're younger. Kind of rare actually, considering that most people will learn how to ride one during their childhood, so what's the chances of finding a couple who both can't ride a bicycle? Practically zero, I bet.


Anyway, it's good to put yourself in the shoes of a humble newbie again. When we're good at something and we've been doing it again and again for a lot of times, we lost touch with something magical - the joy of doing something for the first time.


I learnt a few things that might be applicable to life in general.


Bullythebear learned how to cycle, and miraculously found how to
ride through the bicycle of life 


1. Learn how to move slower before you move faster

The coach removed all the paddles of the bicycle when we first started. The idea is to paddle by pushing your feet on the ground, so that you can control the bike and learn how to balance before you start paddling. It was such a simple strategy but I wondered why nobody told me that before. All the well meaning advice from people trying to teach me how to cycle is that I should paddle and move as fast as I can. But I never managed to put both feet on the paddles before the bicycle leaned way out of my control and I've to start again.

Trying to save a substantial amount? Try a smaller amount first. Trying to get a huge passive income? Try getting a smaller one first. A journey of a thousand miles begin with just one humble step.


2. Lean towards the side you're going to fall on

Again, another simple instruction that nobody had told me before. I had a preconceived idea that I must steer the bicycle away from the direction that my bicycle is leaning towards i.e. if the bicycle leans left, I must steer right. How wrong am I! I need to steer towards the direction that I'm falling so that my bicycle remains upright! Quite counter-intuitive, I must say.

Are you running away from your fears? Maybe you should face it head on instead.


3. To keep your balance, keep paddling

Once the basics of balancing without paddling is mastered, balancing and paddling at the same time becomes that bit easier. If you keep paddling, it'll be easier to maintain balance. How interesting! Another counter-intuitive action. You would have expected that by keeping still, you'll maintain stability, but who would know instinctively that by moving continuously, you'll also be able to keep your stability?


Next big project, learning how to ride a motorbike :)


Thursday, March 20, 2014

Allocated 2 excess rights units for AIMSAMPI rights exercise

This post wraps up the entire episode about the rights exercise for AIMSAMPI Reit.


Before the counter went XR, I bought 6 lots of aims mother shares at 1.385. I didn't buy any nil-paid rights off the market. I'm entitled to 1050 shares of rights units, and I've fully subscribed and applied for excess rights units too. Today on 20th March 2014, I checked my CDP account and saw that I've a total of 8 lots. The refund is not in yet though. I'll probably see the refund into my bank account on 21st March. This means that:


1) I've successfully converted my 1050 shares of rights units into ordinary units at 1.08 per unit

2) I'm also allocated 950 shares of rights units at 1.08 per unit, rounding up my odd lots to 2 full lots


This brings my total average cost per shares, excluding brokerage, to be $1.30875. If inclusive of brokerage, it'll be $1.31262. Not a big deal right, considering that today's closing is $1.310. Well, I wanted to get into this for some time, so the rights brings me a good opportunity to enter at a good time. All in all, if you want to get into a reits with rights issue, the strategy of buying enough shares to reap the maximum number of excess rights units granted to you, is still a valid and good strategy.


Not such a good deal for existing holders of aims, I'm afraid - it's better for new comers like me.

Wednesday, March 19, 2014

Need a seat? Just ask for it.

I was reading the news about Singapore being unkind and ungracious with interest. There's a lady reporter, being pregnant and feeling nauseous, wasn't offered a seat when she took the MRT. Even our top politicians are remarking on that.


I think that if you are in a restaurant, seated, and nobody comes up to you to take your orders, you should wave your hands wildly and call for attention. That will draw attention to yourself and people will come to service you. But why is it that when someone needs a seat on the MRT, then the person needing service have to wait for others to offer one to him/her? That's an interesting observation, no? I think we have to be a little proactive in what we want, rather than waiting for others to volunteer.


I think people everywhere generally practice polite inattention. You do that when a stranger enters a lift with you, so you look at everything except the person. You do that because you don't want to look like you are nosy and you just want to pretend that you're minding your own business, even if you're very curious. Well, I think the same thing happens in the MRT. When someone exhibits weird behaviour, like stripping naked, or sitting down on the floor, people generally practice polite inattention. You mind your own business.


If I'm needing a seat, I've to break this cultural barrier of polite inattention and the by-stander's effect (which means that in a crowd of strangers, everyone think everyone else will help, so in the end nobody helps). The best way to do is this:

Single out a person, tell him you're unwell and ask politely if it's okay for him/her to give up her seat for you. Giving a reason is important because that is generally more persuasive than just ordering people around. Being polite helps all the time. 


If you do that, and nobody helps you, then I will also conclude that Singapore are generally unkind and unhelpful. Until you try helping others to help yourself, I think it's a bit premature to say that others are unhelpful. There's a million reasons why others are not helping you, and one of the most compelling one is that they are giving you space to be 'weird' by practicing polite inattention. A celebrity might like Singapore precisely because nobody gives a hoot even if they know you're a celebrity. They might give a longer look at you, but generally leave you alone, unlike the paparazzi culture in other countries.


My stand is this: If you need help, and people volunteer to help you out, that's good and an ideal case. If you need help, and nobody volunteers, then you got to be proactive and seek the change that you want to see. Not everything needs a law in order to force certain good behaviour. Sometimes, all you need to do is just to ask.

Monday, March 17, 2014

Elderly folks getting bullish?

I noticed that quite a number of elderly folks wanted to put their money to better use. They realised over time, that the miserable interest offered by banks are not keeping up with the general rise in prices. This had been going on for some time after all. Perhaps they heard stories where their friends, or sons or daughters are making a good harvest from investing in the stock markets. Being in a bull market for 6 yrs is a pretty long time for people to think that the good times will last another 6 years. So, the elderly folks are naturally interested because everyone around them are making money but not themselves.


That is all well and good, but it's a little worrying. Usually the elderly folks are pretty conservative. Look at my own parents. They only put money into fixed deposits and perhaps the occasional savings plan offered by insurance companies (aka endowment plans). When I told them I can get better returns, they jumped immediately. They are still conservative in the sense that they don't want to lose any capital (actually who wants to lose any capital?), but they are also unconcerned that I'm investing in the stock markets to generate better returns to them. My in-laws? They had been asking their daughter whether it's good to invest in this or that because their colleagues or bosses had been making a good profit on certain counters. Generally, I find that the risk profile of the supposedly most conservative bunch of people are rising. If I'm a hound on the scent of greed in the market, I'm sure I can smell a whiff here and there now. Fear, the yin-yang twin of greed, is taking a holiday for now.


This doesn't mean that the market is going to crash soon. But I think everyone should be more cautious and on the look out for more signs of exuberance in the market. The good thing about experiencing through 2 bull markets is that you get to see things and how people react to them. All these forms subconscious cues, or a hunch, that perhaps the beginning of the end is near. I remembered reading news articles of young students, skipping school and wanting to become full time investors because they are earning such a good profit trading in the market. Who needs a degree and a job when they can earn a few thousands per day?


Just start squirreling excess income into your war chest. A market downturn is useless if you do not have the means to make use of it. So save up, do your usual things, and perhaps when an opportunity opens up in the future, we can all be thankful that we still have bullets to fire.


Tuesday, March 11, 2014

To remember, you have to suffer every now and then

People are funny; only when things that matters to them disappear, will they realise how much they lost.


Recently, I had a very bad bout of flu. It's so bad that I was quite immobilised for 2 days. On the 3rd and 4th day, I've no choice but to drag myself off bed and go to work. Thankfully, it's all over now and I'm fully recovered. But the illness did make me so happy that I'm healthy. Imagine suffering from some illness that isn't that readily recovered in 3-4 days. You probably can't imagine it because you have to go through it to know it. Even then, you have to go through it once every now and then to remember it. Such is the forgetfulness of humans.


The air quality is also getting worse. The haze comes early it seems. I just hope that it's not as bad as last year where all outdoor activities had to be stopped. Again, only when the air quality is bad would you realise how good it feels like to breath fresh sulfur free air.


I say it's good to suffer every now and then, if only that we can remember and empthasize with those who are suffering all the time. Knowing is not understanding; you must go through it to remember and hence to truly put yourself in the shoes of others.

Monday, March 10, 2014

Accepted, applied and paid for Rights Units!

Today I went to an ATM and exercised my rights units for AIMS AMP Capital Industrial Reits. I bought 6 lots, entitled to 1050 shares of rights units, applied 950 shares to round up my odd lots and also applied an additional amount for excess rights. All these rights entitled and applied are paid up in full (plus another $2 for the service fees) by the time I leave the ATM.


Again, the last date of exercising your rights units through ATM is 13th March 2014, 930pm. Don't miss that dateline. I've heard a horror story of someone who bought a lot of nil-paid rights off the market during the trading period, and forgot to exercise it. In the end, all the nil-paid rights expired worthless and nobody can save you. You can read this horror story here from Mr. Tan Kin Lian's blog post here.


At the end of the whole transaction, make sure you read the receipt issued. There are two important rows to check and double-check, and these are "Rights accepted" and "Excess Rts appl". Make sure that the "Rights accepted" is the exact number that you are entitled to, plus any nil-paid rights you bought off the market during the trading period. For example, if you have 6 lots like me, you'll be entitled to 1050 shares (6000*7/40 = 1050). If you didn't buy any nil paid rights off the market, then that's the amount you should have for "Rights accepted". If you also buy 3000 nil paid rights off market, then the total number of nil-paid rights you have is 4050 (1050 + 3000 = 4050). So make sure that your "Rights accepted" is 4050.


The "Excess Rts appl" refers to the excess rights that you applied. This one is less of a problem and wouldn't cause a catastrophic financial disaster if you press wrongly. Just press any amount that you want (provided you have the means to pay!). Minimally, you should apply enough shares to round off any odd lots. Anything above that is given lower priority, so it's up to your luck.


The timeline is as follows:

Expected date of issuance of rights units: 20th March 2014
Expected date for crediting of rights units in CDP and refund of money: 21st March 2014
Expected listing of rights units and trading of rights units as ordinary shares: 21st March 2014

Monday, March 03, 2014

Rule 4: Living on last month's income

Had a pleasant surprise this March.


When I opened my YNAB to do my monthly budgeting, I realised for the first time that I'm having a $0 for my budget from Mar instead of having a negative number. For those who don't have YNAB, you might not realise how fulfilling this situation is. Since they are using a system where every dollar has a job to do, having a non-negative starting budget value for the start of the month means that I've succeeded in using last month's pay to settle all the expenses of this month, without including any income stream for this current month. Since I've a variable income instead of a fixed salary, I really have to take a much longer time to get to this state. Exactly 7 months is how long it took to have a non-negative starting value for a new month.


Rule 4: Live on last month's income


This is a sort of gamification to make personal finance fun and interesting. By setting intermediate goals or achievements, similar to playing a game, you'll make it through the tougher months where you feel like giving up. For this case, if you're using YNAB, there's 4 big achievements or Quests to be done:


1. Give every dollar a job

Easily done really, just that I don't use a budgeting system in the past until I started using YNAB. I use the 'pay-yourself-first' system where every drop of income I have I'll transfer some to my savings first. Whatever is left is whatever I spend on. I changed because I see a point in budgeting. Budgeting can average out your expenses for all the months of the year because you break down one-off expenses (like annual insurance payment, planned travel etc) and spread it over 12 months. Easily to handle for those with tight cash-flow. Easier for me too since I've variable income.


2. Save for a rainy day

Not a problem for me because I've been saving way before using this software. Makes it easily to track everything though. You can even save for different things. Really reduce the possibility of doing mental accounting down to zero.


3. Roll with the punches

This is manageable for me - basically this means that you need to cut yourself some slack on months that you can't fit your budget. If you spend above your budget, then whatever excess is subtracted from next month's budget. Conversely, if you spend below, you get to spend more the following month. Great system, I must say.


4. Live on last month's income

Ah.. this really took me some time. To achieve this, you need a combination of saving, reducing expenses, increasing income and really proper budgeting. It's hard to appreciate this without the software really.


Still love this software after 7 months. For those who tried this, any feedbacks on how YNAB makes your life better? Care to share with me?