Tuesday, May 19, 2009

How much to save to retire

I was just doing some simple calculations to see how much I need to earn in my working life (assuming I have to retire at 55) in order to sustain myself only till the end of my life. I've a average monthly expenditure of around 2500, all inclusive.

So assuming I pass on at age 85,

$2500 x 12 x 54 = $1,620,000

I probably need this much money now in order to stop working yet be able to sustain my lifestyle till 85. This 1.6 million of course do not include family, or any other commitments that I incurred while I survive till 85...thus it's quite an underestimate.

Reality sucks, isn't it?

Assuming I maintain my expenses after I retire all the way till 85, I need to spend $900,000 (based on $2,500 per month expenses for 30 yrs). I only have 24 yrs to get this amount before age 55, the age I can retire. This means that I need to save $3,125 per month from now till age 55 in order to save up to that amount. That's hard saving only and it's hard saving that amount for that long period.

If I have an investing capital of $100,000 now, I figured that I need to get a returns of around 9.6% per year on average to multipy that capital to reach $900,000 in 24 yrs. That's assuming I didn't add in more capital to that initial capital outlay. Do you think it's do-able?

How can anyone not invest? It's not impossible to reach financial independence, but it'll be very hard if one has to do it by savings alone.

Thursday, May 14, 2009

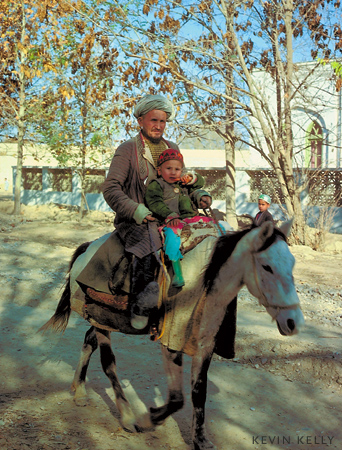
The father, the son and the donkey

KK shared with me this story in the cbox. I really thought it's a very important lesson to be learned from it. It is happening to us all the time. Since we learn different things from the same story, I'm not going to interpret but leave it open for readers to form their own thoughts about it.

----------------------------------

A Man and his son were once going with their Donkey to market. As they were walking along by its side a countryman passed them and said: "You fools, what is a Donkey for but to ride upon?"

So the Man put the Boy on the Donkey and they went on their way. But soon they passed a group of men, one of whom said: "See that lazy youngster, he lets his father walk while he rides."

So the Man ordered his Boy to get off, and got on himself. But they hadn't gone far when they passed two women, one of whom said to the other: "Shame on that lazy lout to let his poor little son trudge along."

Well, the Man didn't know what to do, but at last he took his Boy up before him on the Donkey. By this time they had come to the town, and the passers-by began to jeer and point at them. The Man stopped and asked what they were scoffing at. The men said: "Aren't you ashamed of yourself for overloading that poor donkey of yours and your hulking son?"


The Man and Boy got off and tried to think what to do. They thought and they thought, till at last they cut down a pole, tied the donkey's feet to it, and raised the pole and the donkey to their shoulders. They went along amid the laughter of all who met them till they came to Market Bridge, when the Donkey, getting one of his feet loose, kicked out and caused the Boy to drop his end of the pole. In the struggle the Donkey fell over the bridge, and his fore-feet being tied together he was drowned.

"That will teach you," said an old man who had followed them:

"Please all, and you will please none."

Friday, May 08, 2009

Wordle here wordle there

This is another wonderful piece of art form I found from PG's website. Indeed very fun - I spent a few hours playing with it just to see the different combination that comes out.

Here's a wordle of the books I've read so far this year. The bigger the fonts are, the more times it occurs in the titles of the books I've read :) Have fun trying, it's found here!


See? I've read a lot of books on millionaires and a lot of them have the words 'Buffet' and 'Richard' in them :)

Thursday, May 07, 2009

Top-down approach in investing

I usually adopt a bottom up approach towards investing, so it's good to do a top down approach too, just to see the broader picture. I read this little book series (yes, finally completed everyone of them!) called Bull Moves in Bear Markets by Peter Schiff and in it, there are a very investment themes to take note of. Basically the author is very bias towards the near term future of US, notably because of the high amount of debts that it is mired in and the unwillingness of FED to raise the interest rate to curb inflation, thus running the risk of hyperinflation.


Here's a few countries that might do very well in the future:


1. Australia - This is a country rich in natural resources, with lots of supplies of natural gas and metals. Being very close to China, who is very likely to consume huge amounts of metals and energy in the future to fuel its economic growth, Australia is thus likely to participate greatly in the commodities bull run mentioned by Jim Rogers and other such 'visionaries'. I think its close proximity to China makes it a good exporter of commodities to China at a cheaper price.


2. Canada - Stupid also mentioned about the loonies. It is the largest foreign supplier of energy, including oil, gas and uranium to US. Canada is resource rich with a lot of metals, agricultural commodities and energy. Again, another commodities play, with likely appreciation on its currency, like Australia.


3. Singapore - Yes, this little tiny dot is mentioned in the book as well, which I'm pleasantly surprised. For those cheapo neh neh, can go to bookstores to browse this book. It's on page 163. Singapore depends a lot on export, particularly in consumer electronics and IT products. Manufacturing is diversified into petroleum refining, chemicals, mech. engineering and biomedical sciences. I guess Singapore's advantage is its good relationships with China and US, so can probably use its status as a financial, hi-teh and medical tourism hub (the book said so, not me) to leverage itself into a nice cushy position. The other advantage I can think of is the stronger stable government.

Hey, you can complain all you like about the government, but we all have to concede defeat to its stability and the effects this can have on investors abroad. No strikes, tri-partite relationships with labour unions (do we have one?), low unemployment rate, highly educated labour force -- all this adds up I suppose.

There's a line which I snigger at: "Singapore is the third most popular place for Chinese companies to list their stocks, after Hong Kong and the United States." Oh true, that's why we get all the third-tier ass shares listed here.


Ok, I'm not going to list say more...here's the list of other countries that the author feels for: Norway, HK, Switzerland, New Zealand and Netherlands. We can analyse the countries and see that he is bullish on Asia (esp those leaning towards China), as well as those countries with lots of commodities.


Okay, enough from the book. Here's a few themes that I think are worthy to consider in the future:


1. Green technologies

There is this strong undercurrent of green movement happening around the world today. Carbon footprint seems to be a key concern too. I've a lot of young people telling me about saving the earth and so on. China might also be setting up their own green cars to compete with US. Might be the next technology to lift the world's stock market to another feverish bubble.


2. Commodities

Energy related commodities will continue to play a big part to power the world's economy. Hmm, unless someone managed to find a very environmentally friendly and abundant supply of fuel...looks like bubble creating material to me. There are reports saying the huge demand of metals that China will need in build its infrastructure, thus turning it from a net exporter to net importer. With the low interest rate environment, inflation could be a problem in the future, so countries with lots of commodities will be able to take in more foreign exchange gains if the commodity bull run is true, thus maintaining their currency from dropping.

Wednesday, May 06, 2009

Microsoft Live Writer review

After listening to what PG had mentioned with regards to my time saving article recently, I decided to adopt and download the free Microsoft Live writer. It's actually a very cool piece of software and I'm testing it right now as I type this article. In the past, I used to type my blog on Microsoft words then cut and paste onto the blogger site, but it seems that this cool piece of software can publish straight to blogger!

I can even see how it looks like in the actual colour settings, which is damn cool! If not, I can always switch to html or the normal 'words' format to edit as I wish. Very convenient indeed! I can even put in pictures from web or from my computer, which previously I can't from microsoft words.


The software is also quite idiot proof and I spend less than a few minutes trying to figure out which buttons is for what functions. It certainly makes my blogging experience more enriched. I think it's even more user-friendly than the blogger interface :)

Conclusion:

Definitely a must-use for me! Potential time-saver found!

Monday, May 04, 2009

Ways to save your time

As time gets more and more precious, I wondered how else I can do to squeeze more time. Everyone gets 24 hours a day, but some people wasted a good part of their time doing things that are not aligned to their goals or not pleasurable to themselves – in order words, their time got ‘robbed’ by others.

Here’s a few ways for me to squeeze more time to really do the things I want to do:


1. Blog my articles in Microsoft words first, then cut and paste it straight to blogger.

I’m currently doing that now because my internet connection was down, so I’m using the time now to type it out in the words form so that later I can just copy and paste it to post the article up. This is a great time saver because by blogging the articles when my thoughts are the most lucid and fluid, I can save a lot of time thinking about what and how to write the articles.


2. Give yourself 5 minutes to read through the snail mails and decide what to do with them straight away

I used to keep a pile of snail mails on my desk, waiting for the day when I’m finally free to sort them out. It takes a great deal of time just reading the mails again then following up the actions required. These days, I give myself 5 minutes to read through, decide and follow up the action immediately. These grant me two advantages – firstly, my desk is clutter free and secondly, I do not have to sit through the piles of mails to follow up the actions required. I either throw them straight away or file them up if needed. This ‘no-second-look’ philosophy must have saved me a few hours per month, which is substantial savings in the long run.

I think this rule applies to emails too. If I didn’t follow up my emails immediately, chances are that I would not do it anymore. So I make it a point to apply my ‘no-second-look’ philosophy to that too.


3. I always bring a book whenever I go

It never fails to amaze me how a well-planned schedule for a day can go horribly wrong. I might end up waiting a few hours for events to happen, and I dread having nothing to do while waiting. Thus, I always bring a book whenever I go in case I have to end up waiting for people longer than I should be. I also kicked the habit of sleeping on trains and use the time to read while standing/sitting. I can’t read on buses (it makes me dizzy), so I nap a while or just think about stuff.


4. Use of the SBS-Iris online before I go out

As I take buses most of the time, I detest waiting the long waiting time at bus-stops. Since last month, I’ve been using the SBS Iris website to determine the waiting time I need for my bus to arrive at the bus stop and plan my trip accordingly. This is such a time saver that I make it a point to check whenever I’m going out, if it happens that I’m taking a bus.

Use your time wisely. It’s the only resource that you have!

Tuesday, April 28, 2009

Make me an offer I can't refuse!

When we’re talking about investing, what are we actually looking for? The concept is actually very simple. We’re basically looking for a company that fulfills the following:

A company that earns the most stable and highest earnings over the longest period of time, selling at a cheap price.

(You can replace ‘earnings’ by ‘dividends’ for those who are looking more towards income)

While the concept is easy, the execution is certainly not. For example, what is meant by cheap? Am I talking about the cheapness of the price with reference to the past prices, or am I talking about price with reference to intrinsic value? Talking about intrinsic value, how do I calculate it? Based on PE, discounted dividends, discounted cashflow? What about the discount rate and the period of discounting?

It opens up a can of worms just by analyzing the simple statement above. It’s the same when analyzing a company too – you thought it is a simple affair till you read more.

I think I need to do valuation of the stocks that I want to own, and the price that would make them attractive. It’s been a long time since I started doing so. So, everyday, I’ll just go the market and see if it throws up some real good bargains at me. Make me an offer I can’t refuse!

Wednesday, April 22, 2009

What I learnt from Mafia wars

After playing the facebook application - Mafia Wars - for some period of time, I've come to realise a few truths in life. You can really learn a lot of serious stuff in games, if you played it seriously enough. I'm so serious to even put in a spreadsheet the various yields one will get if one invests in different kinds of property.


Here are the truths in life that I realised by playing the game:

1. You need friends around you. Having many friends is better than having no friends. Having a few good quality friends is better than having many poor quality friends.

When playing the game initially, I only had less than 5 friends. As a result, I was bullied tremendously. It got to a stage that I was so irritated that I went to a massive recruitment drive to increase my friends. Currently, I had 150+ friends. Guess what? No more random attacks from others, nobody dared to rob my properties and it became so much easier to attack/rob others. I also realised that as my many friends grew in levels, it's even harder for others to attack me. A few high level friends helps more than plenty of low level friends.


2. When the going gets tough, the tough not only gets going, the tough hits back.

I used to just silently absorb all the abuse from others as they attacked and robbed my properties, thinking that I should be nice to others. But I soon realised that the best defense is to attack others, especially those that think they can bully me. I would gather a few strong friends, rob their properties dry, attack them until they are dead again and again for a few days until they give up. In life, you need to show others that you have the capability to hit back very hard when the need arises so that others will not take you for a sucker. I have to be aggressive to protect myself.


3. It's important not to overstretch your cashflow.

When you are rich, it's easy to forget that for every things you buy, there is a hidden liability side. As you accumulate your assets, you also begin to accumulate your liabilities. Make sure you always have free cashflow and do not accumulate too many assets that drains your cash out. My current cash flow in per hour is $22 million, cash out per hour is $402k, so my net cashflow is still $22 million per hour. I think I'm as conservative in game as in real life.


4. Be aware of the consequence of your actions, it might come back to haunt you later.

As I was attacking and robbing those who attacked and robbed me earlier, I was wondering. Is it possible that the other party is also retaliating because I had earlier on attacked/robbed them? So it becomes a case where the victim becomes the aggressor and subequently became the victim, and goes on and on in a vicious cycle. In life, it might not be possible to see who is at fault. So one should just think about whether all the fighting is worth it.

I called a truce with someone after fighting him for around a week. He accepted, and is now part of my team.


5. When money is not a problem, a lot of calculations becomes unnecessary.

When I started, money is not enough, so I had to calculate yields for the property purchase to make every cent that comes in count. When I am earning 22 mil per hour (i.e. in one day, I'll get 530 mil - alas if only this is real money) in the game, there is no point to this anymore. I just buy the property or any other items that I like since it forms only a tiny fraction of my cashflow.

The rich thinks very differently from the not so rich, and they are moved by concerns different from others.


There are so many truths in life that you can discover, if you only open your eyes to them. Most are just in front of you yet are invisible to you. Hidden in plain sight.

Tuesday, April 21, 2009

China milk quarterly tabulation

I've some time at hand to crunch some numbers for China milk. I've always wanted to do that but never really got around to doing it. Here's the figures:


I didn't read through the whole annual report nor its business in details, so let's do it another time then. Here's a few thoughts:


1) Despite the s-share saga, there are some s-shares like China milk whose business are still very sound and the debts are not stacked sky high. A cursory look at the revenue and net profits shows that China milk is very much in business despite the tainted milk saga in China too. The business is doing well without the much debts too. Debt/equity ratio is pretty good and is much lower than that in FY07.


2) The cash and cash equivalent is growing bigger and bigger since 1Q07. China milk did not announced dividends but there are official announcement of China milk proposing to buy back part of their convertible bonds - the only long term debts in China milk's balance sheet. The details are quite beyond me, not very sure what they are talking about. But it's important to note that by doing so, they would have reduced their long term liabilities in their balance sheet (by how much, I'm not sure) and book a non-taxable accounting gain of US$654,600 or around RMB 4.5 mil. That is around 3-4% of the 3Q08 net profits.

There are of course questions regarding what is the use of this cash if the management did not distribute back as dividends to shareholders. I think besides buying back their bonds, they intend to get more dairy livestocks.


3) Is there a problems with China milk running into liquidity problems? Very unlikely. Their current ratio are off the charts, being so well bathed in cash. With their repurchase and subsequent cancellation of their convertible bonds, their liabilities will reduce further. We're talking about a very debt-free s-share over here.

Monday, April 20, 2009

Hongguo FY08 results analysis

Hongguo released their FY08 results quite some time ago, and it’s only now that I’ve the time and resolve to really sit through and pore over it in detail. Overall, it was quite a disappointing 4Q result – not terribly bad nor excellent, just so-so. It didn’t help that Hongguo did not declare dividends for FY08 too, presumably to conserve cash and stay liquid in this hard and trying times. I’ve been waiting a year for their dividends in vain.

Here are the quarterly results for Hongguo for the whole of FY08:


1) We can see that the gross margins of Hongguo’s business fell sharply over the quarters. After a sharp rise in 2Q, the 2H08 is just anaemic. There are two reasons for this.

Firstly, the price of the products sold had been reduced due to the promotional discounts granted under the Hongguo’s stock clearing activity, as well as other sales campaigns organized by departmental stores. The departmental stores had to do this so as to encourage more consumers to spend, and such activities had increased in the 4Q, resulting in the rather poor gross margins of 34.6% in the 4Q (compared to average 39.4% for the whole FY08).

Secondly, there is an increase in the cost incurred by Hongguo to support the sales campaigns organized by the departmental stores. Whether there is an increased in the cost of producing the products sold, I’m not too sure on that.

These two reasons exert a downward pressure on the profit margins relating to C.Banner product line and those under JUC. It remains to be seen if this is a chronic problem or a temporary one. C.Banner, Hongguo’s top selling product line, is still ranked no.3 in China in terms of market share.


2)Net margins dropped throughout the whole of FY08, resulting in a whole year net margins of only 12%, compared to the 14.9% net margins in FY07. The rise in Selling, distribution and administration expense (SDA) rose for every quarter. This is due to Hongguo setting up more retail outlets (addition of 125 new outlets for their in-house brand, C.Banner and E.Blan, as well as another 60 more Naturaliser outlets), resulting in higher cost and administration expense because of higher staff payroll.

Just counting the in-house brand outlets opened in FY08, there is an increase of 16.4% in the number of outlets in FY08 compared to FY07 (762 in FY07 and 887 in FY08), whereas there is a corresponding increase of 27.1% of SDA (175 mil RMB in FY07 and 223 mil RMB in FY08). To have a clearer picture, let’s take a look at the SDA/revenue increment. It increases marginally from 23.8% in FY07 to 25.3% in FY08. This means that while opening more outlets will increase the SDA, the corresponding revenues brought in by the new outlets sort of compensated for the increase in SDA.

However, more revenues do not necessary imply that more is added to the bottom line. With the management stating explicitly that they are going to add another 120 new outlets (100 for in-house brands, 20 for Naturalizer brand), I’m a little worried. I can expect the SDA to increase more in the next FY. As long as the additional outlets are opened without leveraging themselves too much (they did not borrow money to open new outlets at all) and keep inventory management, costs and cash flow tightly managed, I think all should go well.


3) Their liquidity ratios are all very well above the normal s-share companies, so I’m not worried at all. With current ratio well in excess of 3 times, and quick ratio above 1.5, I think Hongguo have a clean bill of balance sheet health. They are not highly leveraged at all, so that must have helped a lot especially now where credit lines are tight. Receivables dropped, even when revenues have increased, so no problems of Hongguo having a lot of theoretical earnings in income statement but no real money in cashflow statement. I did notice in the footnotes that the percentage of the receivables dragging over more than 1 yr had increased from around 8.7% in FY07 to around 12% in FY08. But the total amount we’re talking about is less than 1% of the total trade receivables, so I think it’s immaterial. Around 94% of the trade receivables in FY08 are not past due and not impaired, so it should translate into cash in due time.

In terms of cash flow, there are not problems as far as I can see. They are probably going to have better cash flow in the next FY because firstly, they skipped the dividends and secondly, they mentioned they are not going to expand their manufacturing facilities to boost their annual capacity since they still have excess capacity to handle it.


4) Looking forward, the management reiterated that their main focus is actually on the ladies footwear retail business in their business strategy. Currently, they are getting a higher percentage of their revenues from their contract manufacturing business. Hongguo intends to be less aggressive in their outlet expansion plan (though they are still going on with their plans to open another 100 in-house brand outlets and 20 Naturalizer outlets), which I think is prudent in case their liquidity dries up.

For the existing scale of operation, Hongguo stated that their current 6 production lines are sufficient, hence they do not need to expand further in their production facilities in the coming FY. They would instead focus on securing high margin orders to increase their profit margins. Big words, yes, but so far, the management had a track record of fulfilling what they had mentioned. I've full faith in them continuing to do so again. They have every incentive to do so, since in FY08, all the 3 founders had a total stake of direct/indirect interest amounting to 47%, compared to 46% in FY07.


5) I should be attending my first AGM on 30th April by Hongguo. They are trying to pass off some resolutions, notably the more interesting one would be the share purchase mandate. I don't mind them purchasing their own shares off the market, though at this time, I would rather they distribute it to shareholders in the form of dividends. I've no wish to invest more in ass-shares at the moment, so I would rather direct the cash from the dividends to other worthy pursuits.


6) Valuation valuation valuation…

Price at last close: $0.155
EPS: $0.061
PE ratio: 2.5x

NAV: $0.32
Current assets – total liabilities: $0.25

I’m not even going to suggest that Hongguo is a good buy now. But if you’re dying to get some ass-shares in SGX, why not consider the better ones? You’ll save yourself countless sleepless nights. Just ask those who invested in Ferrochina, beauty china, china print & dye etc.

Even considering graham’s strict current assets – total liabilities, the current price is at around 40% off it. If Hongguo survived this and does not go belly up, how wrong can you go with 2.5x PE and price way below any form of valuation? Time will tell if this is a good investment.

Thursday, April 16, 2009

Bulls climb a wall of worry

Have you got this feeling that you've missed out on the stock market? If you've been watching the markets, it seems that no bad news can derail STI from marching upwards these days. Forget about the general economy and the languishing GDP forecast by our government - the stock market has a mind of its own and will move up regardless of the fundamental economic situation.

A few signs are worrying:

1. I've noticed that the top volume of SGX are occupied by the likes of small caps, specifically the ultra pennies as I call them. Once again, ultra cheap counters like the 0.005 digiland reaches the top position in volume transaction. Hey, did I have a deja vu that such things had happened before? I remembered fondly the good old days of the 2006/2007 period where such small caps are punted.

2. Some of the counters are climbing up with lesser volume, perhaps reflecting the same way that STI index is climbing up too. Look at ocbc's chart:


Did you see the rise in price without the corresponding rise in volume? Volume divergence is the name of the game.


The signs are even clearer when you look at UOB's chart. Several volume indicators are diverging from the upward trend in price.

So, if you think you've missed the boat, think again. If you're a keen reader of history, you'll learn that humans never learn from their past mistakes. What had happened in the past will happen again, perhaps in another form. Don't feel missed out...look out for opportunities again and know what to do when it happens again.

If all else fails, you can always feel 'motivated' by this:


Thursday, April 09, 2009

Fashion whims in insurance

Did you realise that financial/insurance products suffer from fashion whims too?

During the good old bull times, we have products offered by companies touting good returns projected way into the future (I heard from a friend, the returns projected are at 10% or more). It's no surprise then that the returns are much less than projected - it's just not sustainable. So what's fashionable now?

If you ever had people cold-calling you regarding their newest product, or if you've ever been waylaid by people on your way to a shopping mall, you'll have realised that the latest fashion whim in financial products are endowment polices. These are called a variety of names but all of them fulfill the same function - save a certain amount of money per month for a period of years mixed in with a bit of insurance coverage, essentially a sort of savings plan.

Hey, don't get me wrong. I'm not saying that endowment plans are rubbish - they are not. I'm just saying that they are not suitable for everyone, especially those who have no proper life plans, CI (critical illness) and H&S (hospitalisation plans). You know, when you have only one product to sell, everyone seems to need the product you are selling. Just like when you have a hammer in your hands, every problem seems like a nail to you.


I noticed that banks are getting a bit more aggressive towards selling insurance policies to its customers. They are touting H&S plans and other insurance plans too. For those who are unsuspecting and who bought it, may I ask a few questions to you:


1. Who is going to service you when you have claims?

2. If you have queries, who are you going to call for help?

3. Who's going to do a yearly review with you since you last bought it as your circumstances must have changed?


Not sure about you, but I prefer to have some face whom I can talk to and hold accountable for. Of course, that person might run road too, but there'll always be another one to take over your case.

Another fashionable whims in insurance I detected recently is this early payout upon diagnosis of CI. Suddenly the brochures are highlighting this clause, and there are new products introduced with the selling point as this. Hey, you know what, the whole industry is filled with incompetent people inculcating the incomprehensible into the indifferent...it's going to be an immeasurable effort.

If you ask this layperson who knows nuts about insurance, I'll say go for the big picture. If you're my age, single but not available and with no child, you'll want to ensure that you have at least a proper life coverage for CI and death, together with the all important H&S plans. Cover these basic needs first, then we talk about other add on like personal accident plan, hospital benefit and disability income. Settle that insurance part, then we proceed on to talk about investments. Exactly in that order.

Tuesday, April 07, 2009

STI - self reference

Self reference only.

There's still no signals to get into STI. Have to wait for a good point of entry.


I see support level at 177X level, sitting right at the ema100d level. After that will be 170X level. I read this website often, it gives a good analysis of the STI weekly movement. Good reference material: http://www.him.com.sg/

I want to catch the big movement, not the small little ones, hence like a fisherman, I have to learn to be patient. It makes it easier because I'm in no hurry to lose more money.

These days I've not had the energy and time to do some quality posts. Why? Usually I blog in the morning. But these days, I'm preoccupied with driving lessons..GRRR! Hopefully it'll all be over soon then I can go back to my usual routine. Life is a series of projects after projects...it gets a little tiring after sometime, don't you think so?

Monday, March 30, 2009

STI and HSI

This is for self reference only.

Below shows the STI index. Poised for a retracement. Possible entry points, 166X, 163X there abouts. I like the 166X support level, as it is the gap support, near to ema 50d support and a trend line coming from June/July last year (touching jan high this year). Could be significant.


The chart below is for HSI. Same pattern as STI.

Sunday, March 29, 2009

The mathematics of effort and results

If you start to value your time, you'll realise that being a perfectionist is a very silly thing to do. Why is that so? Effort is not equal to results. In life, I've seen countless examples of people who seemingly put in minimum effort but reaped maximum benefits. This is also known as working smart, not working hard.

I can't agree more.

While showering, I've derived the mathematics of effort and results. It is actually an exponential graph (I'll spare you the equation because it's the form that matters, not the exactness) which looks something like what I've attached below.


Initially, a little effort will reap a lot of results. However, as more and more effort is piled on top of previous effort, the results increment gets smaller and smaller, until it finally plateaus off. The main idea here is that the results reaped is not exactly linear to the effort that you put in.

Here are some examples that I can imagine:


1. A student gets 40 marks out of 100 for his test. He puts in a 10% more effort, he gets 60 marks out of 100. He puts in another 10% more effort, he gets 70 marks. He puts in another 10%, he gets 75%. To reach 90 marks, he'll have to put in a lot a lot more effort than the initial 10% effort that pushed his grades from 40 marks to 60 marks.

2 A woman had a weight of 70 kg. She tries to jog and her weight drops to 60kg. To lose the next 10 kg, she'll have to run harder and faster than before.


There is a region in which the sweet zone is found - this is where the effort put in is reaping the maximum results before the increment tapers off to a plateau. It's your job to define it and find the balance point yourself. If you value your time, just don't be a perfectionist - the effort that you put in to perfect your act might be better spent on other more value-creating actions.

That being said, there are some activities where maximum effort must be put into before a sizeable result can be observed. But once reached, the result will shoot up exponentially without requiring further effort (as shown below).


This kind of activities require patience and usually involve some kind of leverage on either time or money or both. It is also your duty to find and do such activities and work towards that final exponential increment.

I can think of a few examples too:

1. Trading/investing in the stock market. The initial outlay of effort is tremendous, to say the least, since the 'effort' usually involves financial losses as well. However, once the sweet spot is reached, the results will exponentially increase without you putting in a lot more effort.

2. Setting up a successful business. Key word is 'successful'. The initial time and money used to set it up is discouraging in the early stages of the business, but once it starts to take off, the sky becomes the limit.


Have you been doing your part to allocate your time and effort wisely in order to place a higher value on your life-energy?

Sunday, March 15, 2009

Sunday's rambling

I browsed through Sunday Times today and noticed that there is an article on the low rate of interest provided by financial institutions in Singapore recently, presumably due to the plunging SIBOR rate, again presumably because the world's central banks are cutting their rates to boost the economy.

It's interesting that every politician have a fetish for growth. It's quite impossible to generate growth forever you know. Imagine that a hypothetical bacteria doubles their population every one minute - meaning a growth rate of 100% per min. If this rate goes on forever, we'll be covered by bacteria in maybe a few months? But this will not happen because somewhere along the nice growth rate on paper, there will be a limit to this whole growth process. In the case of the growing bacteria, either they run out of space, or they run out of food, or their toxins emitted kill each other, or all of them at the same time. I guess economic growth is the same too.

I looked at the article and there are suggestions by different people on what is the best place to put your $50,000. Almost all of them suggest at least a small part in equities related instrument, either 'safe' blue chips or a few well diversified funds.

If you ask me, where you are going to put your $50k depends very much on what you intend to do with the $50k. Are you saving up for short term use - like getting a property, a car or marriage within 2-3 years? Are you saving up for your child's education in 25 yrs time? Are you saving up for retirement in 40 yrs time? Basically the longer the time frame, the more you should put into equities related instruments. If now is not the best time to invest, when is it? 2006? 2007? If you need the money in 2-3 yrs time, I'm not so sure what you put into the equities market can be recovered in this time frame. Hence, if you can't afford to lose your capital in the event of pre-matured cash out, then don't put it there.

I'm put most of my money in MMF because of my short term needs (see my post on Budgeting for the near future). However, they are getting lesser and lesser returns (though I must add they are still better than banks' rate), with monthly returns dropping from 0.17% per month in May 2007 to around 0.06% in Feb 2009. This means that the returns per annum dropped from around 2% to 0.7%. I think I'll stop putting money and perhaps draw some out of it. The risk of losing the money in MMF (though low probability) is not worth the 0.06% returns per month I'm getting from it, especially since I'm not going to put it there for the long term.

For those interested, mine is the Phillips MMF. Here's the unit price for year 2009.


Here's the graph plotting for the unit price of Phillips MMF since I started tracking in May 2007. Can you see the shift in gradient starting in 2008?


Friday, March 13, 2009

An epilogue

Today, a pet chinchilla passed away.

In its short life span, it had brought many joys. I asked my gf if she will still have the chinchilla, knowing that it will die at this particular day in advance. She said yes - the joys of having it is so much more than the sorrow that it brings her and so it's worth it.

Life is fragile. It pays well to reflect on who you've been neglecting as you hurdle over life's daily struggle.


Rest in peace, little one, for you'll be in raisin-land with all the other chinchillas.

Thursday, March 12, 2009

Sick of s-shares

Do you know what s-shares stand for?

S-shares stands for stupid shares. Actually they are Singapore listed, China-based companies. What have they done to incur the wrath of investors locally? Let's trace it...


1. All began with Ferrochina. The details are hazy, but it goes more or less like this: Debtors force ferrochina to repay their short term debts, and nobody wants to lend ferrochina money to tide them over. Company declared bankrupt, and shareholders 'dieded'. Suspended from trading.


2. China printing & 'Dying' - this one is comically, though not so funny to shareholders. The husband and wife CEO team from the parent company went runnng. Suspended from trading.


3. Fibrechem – auditors have problems finalizing the trade receivables and cash balances at 31st December 2008. Shares are suspended from trading now.


4. Beauty china – Some party wanted to buy over the shares of the CEO, who is a major shareholder himself, as his stakes take up 38.7% of the total shareholdings. It seems that part of the shares sold by the CEO are due to margin calls - which means that the CEO had pledged his shares to do some borrowings. Suspended.


5. Sino-env - CEO had a company, who pledged his shares in sino-env as a pledge to hedge funds. Now, unable to repay their payment obligations, hedge funds threaten to sell off shares. Might affect the company's solvency and ability to pay off bond holders. Suspended.


6. Oriental century – Subsidiary of Raffles education. This is the most recent case where s-shares are involved. CEO substantially inflated sales and cash balances and had diverted unspecified sums to an interested party. There are fictitious accounting and related records, thus leading everyone to believe that the cash they had were in existence. Raffles education shares, who held 29% of oriental century, are halted from trading now. Oriental century shares are suspended from trading.


So who’s the next one to fall? These incidents reflect very poorly on s-shares because of the lack of good corporate governance. If the statements they published publicly cannot be trusted, nobody can do a proper valuation of the company and determine how strong their financial standing is currently. This will affect investors’ ability to judge for themselves the strength and prospect of a company. It’s a shame that such low quality companies are allowed to be listed in SGX.

I remembered fondly in 2006 that any company with CHINA as their names will do very well as punters bid them up, citing very valid and logical reasons like China being able to decouple from US, China being the next powerhouse etc. It’s great that I didn’t participate much in this orgy, though my sins are equally as bad – I bought some of them on the way down.

I’ve two s-shares currently (I do not consider pac andes as s-shares, since they are not china based companies, more like HK based) – china milk and hongguo. Both reported okay business – still making profits but lesser amounts. Both of them share a common attribute, which is they have excellent cash positions. Now, I would have to wonder if the cash reported are really there or not. It sucks big time to me because I can’t even be sure if there accounts are true!

You know what? I’m sick of s-shares.

Monday, March 09, 2009

Budgeting for the near future

I was trying to determine the big ticket cash outflow in the near future over the weekend. The 3 biggest ticket items are car, property and wedding. I roughly know the first two and set budget for them already, so I need to estimate how much I have to cough out for the wedding.

I started by writing down the names of the guests I wish to invite for the dinner. At last count, there are around 85 people, with maybe another 40 more coming from friends of both parents. This works out to be 125 guests to be invited, or assuming a table capacity of 10 guests, a total of 13 tables. Let’s just raise it up to 16 tables, in case there are extra.

Since there are only a small number of tables, I thought it’ll be better to have a dinner at a high end restaurant rather than be contented with a middle range hotel. That needs to be worked out with my gf. So assuming $1200 per table, I need to fork out $19,200. From what I asked around, the wedding package of bridal gown plus photos/video should cost around $6000. Add to this the cost of the wedding rings/bands, which I budgeted to be at $5000, we’ll have a grand total of $30,200. To be on the safe side, I’ll increase it to $35,000, which is a near 16% markup for conservative budgeting purpose.

For car, my total budget is around $30,000, which I intend to pay 50% as down payment and borrow the rest so as not to over stretch my cash coffer. With this budget, I narrowed down to 2 cars – first is a new Kia picanto, the other is a 2-3 years old Honda jazz. I’m undecided as to which is a better bargain, but that’s not important yet in this planning exercise. I strictly do not want my budget to exceed $35,000. Period. Let’s just use the budget of $35,000 to begin with, and my intention of paying 50% upfront means I have to fork out $17,500.

For property, I intend to get a 600-800k property for investment purpose. Assuming a 30% down payment, I need to raise 180-240k cash for it. This might be a little too big for me to swallow, so I’ll have to look for co-investors to share the down payment and mortgage payment. Still, my budget for property is only 100k, so I either have to find enough people to share the burden or just reduce the size of the property I’m looking out for.


Let’s tally the figures:

1. Car purchase: $17,500 which I’ll need by end 2009
2. Marriage: $35,000 which I’ll need by end 2010
3. Property: $100,000 which I’ll need by around 2010 to 2012

Total: $152,500


Assumptions:

1. I have to pay all the things myself, which is quite a valid assumption for now. My parents are definitely not going to chip in. My wild card here is the contribution from gf and her family. I assumed my wild card doesn’t exist.

2. I heard people saying that I can recover 80% of the wedding banquet expenditure. Since my banquet expenditure is estimated to be $15,300, this means I can recover back $15,360. I rather not bet on it. Let’s just assume that I get nothing back.


Cashflow

Getting the car and the property will increase my monthly expenditure as I need to repay the interest and principal of borrowing. The car should set me back by around $1000 per month (includes everything) while the property should at most set me back by around $1000 per month too, assuming that I have 2 person to share the burden with. That will set me back by $2000 per month, meaning that I have less to save unless my income increases by an equivalent amount too.

Of course, the point of buying a car for me is to increase my income, so even though my expenditure is 1k per month, I might/might not be able to break even/make more. The second thing is about the mortgage for the property loan. Best case is that the rental can more than cover the mortgage, generating cash flow for me. Worst case is that there’s no rental and I have to bleed 1k per month till I exit from the property. I’m totally fine with the worst case scenario. The more likely scenario is that my gf can help to ease my burden for both of the debts I incurred, which up till now I have not considered yet. That will greatly improve my situation and most likely I can retain my savings rate of more than 50% monthly income.


3 yr plan from early 2009 to end 2011

I have enough cash to cover both the car down payment and the marriage, which I’m very glad. This means that till end 2010, I do not need to accelerate my savings (like selling off my stocks to raise cash). I have 2 years – 2009 and 2010 – to save up, which at my current rate of 50k per year, I should be able to accumulate 100k for the property at end 2011. The critical period is from 2010 to 2011, as I might need to accelerate my savings before the property market flies off. However, if the market from 1998 to 2003 is any indication of future trend, there might be a period of consolidation while buyers and sellers fight it out. If that happens, I will have more time to accumulate savings for property. If I purchase the property 3 years later at 2012, I’ll have even more cash to buffer.

Friday, February 27, 2009

Value of time

Time is getting tighter for me these days. I remembered fondly years ago, that I'll have time to walk around shopping malls and have the leisure to stand and stare. I can go jogging around 4pm, or swimming at 1pm - those are the days. Still, to get out of the rat race, this is the little sacrifice one must make to quicken the process a little.

Dream mentioned that I must take time to smell the flowers. I agree fully. If yesterday is a cancelled cheque, tomorrow is a promissory note, then today is cash on hand. While planning for the future is important, I cannot be too blind to the good things happening to me presently. One must be thankful not only for the good things that happened, but more importantly, for the bad things that never happen.


Here's something meaningful:

To realise the value of one year;
Ask a student who has failed a final exam.

To realise the value of one month;
Ask a mother who has given birth to a prematured baby.

To realise the value of one week;
Ask an editor of a weekly newspaper.

To realise the value of one hour;
Ask lovers who are waiting to meet.

To realise the value of one minute;
Ask someone who has missed a train, bus or plane.

To realise the value of one second;
Ask someone who has survivied an accident.

To realise the value of one millisecond;
Ask someone who has won a silver medal in the Olympics.

Thursday, February 26, 2009

My ideas on insurance

As a lay person to insurance, it is not easy to ‘break into’ the knowledge banks of insurance. While I profess that I’m no way near a level where I can tell people what to do with their insurance, at least for now, I understand my own insurance needs and plans – which is the raison d’etre for wanting to know more about insurance.


Let’s just talk about the difference between a whole life plan and a term plan. A whole life plan is an insurance policy where the insured gets a cash value, usually towards the 3rd year of the policy. This cash value will grow in value, and it consists of two parts – the non-guaranteed part (usually projected at 3.75% or 5.75% pa) and another guaranteed part. The whole life insurance plan puts the premium that you pay into a participating fund (par fund for short). This par fund consists of a mix of assets, usually more geared towards bonds (higher percentage) and equities (lower percentage). Back in the heydays of bull markets, insurance policies of olden days project their non-guaranteed returns at a rate of 7-10% (that’s what I heard from others) and the selling point of these policies is the high cash values (as always, compared to fixed or savings accounts in banks) that the insured stands to gain when he cashes it out. I think it didn’t work out too nicely when the insured realized that the actual cash value is so far off the projected returns years down the road.


Well, on paper, anything goes. The best and most sophisticated model might not yield the most accurate predictions. Hence, for me, I never like to look at the non-guaranteed part of the cash value. It’s better to plan your life on not having the non-guaranteed portion than to have a shock in the future. This philosophy of not looking at the non-guaranteed portion of any cash values in policies extends not only to whole life but to other savings plans too. I just never look at the non-guaranteed part of the cash values. Call me a conservative if you wish.


To me, insurance is not about investment. I do not think highly of mixing insurance with investment. Obviously not everyone thinks the same as me, hence it’s crucial to decide how you treat insurance. As KK puts it, are you treating insurance as an expense or as an investment? If you treat it as an expense like me, you’ll want a cheap insurance with maximum coverage in terms of both breadth (i.e. how much coverage) and length (i.e. duration of coverage). You’ll not care for any cash benefits or returns because this is immaterial to your purpose of buying insurance. On the other hand, if you treat insurance as an investment, then you’ll want to worry about how much returns you are getting, and whether the returns are mostly in guaranteed part or non-guaranteed part, the composition of the par fund etc.


There are no bad insurance products, just a mismatch between products and the buyer. If you want to be serious in being financially independent, you’ll have to take responsibility in finding out more about insurance as it’s an integral part of being financially responsible to yourself and your family.


Now, what about term plans? Term plans, firstly, have no cash values to talk about. It’s purely for insurance and the premiums you paid are not put into the par fund to grow it. Hence, the premiums are usually much cheaper (around 4 times cheaper, all else being equal).


I think it’ll be good to list the comparison between term plan and whole life plans here:


Personally, I’m holding 2 whole life policies. One is a traditional whole life policy where the policy will be in-force as long as the premiums are paid. The other is a limited payment whole life plan where the premiums are paid for a period of your choice of 10 yrs, 15 yrs, 20 yrs, 25 yrs etc, but the policy will be in force till you expire (or up to age 100).


The reasons I bought and the reasons I’m holding are quite different. Since the reasons why I bought are less than stellar, let’s talk more about why I’m still holding on to the whole life plans:


1. For the limited payment whole life plan, I like the fact that after a period of 15 years (I chose it), I do not have to pay for the premiums anymore. This will cover me for 100k for the rest of my life, with an additional option to change to an annuity upon hitting a certain age. This means that I will not have to pay for the premiums for this plan when I reached age 45, well before my retirement age. This certainty is well worth the extra premiums I paid for this plan.


2. The limited payment whole life plan will be my base insurance coverage till I expire. I have no intention to convert to an annuity plan nor to cash it out, otherwise I would not have any more coverage. Should I hit any unfortunate event after I cashed out my plan or converted to annuity, my savings will be eroded. This is not something I would want to happen towards the end of my life.


3. The other traditional whole life plan I will have to cut upon hitting retirement. I wonder how I can pay the premiums to keep the policy in force after I stopped working. Hence towards the end of last year, I started to cut the initial 180k coverage to 50k to reduce the premiums paid. Thus, I would have a sum of money ready the moment I decided to cash out this policy.


Having settled my base insurance, I will next work on temporary coverage using term plans. This will start as soon as I start my family. The reasons why I chose term plans are:


1. The term plans is to boost my insurance coverage in case something happens to me, so my dependents will need a sum of money to maintain their current lifestyle. But as my dependents get less dependent on me, I do not need to have such coverage anymore.


2. Ideally, I plan to boost my insurance coverage using term plan, for a period of D+25 years, where D is the year where my last child is born. 25 years should be sufficient time for the last child to earn his/her own keep and hence will no longer be dependent on me. The term plan should also be sufficiently cheaper than whole life plans, so the financial burden will not be too great on me.


The whole idea here is to use a combination of whole life and term plans to achieve exactly the goals you want to achieve for insurance. Limited whole life plan to act as a base insurance coverage, topped with term plans to boost coverage until the dependents get less dependent. Of course, other essentials like hospitalization and surgery (H&S) plans, personal accident (PA) plans and disability income plans are crucial for a well rounded insurance coverage. Perhaps more on those in future posts.

-----------------------------------------------------------
Note that I'm not a qualified financial advisor. I'm just posting my thoughts on it, and I do not advise anyone to follow my own philosophy towards insurance. Do seek the proper advice if you need more help. There is a possibility that the information given here is wrong. Hey, what do you expect from a layperson trying to break into the insurance bank? Gimme a break (literally)

Wednesday, February 18, 2009

Personal finance distilled

You know, I've been reading a lot of books on personal finance. But after reading a great variety of them, you'll get a rough idea of what most of them advocates. I'll attempt to summarise those few pointers that I get from reading all these books (don't ask me which book mentions what, I seriously can't remember).


1. Know your expenses well.

This is very easily said, but hard to follow. I've been tracking my expenses for more than a year already, so everytime I spend money, you'll see me whip out my handphone and key in the amount so that I can tally up to my spreadsheet. Initially I wanted to do it only for a few months as I thought it's quite insane to do this, but after a while, it began to look like a sort of game. Every month, I'll tally up and see how the graph looks like, thus motivating me further.


The graph above shows my own expenses vs income for last year 2008. The difference between the blue (expenses) and the red (income) is my savings. That is extremely motivating for me to see my savings growing more.


2. Pay yourself first

This is more for people with fixed salary. Most books will recommend people to save up a portion of their salary and deduct a fixed percentage of say 30% into another 'untouchable' account. The rest, they can spend it to pay for bills and their monthly expenditures. This is essentially a forced savings, somewhat like CPF, except that you have more say on how much you want to contribute.

For variable income people (like me), what I do is that I'll put into my 'untouchable' account as soon as I have a sizeable amount. For example, if I have more than 1.5k in my bank, I'll put in 1k into that untouchable account. This requires more active managing, because I have to think about the near term cash outflow. I do not ever want to withdraw money out of the untouchable account unless absolutely necessary, so if I didn't plan out properly, I'll run in short term cashflow problems.

This kind of savings is significant. If one takes home a pay of $3,000 and pay himself 30% first, he'll get $10,800 in a year, excluding interest. Do not belittle it. It'll be even more if he pays himself 40% first, amounting to a huge sum of $14,400 in one year.


3. Identify your needs and wants

This comes as a result of first knowing what your expenses are, from step 1. If you do not know how much you spend on what, it's hard to audit your expenses to manage it better. It's important to identify your needs and wants because wants are not necessary.

Usually before I buy something, I'll have an intense desire to get it straightway. There's no point in reasoning out because the reasons will always expand to fill the desire. What I'll do is that I'll cool myself off for a time period, then if I still think I have to do with it, I'll go and buy it. For my accoustic guitar, I've been toying with the idea of buying it for almost 2 years. It cost slightly less than $300. For a CD that I really like, maybe I'll delay buying for up to 6 months or more. If I still like it, I'll get it.

Can you delay your gratifications, sometimes indefinitely? That being said, one must not feel deprived for doing without it. Enough is a balancing point between too much and too little.


4. Understand and manage your debts

Don't get yourself immersed in debts. Certain debts are good and others are bad. If you want to buy a car, but you can't have the money, so you borrow 100% of the amount and pay off in 10 yrs - that's very bad debt. How does one differentiate between good and bad debts?

For me, I classify things into assets or liabilties. Things that allow me to increase my money are my assets. Things that suck in money from me are my liabilities. For example, I would like to buy a car so that I can work harder and faster. With my own sets of wheels, I can save a lot more time, reach places a lot faster and probably squeeze in a few more work. It's more than worth the cost of the payment. Here, I'm borrowing to leverage on time.

For those that depreciate in value (like car or a washing machine), it's not wise to borrow money to pay for it. Some people I know borrow money for renovation, wedding, television sets etc...those are really bad debts.


5. Earn more money

I've seldom read books that tell you this thing. Earning more income is possibly the best way to save (i.e. if you don't spend more to 'reward' yourself too). There's plenty of ways to earn more - do a better job and try to get promoted or teach some skills that you can do very well. Most will probably choose tuition as it's easy and provides a healthy cashflow. With one student, you can possibly bring in an extra $200-$300 in per month, instead of lying in the sofa watching tv on weekends. How about teaching roller blades, cycling, swimming, baking etc?


6. Have adequate insurance

I've known people with less than adequate insurance. There are many insurances one can buy, ranging from:

1. Life insurance (death benefit)
2. Critical illness (like heart attacks, cancers, strokes etc)
3. Hospital and surgical insurance
4. Accident plans (can include things like dengue fever)
5. Elderly care (for those who are old and have problem fulfilling some basic acts of being a healthy independent human being)
6. Disability income (if you can't work because of disability, you'll get an income for a period of time)

Different life stages will require different kinds of coverage. For my life stage, I'll probably need more critical illness, hospital and surgical insurance and perhaps death benefits. The thing about insurance is this: it's equally bad to over insure and to under insure. If one over-insures, he is paying a lot more money than needed for the possibility of a claim event happening. If one under-insures, he have to folk out more money in the event that something happens. Both are equally not optimum. But from what I see, it seems there's less possibility of people being over insured, haha

What's the purpose of insurance? It helps to pass some of the risk to others. Can you afford to pay for $XXX,XXX in the event of cancer striking? If you can't fork out the amount of money, it's better to pay $X,XXX per year for a limited amount of time in order to pass the risk to others. As simple as that.

This issue about insurance deserves an article on its own, so I'll stop here. For now, it's suffice to say that without proper insurance, all the savings you've built up will be wiped out. Such events might be rare, but it's possible and probable. If you've read Black swan theory, it's always these exceptional circumstances that will have significant impact on your lives, so prepare yourself for it.

Wednesday, February 04, 2009

Woe be to those who missed out ROE

I was just waiting for the bus to come when I thought more in depth about the concept of return on equities, otherwise known as ROE for short. It’s not those little things that you put onto sushi though.


WARNING: THIS IS ONE OF THE MOST CHEAM AND LONGEST POST I EVER DID ON ACCOUNTINGS. PROCEED WITH CAUTION.

ROE, usually denoted as a percentage, is defined as the net profits per equities of a company. Equity is the amount that is left when you subtract total liabilities from total assets. In this article, I’ll explore the idea of how difficulty it is to maintain a consistent ROE throughout the years. I figured out an example while waiting for the bus, so I’ll just use that one to illustrate.

Suppose Bullythebear Company (BTB for short) is opening for business. To start off the business, BTB managed to raise $150 from venture capitalist. However, because BTB still needs to buy some fixed asset to kick start the business, it’ll have to borrow $50 from the Kingpin. Being a kind soul, Kingpin do not require any interest to be paid up, so there is no interest charged on the $50. BTB will immediately have a cash/cash equivalent of $200, listed as a component under the assets column. The balance sheet will look somewhat like this:


BTB proceed to buy a piece of machinery (that can be used forever and hence do not need depreciation charges at all) that is used to produce the revenue, costing a princely sum of $120 paid up front without credit. Hence, from the cash/cash equivalent of $200, $120 of which will be used up, leaving $80 (200 – 120 = 80) left. The balance sheet looks like this:


So after the first year of business, BTB made a revenue of $100, and after all the costs and taxes involved, retains a net profit of $52. The $52 will be received immediately and will add to the initial $80 cash, hence the cash/cash equivalent will be raised from $80 to $132 (80+52 = 132). There is a corresponding entry in equity under retained earnings, which is the exact amount as the cash/cash equivalent, being $52. The balance sheet and income statement looks like this:


Let’s do some FA for the company at this present moment.

ROE is 25.74% (52/(150+52) = 25.74%).
Net margins is 52.0% (52/100 = 52%)
Financial leverage is 1.25 ((132+120)/202)
Asset turnover is 0.40 (100/(132+120))

Hey, not bad numbers at all!

Into the second year, BTB manages to raise revenue by 15%, which is pretty decent. Unfortunately, the direct and indirect costs associated with making the revenue also increases proportionately, creating a net profit of $59.80. Again, this sum is collected in full without credit and thus increases both the cash/cash equivalent and the retained earnings. The balance sheet and income statement looks like this:


Take a look at the figures now
Revenue increment: 15%
ROE is 22.84%
Net margins is 52%
Financial leverage is 1.19
Asset turnover is 0.37

Hey, the ROE drop from 25.74% in the first year to 22.84% in the second year, even though the company is pretty decent. The net margin remains the same and the revenue increase by 15%. This is the difficulties that company faces when they want to maintain their ROE – it’s not easy, especially when they hold their retained earnings in cash which is sitting there earning a miserable interest. The more the company earns, the harder it will have to work in order to maintain the same ROE because the asset base increases!

Let’s see what happens in year 3 when there is a great year for our BTB company, with revenue increasing by 29.6%. Here’s the balance sheet and income statement:


Here are the figures:
Revenue increment: 29.6%
ROE is 22.84%
Net margins is 52%
Financial leverage is 1.15
Asset turnover is 0.38

Here, the ROE is maintained at 22.84%, same as the previous year. But look what it takes to achieve this same consistent ROE feat – a revenue increment of nearly 30%. Can you see how hard it is to keep on maintaining the same ROE again and again, year after year? It takes not only good use of the retained earnings, but also great management insight to invest the excess earned every year to good use. It’s not easy at all!

Here's a few insights that I gained by doing this rather rigorous way of exploring how ROE numbers are generated:

1. ROE is very difficult to maintain. Every year, the management will have to decide on how to maintain ROE, which isn't fun at all. Holding too much cash is great, but it'll drag down the ROE. Invest more into their business - what if they can't generate the kind of returns? Management will also have to think about giving back earnings in terms of dividends, especially when they are not confident of using it wisely. The worst they can do is to invest in non-core business for the sake of expanding their empire. It'll drag down ROE, suck up precious cash, and even have to spend money to get out of it eventually.

2. This comes as a surprise actually. I knew it but never really thought hard about it. Financial leverage drops as one gets more and more asset base. This is the result of increasing the asset faster than one's borrowings. Just by retaining cash, the financial leverage ratio drops substantially.

3. I've a much better understanding of the relationships between the 3 statements found in financial reports. I used to do all these accounting in the past (I blogged it an article found here), as part of my journey to learn fundamental analysis, and I remembered I took half a day to do just a simple tracking. This one, I did it in 1 hour. Hey, practise do make prefect - just keep staring and crunching numbers for 1 full year, it'll work wonders.

4. I start to appreciate more when I see companies with high and consistent ROE. Take a look at Hongguo:

----------ROE(%)
2003------19.68
2004------20.49
2005------22.46
2006------22.31
2007------22.30
2008------19.7 (*)

* estimation based on 9M08's ROE

Tuesday, February 03, 2009

Celestial

I’ve got another request by one of the superfriends to do a review on Celestial. I’ve covered Celestial quite some time ago, around end of 2007 I believe, so I think it’s a good time that I revisit this company again and see what had transpired between then and now.

Celestial is in the business of manufacturing soyabean protein-based food and beverage products and is selling them under its own brand name. They are also entering the biodiesel business which began a trial run last Oct 2008.

For this review, I’m only reading their 3QFY08 results, which they released back in November last year. Here’s a few statistics (based on 9MFY08 data):

Net margins: 22.8%
ROE: 25.7%
Annualised diluted EPS (assuming conversion of bonds to shares): SGD 0.14
Current assets/Current liabilities: 1.3
Total assets/Total equities : 1.73
Total liabilities/Total equities: 0.73
PE (based on today’s price of 0.340) = 2.4x

Here are a few things that I noticed and thought about:


1. Net margins are pretty high at 22.8%. However, compared to FY06, their net margins are at 31.9%. Even last year’s net margin was at 23.3%. We are definitely seeing some trends in the erosion of their net profits. I’ll say they are being held hostage by the high prices of soya bean. This can be seen in their Cost of good sold (COGS) as a percentage of their revenue. Since the last time I tracked this, their COGS (as a % of revenue) had increased from 55.7% in FY06, to 61.0% in FY07 and to the present 64.9% for the 9 months into FY08.

This is something that they have not much control on. I’m not sure if they hedge the price of soya beans purchased with something like a commodity futures contract, somewhat like what SIA did to lock in future oil price.


2. Other expenses like distribution costs had also shot up sharply. We’re talking about close to 50% rise in 3Q08. Not sure how they distribute their products, and not sure if it’s linked to oil too. But I do know that Celestial needs to do more to control their costs, which are already eating up their once very healthy net margins.

Considering that their net margins are so easily eroded within a span of 3 years, perhaps they do not have much of an economic moat. That being said, a net margin of 20 % plus is nothing shameful.


3. They have been easing down on their financial leverage since I began tracking it. Their financial leverage (defined as total assets/total equities) went from 2.17 back in FY06 to 1.99 in FY07 to the current 1.73 in FY08. The secured borrowings they had made back in FY07 had been fully paid up, leaving SGD 243 mil unsecured borrowings to be payable within one year or less (as at 30th Sept, 2008). This is from the zero coupon convertible bonds issued on 12th June, 2006, with a maturity of 5 years i.e. 12th June, 2011.

The price of the conversion of the bonds to share was adjusted to $2.47 per share. With the current crisis looming and the low share price of Celestial (last transacted at $0.340), I doubt if many shareholders will want to convert their bonds to shares, especially when the conversion price is like 7+ times more than the current share price.

They mentioned that if the bondholders held on till maturity (i.e. June, 2011), Celestial have to pay 129.263% of the principal amount (S$235 mil) by then. This means that Celestial will have to cough up nearly SGD 303 mil (RMB 1,515 mil) in 2011, assuming none of the bondholders convert to shares. That is a potential time bomb waiting to explode.

They did, however, have cash/cash equivalents of RMB 1,397 mil sitting at their company’s coffers now. It depends on how wisely they plan to use this amount of cash. Spend it foolishly and they will have to borrow more money to repay the bondholders when it approaches 2011. Would it be easier to borrow money then? I do not have the answers.


4. ROE (annualized) for FY08 is an impressive 25.7%. It’ll be more enlightening to look at the breakup of the ROE and tracking it over the years, since I have the data at hand.

------------------Financial leverage-----asset turnover-----net margins-----ROE
FY2006--------------2.17------------------0.38------------------31.9%------------26.3%
FY2007--------------1.99------------------0.52------------------23.3%------------24.1%
FY2008*-------------1.73------------------0.65------------------22.8%------------25.7%

* FY08 figures are estimated on the basis of the figures given in the 9M into the FY08. I assumed a straight trend leading to 4Q08 and the estimation can be wildly off the actual figures


We can see from the breakup of the ROE figures how Celestial improves it’s ROE. It is using less leverage (good sign), churning out more revenues per dollar of assets (good sign) but with lesser net profit margins (bad sign). I’ll say that the quality of their ROE is actually better, even though it’s lower than FY06, because it’s not as highly leveraged.

ROE of above 20% is still impressive, at least to me.


4. Current ratio is good at 1.3x, but I’ve no past figures to guide me on this. But let’s look at the absolute figures. They have RMB 1,971 mil worth of current assets, of which 71% consists of cash/cash equivalents. Assuming a bad debt of 50% on their trade/receivables and zero value on their inventories, their adjusted current assets will stand at RMB 1637 mil, which is more than enough to cover all their total liabilities amounting to RMB 1,532 mil.

I think no worries on their solvency in the near term. Of course, if businesses are affected, there’ll be more bad debts, the liabilities will also shoot up…but that will be anybody’s guess.


5. Operating cashflow which is coming in is good. However, one huge figure worries me, which is the amount of cash that flows out due to their investment in their plant, property and equipment (PPE). For the 9MFY08, cash comes in at RMB 380 mil, but flows out at RMB 470 mil due to investment in their fixed assets, and another RMB 160 mil flows out from financing activities. No wonder they need to issue convertible bonds to raise money. I do not know their plans for expansions in the near term…are they going to invest more money into their PPE? If not, things will go fine and they can even give out some dividends and have some remaining to save up for rainy days.


6. The management seems to have prepared for the eventuality of the bondholders redemption in 2011. They are already planning to look into different re-financing options. More updates on this potential time bomb will be given come FY08 full year results, so they say. Due to this, they also chose not to declare any cash dividends for the FY08 – this means next quarter when they close the results of the year, no hope on getting any dividends. This is a prudent and conservative approach taken by the management to ensure the long term survivability of the company.

The new biodiesel business is in trial period, starting last Oct 2008. They are determining the prospect and strategy for this business, so it’s a good idea not to hope for any positive contribution coming from this new business segment.


7. Ultimately, what to do for Celestial? Invest more to average down? Cut loss and move to supposedly more stable blue chips?

At PE of 2.4X, there’s not much expectations for Celestial based on the current price. I’m still worried about how they are controlling their expenses, which is eroding their margins. I do not think Celestial will be one of those companies that will go belly up, unless something drastic happens to the soya bean industry (look at what the milk scandal did to big players like Sanlu and Mengniu). Do take note of the potential convertible bond redemption coming closer to 2011. If bondholders redeem their monies, Celestial will have to seek new financing to pay them. If bondholders convert to shares (possible, but unlikely), there’ll be around 10% dilution to existing shareholders.

Monday, February 02, 2009

Data pulse

Trying to help out a fellow regarding his investment into this firm, Datapulse. From the books that I read, either this or Datacraft was one of the hotly punted stocks way back in the dot com era. I started browsing through the statements with a skeptical eye, knowing that Datapulse was dealing with those computer, gadgety stuff (they are actually providers of total solution to CD/DVD for content distributors in Asia Pac region). How good can they be. I think I'm wrong.

I only looked at their FY08 results released in 2008, Sept.

Net profit margins: 18.2%
ROE: 16.6%
Current assets/current liabilities: 4.0x
Total assets/Total equities: 1.25
Diluted EPS: 2.25 cents
PE (based on today's price of 0.135): 6x
Dividend yield : 14.8%

Here's my thoughts:

1. They must be doing something right. I thought the kind of business they are doing are so easily replicable and with not much of a competitive edge of others. But take a good look at their impressive net profit margins of 18.2%. This could be one off of course. ROE of 16.6% is pretty impressive too, especially for the kind of business they are doing. Usually for business geared towards manufacturing, I expect to see a rather lower ROE because of the high fixed cost perhaps coupled with high borrowings too. How wrong. Their ROE is hampered somewhat by the high cash/cash equivalents they are holding, but in these times, perhaps this is what prevents them from collapsing.

2. Looking at the current ratio and gearing, it's quite hard for me to see them needing any emergency cash to tide over current liquidity issues. Their current assets (of which 74.5% consists of cash/cash equivalents) can cover their current liabilities for 4 times. They have no problems with longer term debts too, with non-current liabilities consisting only of 24% of total liabilities. If they have no problems with short term liabilities, they wouldn't even have to blink for non-current liabilities.

In fact, their cash/cash equivalents of 45 mil can more than cover total liabilities of 20 mil PLUS dividend of 2 cents to every shares they own (around 11.9 mil) and still have 13.1 mil left over. Hey, do not belittle this penny share ok?

3. Based on the above rough calculation, I would say no problems to them continuing to give dividends in the future, IF they can maintain their business. A big IF, I know. Are they able to do that? I do not have the answers, as I do not have the expertise nor interest in their area of business.

4. Cash flow wise - a clean bill of health. Cash is coming in for sure. In fact, the quality of their recorded earnings are very good. Due to the accrual nature of accounting (and the fact that business give credit), what is recorded as earnings might not materialize as cash, so we might see a case where there is superb earnings but little cash flow. However, Datapulse's earnings are very much translated into cash flow. If we take their net profit of 13 mil, add in the non-cash depreciation charges of 7 mil, we can around 20 mil, which is exactly what their operating cash flow show. No nonsense at all.

The biggest cash flowing out is actually the dividends paid out to shareholders. This drains off around 12 mil from the company's coffer. For FY08, they are spendin a fair bit (5.7 mil) investing in their assets. Not sure what their plans are for the coming year, but I'm sure they won't be putting in so much into their capital expenditure.
In my opinion, no worries in terms of cashflow.

5. Good time to buy? With PE of 6x, dividend yield of 14.8%, low debts, good cashflow to pay off all debts and dividends, it seems not a bad option at all. One of the risk is that we do not know the extent of how the recession will affect the demand, and hence, their business. If business is affected, a lot of things mentioned here will also be affected. Another risk is whether there are better use for the money. Is there a better investment around?

If you treat this as a dividend play, it's not too bad. If they give their dividends of 2 cents per share forever (another big IF), you'll get back your investment capital in around 7 years. Probably faster since this rough calculation ignores capital gain. So if the real question to ask is really how stable their business is. Answer that, and the rest will follow.