Showing posts with label Singpost. Show all posts

Tuesday, September 11, 2012

Singpost's quiet rise

Singpost's shares had been climbing up steadily, but especially so after the announcement of the new thompson mrt line. At least it seems so to me. The volume of the shares transacted daily also rose up appreciably, whereas in the past, this is usually a quiet counter. Out of curiosity, I went to dig up some figures to see how much the postal building at the affected Thomson Road Post Office located at 246T Upper Thomson Road is worth.


From commercial property guru site, a mall shop, 99 yr leasehold located at Upper Thomson Road is selling at $1.5 million for a 31 sq m space (built in). This works out to be around $4.5k psf. The Thomson Road post office is also a leasehold property of 99 yrs (since 31st March 1992), occupying a land area of 2753 sqm and a building floor area of 1793 sq m. Just as a ball park figure, this works out to be around $86 to $130 mil, depending on which area you multiply with the psf figure. The weighted average number of ordinary shares is 1,900 million shares. So if they are going to distribute out all the money from the property transaction, it'll work out to be around $0.045 to $0.068 per share.


Of course, this figure could be way way off, because a lot depends on the fair value of the property, which is hard to determine. I only know the comparative value based on another property which is trying to sell at this price, meaning that the price is not even the actual transacted price. So let's give and take - we'll take 50% of the lowest price of $86 mil, and that works out to be $43 mil and see what's the dividend like. It turns out to be $0.0225 or 2.25 cts per share.


Compared to the usual quarterly distribution of 1.25 cts and final distribution of 2.50 cts, this can be quite a bounty. Is that what people are buying up this quiet counter for?


(You do realise I'm not a qualified surveyor or property guru for that matter. The figures are just numbers plucked from a certain number of key assumptions that may go all wrong. If you buy the counter based on what I wrote here, you're nuts. Either way, the disclaimer at the bottom of the blog applies.)
Tuesday, November 23, 2010

Singpost chart

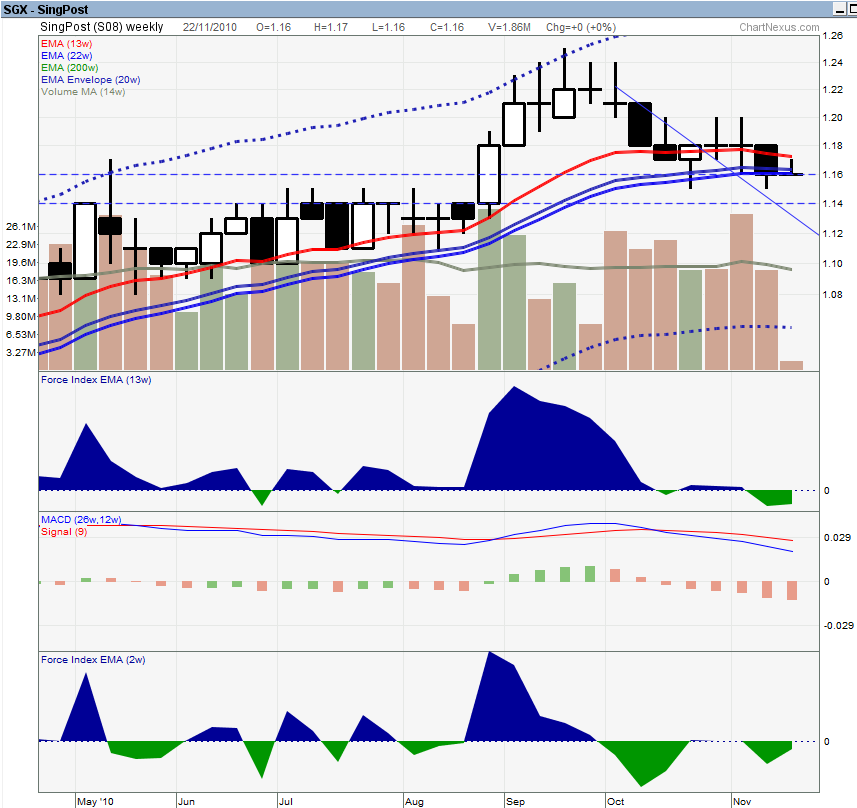
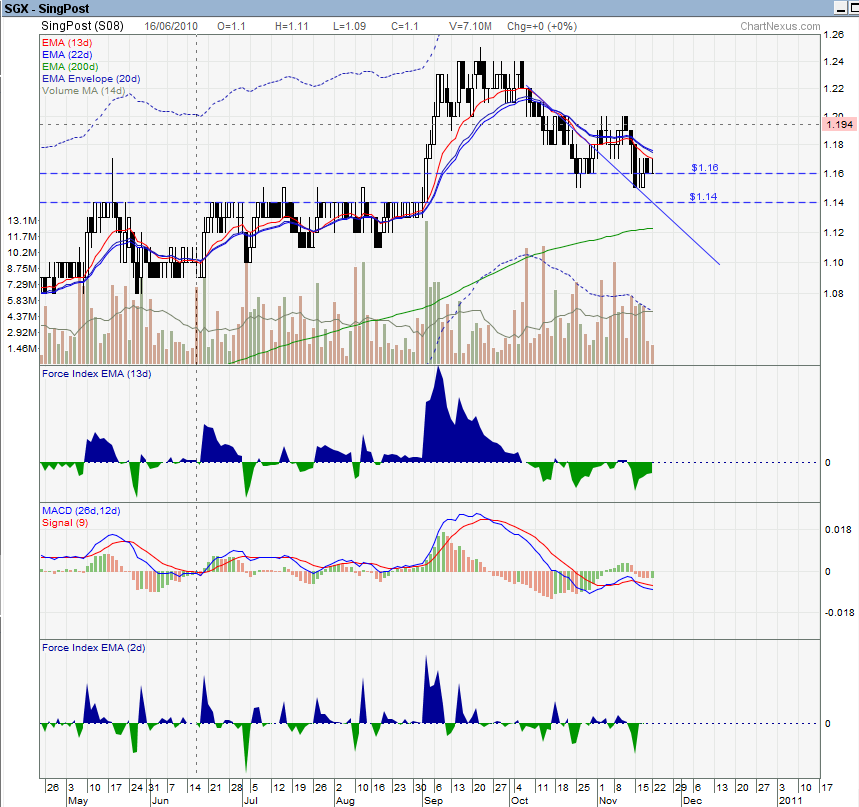
For self reference. Next dividend on Feb. 1.14 - 1.16, 1.20, >5.4

Weekly

Price touching value zone. Long term FI divergence.

Daily

Macd divergence, macd lines divergence, downtrend broken & retested

Tuesday, July 06, 2010

To milk or to slaughter?

Having sold a dividend yielding counter recently, I was thinking about the age-old problems that plagued me. I was suitably reminded of someone's analogy (bro8888's?) that a dividend yielding counter is like a milk cow. Every other time, a milk cow will give off milk, so that you can drink some and sell some, thus giving you a good cash flow. Alternatively, you can sell the milk cow to someone at a good price and get several years worth of 'future' milk money now, so that if there's a mad cow diseases floating around infecting other herds, your future cash stream will be secured because it's in your hands now. This comes at a cost - you'll lose your future cash stream and possibly the price of the milk cow might also increase in the future.


To milk or to sell - that is the question


Quite a good analogy to stocks, no?


The counter I sold recently was singpost. This particular tranche I had held for quite some time - around 3 years in all. I had bought it at a rather high price of $1.18, something that I had regretted for an equally long time. However, I made good on the stocks when I sold it at 1.13, with my dividends covering all my capital losses and making up an 'okay' profit.


The thoughts that ran through my mind was if I should hold on to it longer to get more dividends or should I just sell to lock in my profits to get my hands on cash, and live to fight another day. Here's my reasons for divesting:


1. At 1.18 entry price, I was not doing as good on my yield. Singpost gives quarterly dividends up to a tune of 6.25 cts per annum, thus giving me a yield of 5.3% per annum. Not bad, but not fantastic either, considering other lower geared but higher yielding alternatives out there. Therefore, I was inclined to sell it to get the cash to get into the other alternatives.


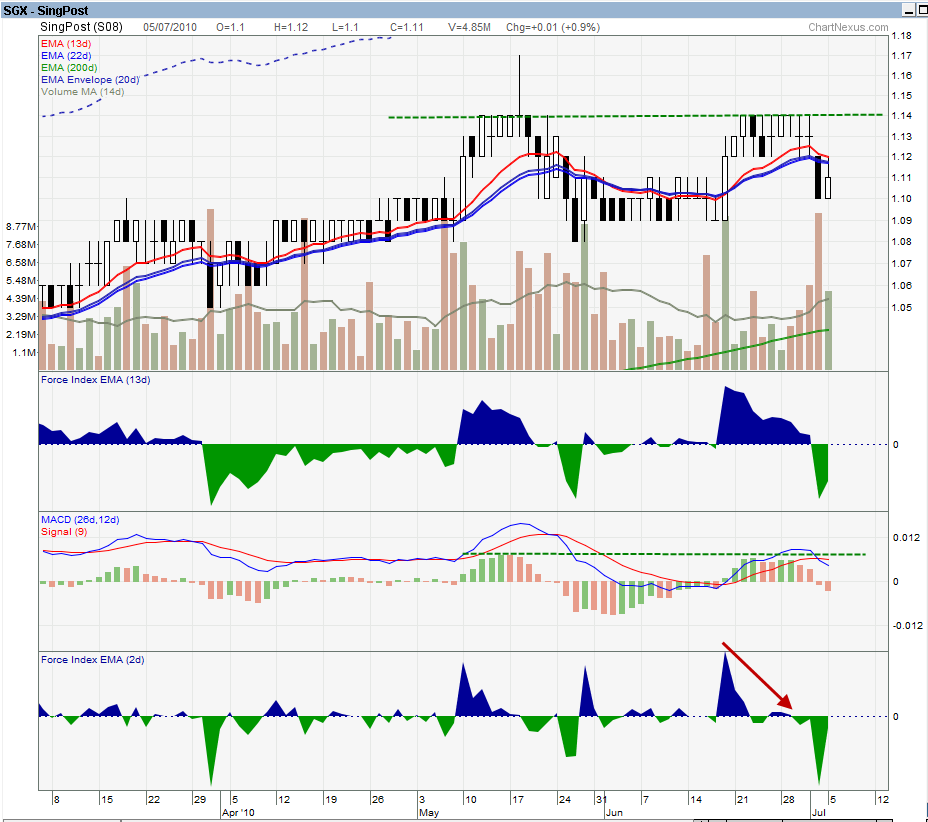
2. A picture tells a thousand words. Let's see what this picture tells you:

Singpost - daily chart

I wanted to sell at 1.14 but after queuing for nearly a week, I couldn't get it done. I just opted for 1.13. This chart was not particularly bearish, but the overall market condition was, so I didn't want to risk what I had out there and just took what I can out of the table. The price dropped due to XD. On hindsight, I could have got the dividend, sell at 1.12 and have both my cake and eat it too. But alas, things are always much clearer after it had happened.


3. I told myself that I would want to 'trade' this counter again, with this as the second round. The time frame for trading this is actually quite long, which is fine for me actually. I'll want to trade it when the signal comes and to hold it for dividend yield when the price reaches around 90 cts level. At 0.90, the yield will be near 7% - that would be something worth holding for.

Friday, January 30, 2009

Singpost 3Q08's result

Singpost announced their 3Q08 results today. As usual, their results are just that...boring. It's not doing exceptionally well, nor terribly bad either. It's just plodding along, so to speak. A few pointers to take note:

1. 3Q08's operating profit falls 1.2% compared to 3Q07. However, if excluding all extraordinary items, the net profit for both 3Q results are nearly the same.

2. Comparing 9M08 to 9M07, the operating profit dropped a little too (0.7%). Again, excluding all extraordinary items, the net profit for 9M08 is a little better, being 7.5% above 9M07. As mentioned, Singpost's result is nothing spectacular but nothing to worry about too.

3. I noticed that for 3Q08, the selling expenses went up nearly twice as much (43.5%). However, the absolute amount is quite insignificant, being just around 4% of the total expenses incurred for the same quarter. It's stated that they provided more in terms of doubtful doubts in view of the bad times. Singpost do need to curb their expenses though. The revenue for this quarter is up 1.6% from the last year, but the expenses expanded by 5.2%. Of course, this naturally dragged down the net profit for the quarter.

4. Diluted EPS for the past 9M08 is 5.891 cents. Today's closing is 77 cts. Thus, the PE is 9.8x based on annualised EPS for the past 9 months. For singpost's standard, this PE is actually quite low already. Still, in this kind of times, sub-10 PE is quite the normal. Maybe even sub-5.


5. Current assets for this quarter is 1.05, compared to 0.90 last quarter. There is an increase in the percentage of cash/cash equivalents over the current assets this quarter. Singpost increased its cash/cash equivalents to current assets from 57% last quarter to the present 62%. Since they do not hold much inventories, quick ratio is pretty irrelevant here. In my opnion, nothing to worry about them being unable to meet short term debts.

6. Long term debts consists of unsecured bonds, expiring on 11th April 2013 with fixed interest rate of 3.13% pa. This bonds actually forms a huge part of their total liabilties (58.3%), so it's important to see how they are able to pay for it when the time comes. There are still 4-5 years more to go before it's due, so I don't think there's a concern about that now.

7. Cash flow from operations are still coming in (a total of 63 mil). I doubt they are going to go into any major investing in their PPE, so net cash should still be positive. The major outflow of cash comes from payment of dividends to shareholders. It's 'bleeding' 24 mil this quarter. Overall, there is around 29 mil of cash entering their coffer this quarter, bringing their total cash/cash equivalent to 131 mil. If they are going to pay a special dividend next quarter (which they normally do, usually to a tune of twice the quarterly dividend i.e. 2.50 cents per share), it'll take away around 48 mil.

Is it likely? I think so. The payment period of their bonds are still far away, and they are still getting in a good cashflow of 60+ mil. Then again, last quarter was the better quarter for Singpost due to the holiday seasons, so 4Q might be slower. Still, there's still a good chance for them to pay special dividends next quarter. Let's see how the situation goes. At least 1.25 cents per quarter is their dividend policy, based on my buy price, I should be 'guaranteed' a yield of at least 4.2% pa.