Showing posts with label Fund manager. Show all posts

Friday, September 21, 2018

The returns of OCBC 5.1% preference shares

I bought the OCBC preference shares, OCC 5.1% NCPS, a while ago for my parent's retirement funds. I didn't even know that OCBC had redeemed back the perp on their first call date until I saw the capital returned to my bank account. Another one bites the dust... So how had it performed? Let's take a look at the details:


1st tranche:

Buy date: 3rd-Feb-2014
A) Buy price: $106.10
B) Quantity: 100 shares
C) Comms paid for buying: $37.19
D) Dividend collected: $2551.40
E) Total profits: 100*B + D - 100*A - C = $1904.21
F) Recall date: 20th Sept 2018
G) Total duration: 4.63 yrs
H) Total % profit: E/(100*A + C)*100 = 17.88%
I) % returns/yr = H/G = 3.86% per annum

2nd tranche:

Buy date: 14-Jan-2015
A) Buy price: $106
B) Quantity: 100 shares
C) Comms paid for buying: $36.30
D) Dividend collected: $2041.39
E) Total profits: 100*B + D - 100*A - C = $1405.09
F) Recall date: 20th Sept 2018
G) Total duration: 3.68 yrs
H) Total % profit: E/(100*A + C)*100 = 13.21%
I) % returns/yr = H/G = 3.58% per annum


I think the returns per annum is pretty decent, especially at those times where the Singapore savings bond is not even available yet. Those are the times when the interest rate is super low. In fact, so low that I am compelled to help my parents because their default action is to put into fixed deposit.

I'm glad I didn't screw it up for them.
Monday, December 12, 2016

Closing off a tranche of LP 'bonds'

I handled my parent's portfolio since end 2013, and I'm still handling them now. Recently, my parents wanted to withdraw out 40k. My parent's portfolio is handled in tranches, according to the timing where they gave a lump sum to me. Since the first tranche of money is 50k, and the portfolio also consisted of Capital mall asia bonds (CapmallA3.8%b220112) that is going to be redeemed back in Jan 2017 (here), I decided to cash out the entire portfolio and return it to them.


When I first started out, the options are pretty limited. I looked back at my older article here on the philosophy behind the allocation. The fixed deposit for foreign banks are giving 1.25% pa for 2 years, while the local banks are giving about 0.55% for the same period. Now, the rates for local fixed deposit for 2 yr is doubled, at 1% pa. For POEMS money market fund (MMF), it was 0.5% pa in end 2013. Now the MMF is giving a return of about 0.9% pa and still rising. You can see the macro environment changing over the last 3 years. There isn't even a singapore saving bonds back then. If it's available, I'll definitely consider putting some money in it since it satisfies the criteria of handling my parent's money, which is a guarantee on capital and also a higher than fixed deposit return.


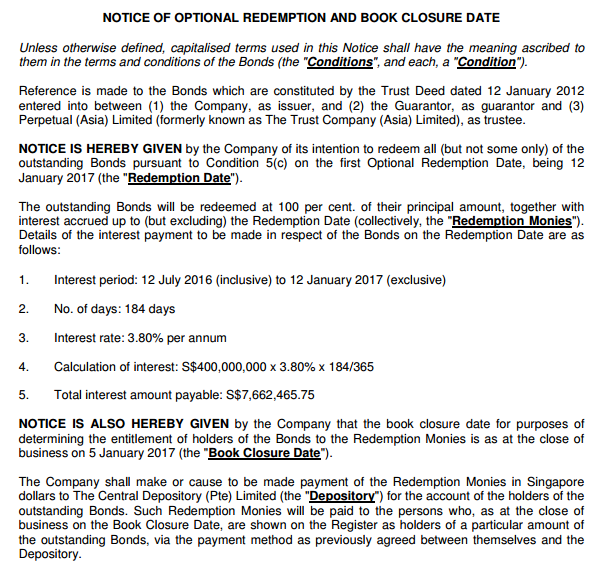
And so I did the allocation of the 50k. The terms are laid out in this post here. I'll summarise the gist of the terms here too. It's like a bond, with a fixed yearly yield of 2% pa, no fixed duration or maturity period, and I will guarantee that their capital will stay intact when they want to cash it out. So the actual instruments I used to achieve this aims can be found in this post here. Mainly it's pref shares from banks and high quality retail bond. There is a change in the portfolio because the pref shares from OCBC bank (OCC 5.1% NCPS 100), was redeemed back in Dec 2015, which I've mentioned in this article here. The portfolio didn't lose money, but it affected the returns because of the unexpected earlier redemption.


I took the money and reinvested in Frasers centerpoint ltd bonds (FCL Trea 3.65% b220522), and that's all the transactions there is until today. Let's see the returns over the 3 year period where I handled the money.


Initial capital: $50,000
Date of inception: 27th Dec 2013

Total brokerage fees in buying/selling: $342.13
Percentage of brokerage to capital invested: 0.68% total or 0.225% pa
Total amount of dividends given out: $2,000
Cash retained in portfolio: $3,881.43

Current value of portfolio (all in): $53,402.43
Total portfolio returns (inclusive of paid dividends): $55,402.43
Date of closing: 12 Jan 2016 (that's when the capital from the redeemed cap mall bonds will be returned)

Absolute profit: $5,402.43
Percentage return: 10.80%
Time period of handling portfolio: 1112 days
Average returns per year: 3.55% pa


That's fantastic, in my own opinion. I beat the Singapore savings bond over the same period of 3 years. Even at their best of 2.78% per year over 10 years (Issued in Nov 2015), their 3 yr average return per year is 1.48%. Their Dec 2016 issue is worse. At 1.87% per year over 10 yrs, their 3 yr average return per year is 1.03%.

Shit, I should just take a cut of 0.7% pa of NAV, as 'management fees' over the last 3 yrs in which I managed my parent's money. I'll get about $1k, and the average returns per year will drop to 2.86 % pa. Still very decent lol!


Reflections:

It had been a very good learning experience for me to start and close off this tranche of investment money. I had to think deeply about the benchmark I want to set, and also the criteria in which my allocation philosophy is based on. In addition, I also have to think about how to set aside the amount I want to distribute out so that I can retain the cash to pay for things like commission and more importantly, to offset any possible losses from early redemption from my parents and also from the inherent capital loss from buying retail bonds at above par value. In between, there is also switching of the portfolio allocation because of redemption by the issuer. I'm glad I didn't lose any money on my parent's behalf!

Tuesday, November 15, 2016

Capitamalls asia bonds optional redemption

Another bond bites the dust.

Don't worry, this is not from the troubled oil and gas sector. It's the optional redemption of Capitamalls asia bonds, CapMallA3.8%b220112 announced from sgx here. I blogged about the bonds here and here.

The full maturity of the bond is actually on 12-Jan-2022 but there is an option for early redemption on 12-Jan-2017 and every year thereafter. Since there is a step up option for the bond  if it is not redeemed on 12-Jan-2017 to 4.5% instead of 3.8%, I guess there's every reason for them to redeem it back in full. The 3 months SIBOR now is 0.87%, about doubled since Jan 2015. I guess I was wrong to think they wouldn't redeem it. There's still another bond out there with 3.08% by Capital Mall Trust (not the same, but yeah) with no step up option and with maturity date in 2020.


How would this affect me?

It wouldn't affect my portfolio because I don't have any more of this bond. But it'll affect my parent's retirement portfolio, to the tune of $26k. Guess what, I'm going to take the redeemed amount and return it back to them. The last time OCBC pref shares redeemed back, I took the money and reinvested back into FCL bonds, but I'm not going to do so now. It would seem that in the very near future, it might be better to put the money in the safety and guarantee of a fixed deposit in the banks, rather than to take that extra bit of interest and risk the price volatility of the bond. Especially if I'm the one guaranteeing their capital.

Nope, going to return them the money. No more reinvestment of the money into bonds for them.

Monday, November 02, 2015

Real investor (in pref shares), real returns!

Real investors, real returns!


I had the honour of handling my parent's retirement portfolio, otherwise known as LP bond fund 1, 2 and 3, starting from around 2013 to the most recent early 2015. In it, I bought several lots of preference shares by OCBC. It's the perp that I blogged about earlier here, paying a coupon yield of 4.2% pa and they are going to be redeemed soon in 2nd December 2015.


One good thing about investing in bonds is that you know the returns and the price before you plonk in your money. In the case of preference shares or perps, it's a little trickier because you don't know when they are going to redeem it back. In other words, unlike bonds with a stated and clear maturity date, perps technically only have an optional first callable date. It happens that for this OCBC pref shares, the first callable date is on 14th July 2013, and thereafter on every dividend payment date, they can choose to redeem it back at a par value of $1.00 per share.


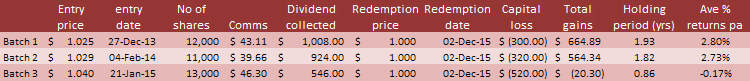
With that, I can calculate exactly how much returns I extracted from the preference shares while holding it. So here's the result:


A few key points:

1. The earliest first batch, invested since 27 Dec 2013 gets the most returns. I got in at a price above par of 1.025, and averaged out over the entire holding period, it gives me an average of 2.80% per year. Very similar to the singapore savings bond, except that the instrument is not out yet in 2013. Back then, it was pretty hard to find a decent retail bond!


2. The second batch, about 1 month later, gets 2.73% pa on average over the holding period. Still okay. I got in at a slightly higher price of 1.029 though. That probably accounted for all the difference in the final total returns.


3. The third batch is the one that I just broke even excluding commissions, and slightly negative after comms. Who would have thought that the issuer will redeem back the preference shares less than 1 yr after I got in? It would minimally need 1.5 yrs before I can make a positive return, and I bet that it wouldn't redeem back within that time. And I lost that bet. The good thing is that it's only a small part of my parent's portfolio, consisting between 17% to 27% in each tranche of the portfolio (I've LP bond 1, 2 and 3). In absolute amount, the loss is $20.30, thankfully. I think the relevant lesson learnt here is that if you want to have a portfolio of preference shares or bonds, it's wise not to put the entire sum into the one with the highest yield, even after accounting for the safety of the issuer company. The reason is that even the safest company may fail. History shows a lot of such blue chips quality company turning blue black. The other reason is that if they redeem it back, then you might have to reinvest again at a point at a point where it's not conducive to do so. That might eat into your returns as well.


So, when they redeemed back the preference shares, I can only hope they will reissue another preference shares. A good quality preference shares by a bank is something that would be suitable for my parents, since their holding period is really just forever.


Now I've to crack my brains to think of where to put in the capital to generate cashflow again. Or maybe I can return back to my parents, haha


Thursday, December 25, 2014

LP bonds 2014 part 2

Here's part 1. There's an important part that I need to remind myself. Most of the holdings are preference shares and bonds listed in SGX. Here are the holdings:


1. OCBC Bk 4.2% NCPS (perpetual, maybe be redeemed after Jul 2013)
2. OCC 5.1% NCPS 100 (maturity 3.7 yrs)
3. DBS Bk 4.7% NCPS 100 (maturity 5.9 yrs)
4. CapMallA3.8%b220112 (maturity 7.1 yrs)
5. CapMallTrb3.08%210220 (maturity 6 yrs)


Since I bought the bonds/pref shares above par value, there will be a guaranteed capital loss if the issuer wants to redeem back the bonds/shares. That's why I need to keep a part of the cash distributed aside for such an eventuality and not distribute it to my parents 100%. How much do I need to keep for LP bonds?


1. LP bond 50k

Guaranteed capital loss from buying above par: $2,588
Cash from holdings per year: $2,144
Cash distributed to parents per year : $1,000
Cash left: $1,144


Balance sheet wise, I will have enough to pay off the guaranteed capital loss from buying the holdings above par value. I just need about 2.5 yrs and I can accumulate enough to pay off this guarantee capital loss. The only problem here is that the issuer might take it back at different times, especially for the OCBC Bk 4.2% NCPS, which is perpetual and which means they can take back it anytime after Jul 2013. If that's the case, I will have to cough out money and also lose this stream of cash. Double whammy. 


In other words, in the next 2.5 yrs, I need to conserve and pay as minimally to my parents as possible. Once I accumulated enough to pay off that $2,588 from buying above par, I'll be safe. Then I can distribute more out to them. Without caring for the perpetual OCBC Bk 4.2%, the shortest time frame I need to accumulate is 3.7 yrs from now. Any other holdings will mature longer than 3.7 yrs (again, except for the ocbc perps). Furthermore, except the two capmall bonds, not all will mature at the time duration stated above. It's just the date at which the issuer can start redeeming back. 


For a good pref shares or bond, you wish they will keep delaying their redemption. The right time to hold such bonds/pref shares is forever.


2. LP bond 60k

Guaranteed capital loss from buying above par: $2,527
Cash from holdings per year: $2,462.40
Cash distributed to parents per year : $1,200
Cash left: $1,262.40


For this, I will need just 2 yrs to accumulate enough to pay off the capital loss from buying above par, should the issuer redeem back the holdings. The good thing is that once I stashed enough money to make sure I have enough to break even without losing any capital, I can distribute out more. How much more? Both LP bonds will be able to distribute 100% cash received from holdings without worrying about the rise or fall of the market price of the holdings, and by extension, the interest rate environment as long as I hold the bond till maturity. That is the single most important part of this strategy, something that bond fund cannot provide me. 


LP bond 50k will thus pay out 4.29% (2144/50000) and LP bond 60k will pay out 4.10% (2462.4/60000). The first bond pays out slightly more because it is started in Jan while the second one starts off in Feb. That one month means I missed out on one payment cycle for one of the bonds. And the mix of holdings are also a little different. Hey, it's still more than doubled of what is giving out now, at 2% pa. 4%+ per annum will be great.


Either that will happen, or the interest rates rise tremendously within 2 to 3 yrs time so much so that the fixed deposit rate will increase beyond 4+%. If that unlikely scenario takes place, then I will close off both funds, take the loss in capital, distribute back to my parents and ask them to invest in fixed deposit. Lagi better, no longer am I the guarantor! Let others take the hit haha :)

Wednesday, December 24, 2014

LP bonds 2014 results

This is the time to distribute coupons for my LP bonds back to my parents. For those who are scratching their heads, here's the prequel for this post.


There are two tranches for the bond:

1. LP bond 50k

Starting capital: 50k
Invested capital (inclusive of comms): $49,773.02
Cash accumulated from payout of holdings: $2,144
Paper gain (loss) from drop in market price of holdings: ($748.02)
Total portfolio gain (loss): $1,395.98
Total portfolio % changes: 2.79%

Going forward, since it's a capital guaranteed bond (by me, of course), I need to retain a certain amount of cash in case my parents need to liquidate it. I'll pay 70% of the net portfolio gain or 2% of 50k (which is $1000), whichever is higher. That should be the policy going forward.

70% of $1,395.98 is $977.19, which is lower than $1000, so I'll just pay out $1k for this tranche.


2. LP bond 60k

Starting capital: 60k
Invested capital (inclusive of comms): $59,699.66
Cash accumulated from payout of holdings: $2184.94
Paper gain (loss) from drop in market price of holdings: ($498.66)
Total portfolio gain (loss) : $1,686.28
Total portfolio % change: 2.81%

Cash payout so far: $600

For this bond, it's a semi-annual payout. I've already distributed $600 in the middle of this year. Going by the same policy of 70% of net portfolio gain or 2% of 60k ($1.2k), whichever is higher,

70% of $1,686.28 = $1,180.40, which is lesser than $1200, so I'll just pay out $1.2k. However, I've already distributed $600 earlier, so this time, it's only another $600.


It's not easy to run a fund that promises a guaranteed payout of a fixed percentage and yet there's capital guaranteed. The returns are not fantastic, but I must remember what the risk profile of my parents are and what are their goals. They initially just wanted to get into a fixed deposit, which pays about 1.2% or 1.3% at that time but I thought they are not doing their money justice. Hence, I offered to do this for them. Hence my benchmark should be the long term fixed deposit rate. As long as I can do better than the fixed deposit rate, I should run it for them, if not, I might as well cash out, have less trouble and not bounded by my own guarantee!


They are still interested to invest with me (another 100k plus minus!), but too bad, closed shop liao. LP guaranteed bonds is officially over! If they want to invest with me, it'll be LP equity fund LOL! Equity funds means bo bao capital, and if the market tanks, they will bear the loss. I need to highlight that to them haha :) For LP bonds, it's low guaranteed returns and capital guaranteed, maybe for LP equity funds, it'll be medium guaranteed returns but no capital guaranteed...see how lah


Wednesday, July 23, 2014

Thoughts after 1/2 yr of managing my parent's money

I recently handed a cheque of $600 to my father. It's his half yearly 'coupon' from buying LP's bond with a principal sum of 60k. It's right on track to deliver 2.5% to 3.0% returns per year. Actually it's more than that, but LP's bond is capital guaranteed, I've to reserve a certain amount of cash paid out in the event of redemption of bonds that I've bought above par value to cover the capital loss.


Ya, I know it's still lower than CPF, but it's hard to achieve this kind of returns in this time and yet also guarantee the capital. Still, it's better than my parent's initial plan of putting their money in fixed deposit earning maybe 1% pa. I'm potentially offering 3 times as much, and I'm glad I did it for them, even though I don't need to.


I heard from my father that another tranche of money is coming in at the end of this year. It's from his endowment plans he put earlier, amounting to about 100k. Not sure if I can offer capital guarantee again because I'm holding quite a big portfolio already from my parents (160k!). I will most likely outsource the risk to others...maybe find a good annuity for them? We'll see how it goes when he gets the fund and perhaps let me know what's his intentions are for that amount of money.


Not a good sign eh?

With their medical fees mostly covered by hospitalization plans, and knowing that they have a sum of money to do what they wanted to do during their retirement phase, having paid up all their housing debts and having their children giving them a monthly allowance to cover their transportation and food bills, I'll be happy to be in their shoes. All in due time I suppose. I'm not expecting to have any inheritance from my parents - they are pretty down to earth folks who had worked hard to get to where they are. They should spend all their money up before they go. At the very least, I'm quite sure they won't be a financial liability to their children. That's already a big plus.


Managing their retirement fund makes me want to have my own retirement funds too. But alas, I've a hefty housing bill to pay, amounting to 1k per month from me, and another 1k from my wife. I'm trying to raise capital that can draw dividends amounting to 1k per month to at least cover my housing contribution. That will greatly relieve my fixed expenses per month. 1k per month for 12 months will be 12k per year. If I have to invest at about 4% to 5%, that'll be about 250k to 300k. If luck is on my side, I should be able to reach that amount in another 3 or maybe 4 years.


That should be my financial goal in the near future. We all have to start somewhere to boost up our passive income. There's a lot of unknowns, but I'm sure I can handle it when I reach there.

Wednesday, January 08, 2014

The allocation of my parent's 50k

On the last day of 2013, I've finished investing all the 50k entrusted to me into the market. I didn't do it irrationally. I've been thinking about it for a few weeks already.


My aim is to invest the 50k for a min of 2% and above, with very good chances of not losing the capital. This is not a growth-dividend portfolio, because I'm guaranteeing the capital. This is also not a high dividend yield portfolio, because I don't need to take the necessary risk to get the 2%, and neither can I guarantee the capital if the market goes down. As such, I'm only putting the money into pref shares/bonds. I choose bonds because as long as I hold till maturity, the ups and down of the price wouldn't affect me. Pref shares because they have a very low volatility; even during the financial crisis, it dropped 20+% but recovered. Most of the time the share prices are range bound. I just need to worry about whether the underlying companies are steady enough and won't go bankrupt throughout the holding period, hence I only pick government-linked companies and banks. Especially banks lol


I've put the money into 4 counters with the respective % (included commission) in brackets:


1. CapMallA3.8%b220112 (10.3%)
2. DBS Bk 4.7% NCPS 100 (42.9%)
3. OCBC Bk 4.2% NCPS (24.6%)
4. OCC 5.1% NCPS 100 (21.3%)
5. Cash (0.8%)

Total: 100%


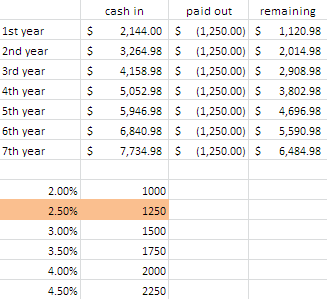
By allocating as such, I'll have a cash flow of $2,144 per year, which is equivalent to a 4.29% portfolio yield, inclusive of commission. I plan to give my parents 2.50% pa, keeping the remaining 1.79% to buffer against the loss of capital when the pref shares and bonds are redeemed at par value when they mature. With this spare cash accumulated over 2 years plus, I can also buffer against a drop in prices of around 10 to 15% (amounting to 2.3k to 4.8k), in case they want to get the money out before maturity and I have to sell below my buy price.


Estimated cash flow. Things will be a bit hairy upon the 5,6 and 7th year as some will be matured. But no point thinking so far ahead. A step at a time.


1. CapMallA3.8% (5 lots, board lot size 1000 shares)

This is the only bond that I have. The maturity date is 8.1 yrs from now, on 12-Jan-2022. There's optional redemption on 12-Jan-2017, 12-Jan-2018, 2019, 2020 and 2021. If they didn't redeem on 2017, then the interest will step up from 3.8% pa to 4.5% pa. It's a good thing if they redeem early, because by then, the higher interest rate environment might offer me more choices of bonds/pref shares that pay a higher yield too. If they don't redeem, I'll get a stepped up interest of 4.5% pa, so it's good too. Capmallasia is just more risky as a company compared to banks, so I only allocate 10% of the portfolio to it.


Do take note that if you buy now, you won't be in time to get the payment on Jan because the counter just went XI. The price, however, also dropped, so the total returns will be a little different from what I've put up in previous posts.


2. DBS 4.7% NCPS (2 lots, board lot size 100 shares)

They can first redeem on 22nd Nov 2020, which is 6.9 yrs from now, but this is an option for the issuers, not a requirement. You'll get 4.7% pa flat while holding.


3. OCBC 4.2% (12 lots, board lot size 1000 shares)

For this one, it's the more risky of the pref shares that I had bought. This is because the optional redemption date is on 14th July 2013, which had long passed. They can have the option to redeem anytime when they give the payments on 4th Jun and 4th Dec every year. Since I bought it above par, if they decide to redeem on the 4th June this year, which is one of their payment dates, I'll lose money. Based on my entry of 1.025, I just need to get 1 full year of interest at $0.042 and I'll be safe. That said, I think the chances of them redeeming on this kind of environment is going to be low. If anything, they shouldn't redeem this. They had already redeemed the higher interest bearing pref shares, so this is one of the lower one. It's a good bet, I think.


4. OCC 5.1% (1 lot, board lot size 100 shares)

For this, there's two interest rate. Before the first optional redemption on 20th Sept 2018 (4.7 yrs from now), the interest is 5.1%, based on $100 share price. If they did not redeem on that date, the interest will be 2.5% + 3mth SOR. Currently, the 3mth SOR is about 0.2 %, and 4.7 yrs from now, it should increase, not decrease. Since I'm happy getting a minimum of 2.5 % + 0.2% = 2.7 % pa, I got this too.


Thursday, December 26, 2013

Issues to think about for portfolio allocation

With other people's money comes great responsibility.


Well, over the last couple of days, I was doing intensive research on the various preference shares, corporate bonds and sg bonds. I decided that I'll just put those funds in fixed income instead of equities so that things are a lot more predictable. I'll have predictability in cash flow and more stability in portfolio value. I'm always thinking that I'm the one who's guaranteeing the money, so I better play it safer. It's always a compromise between yield and risk of loss of capital, so I'll have to balance it to seek the returns that I want.


First of all, after doing a table of all the instruments that I'm looking at, I did a spreadsheet to see how different portfolio allocation can affect the overall yield, the actual cash flow and also the possible gains/losses if there's early redemption (this is really just for preference shares, and most, if not all, are trading above par values). After playing around with the numbers, I have a few sets of portfolio allocations. I initially wanted to settle for one at 5% portfolio yield, but decided not to, because a big part of it will be put in a rather high risk bond (Olam's, if you must know). Before I typed out this article, I really had the intention to follow this portfolio's plan. But I guess I chickened out in the end, so I settled for a more modest portfolio yield of 4%. Still, the 4% per year is still way higher than the 2% that I guaranteed for my parents, so I'll be covered. No point coveting an extra 1%, which is just $500 per year!


Secondly, I have to think about how much to give to my parents. The terms of LP bonds are listed here, and I'll have to hit at least 2%. It'll be good to have a bonus of 0.5% to 1% given to them too. Even giving them 1% more per year, I should have a healthy buffer of cash to pay out in case shit hits the fan on my portfolio. Being able to earn 4% yet guaranteeing only 2% will be my safety margin, but this must not be achieved on potentially higher risk instruments.


Thirdly, I have to stress test the portfolio. I made an important assumption that all the underlying of the bonds, sg bonds or preference shares are not going-concern. If they are, then I won't be able to save it anymore. Therefore, to make this assumption true, I must be rather vigilant at looking at the underlying company for the instrument concerned. 80% of it is to be invested in banks/sg bonds, so I think it should be a pretty good assumption. I'll share more about my portfolio allocation when I'm ready to reveal. I make a 10%, 15% and 20% drop in prices and see if my remaining cash flow that I didn't pay out (after paying out 2% min) is enough to hold it afloat. I figured that I should be able to take a hit of around 10 to 15% losses if suddenly my parents want to liquidate the portfolio and withdraw their principal when the market is not doing well.


With that said and done, I'll just have to wait for the funds to flow into my trading account. After the initial fishing for the best price in the market, I'll just sit and wait for the cash flow. I really don't want to worry too much about this portfolio, nor do too much work for this as it's supposed to be a low fuss portfolio.

Monday, December 23, 2013

LP bonds are oversubscribed!

La Papillion is now officially a fund manager.


I don't know whether this is a good development or not...I'd like to see it as a positive one. Before you start thinking I've joined some fancy company as a employee, nah, I'm not. I've simply the fund manager of my parent's retirement money. This follows my post a week earlier regarding an assignment that my mum tasked me to do. Following some readers comments that I should issue my own LP bond with a fixed rate and a term, I've decided to do it because I think I should confidently be able to beat the fixed deposit rates offered now (around 0.25% to 1.25% pa) and yet also be able to provide them security by guaranteeing that the capital that they had trusted with me will be returned as and when they require. Seems like I've built a certain trust level with my parents because ultimately, the security of the bond is as safe as the issuer - which is me.


The terms of the bond are as follows:

1. Fixed guaranteed yearly interest of 2.0% pa, paid out per year on 1st Jan.

2. No fixed duration, which means it's perpetual until redemption by parents, or liquidation of funds by issuer (i.e. me). Before either can happen, there will need to be at least a 6 months notification to the affected party.

3. Non-guaranteed bonus per year, ranging anything from 0.5% pa to 2.0% pa. This is in addition to the fixed guaranteed yearly interest of 2.0% pa.

4. Capital guaranteed by me after a minimum period of 5 years. If they take out the capital before 5 years, any losses will be born by them. If they take out the capital after 5 years, I'll take the losses if any.


You thought a fund manager will be like this...nah, it's not fun but lots of hardwork


I've 50k at hand here sitting around for a week already, with possibility of another 40k to 100k coming in next year. Wow...I didn't know that they will be sold so easily after presenting to them the different options. However, I didn't do anything for a week so that I can approach this issue with a calm mind. First of all, I didn't know they had squirred quite a sum of money for retirement. This is probably good news for me because it means that I've got 3 layers of defense for any emergency medical fees - insurance under H&S, their retirement money, me and my brother's money. This makes the whole financial burden a lot easier to shoulder. Secondly, I can only guaranteed 50k at this point in time. If they wish to put in a total of 150k, I don't think I can guarantee that kind of sum. Hence, I suggested to them that they evaluate my performance first. If it's satisfactory and most importantly, that I'm confident that I can guarantee both the returns and the safe return of their money, then I'll take it. This is better for them and for myself.


In the coming days, I'll be thinking hard on my portfolio allocation. How much of the money should be allocated to bonds, fixed deposit/cash equivalents, equities etc. If anything, this 50k is even more important than my own 50k because I can lose my own money but I can't lose theirs. 


Now, if only bankers would think like that, we'll have a lot more trust in them.

Monday, December 16, 2013

Where to invest your mum's 50k

Interesting assignment that my mum gave me this morning.


She wanted to put in 50k for her savings to get more returns instead of the usual savings. I think she got this lump sum after her previous fixed deposits expired. She wanted me to look into some instruments where she can get better returns but she don't want to put it into the stock market for fear of eroding her capital. I also won't recommend that she put it into the stock market when I cannot guarantee her capital won't be lost in the process.


Here's what I found out:

1. Firstly, most fixed deposit rates suck. The three local banks are so full of money that they don't even pretend to like more additional funds. Certainly, that's the idea I had when I saw the returns on their timed deposits. The rates are not worth mentioning - better than savings accounts of course, but not much better. Usually foreign banks are more generous, so I looked into that direction but came out disappointed.


2. Certain banks/financial institutions have a special fixed deposits for senior citizens aged above 55 year old. I looked into Hong Leong finance. They have a 1.21% pa for a period of 24 months for people with some bird's nest thrown in as well. That's a notch better than most DBS/POSB, which gave about 0.55% for the same time period. People's bank? Bah. Maybank is not too bad either. For a period of 24 months, you get to have 1.25% pa, slightly better than HL finance and way better than any of the 3 local banks.


I'm still not satisfied though. So I looked into money market funds from POEMS. In it's heyday, it's giving 2% pa which is really a good deal. But that's the time when interest rates overall are high too. Anyway, it's now less than 0.5% pa. For people considering putting in less than 50k in a period of less than 2 years, that still beats fixed deposit rates in most banks considering that the money market fund is so liquid and safe. But no, money market fund isn't going to do for me.


Next, I looked at SG bonds/bills. As safe as the solvency of this government, if you hold the instrument to maturity, you'll be able to get back the capital. The interest, in the form of coupons, are usually given twice a year. I looked at the fundsupermart platform, which charges 0.1% custodian per annum on the coupon payments and also 0.1% for initial processing fees. That's okay, considering how they make life easier for me. I worked out on their calculator for this NX11100X, with a coupon of 2.225% and maturity on 1st June 2021, which is about 7.47 years to maturity.


What I'm concerned is how much I'll get over how much I paid for the instrument, on an annual basis. Based on the estimated amount that I've to pay ($49,829.40), I'll get $1,057.50 per year, spread over two payments (each $528.75) on 1st June and 1st Dec per year until maturity. At the end of 7.47 years on 2021, I'll get back $47,000. My only concern is that the yield will be 2.122% (1,057.5 / 49,829.4 = 2.122%) ; I'll leave the rest of the jargon to academics.


That's a lot better than the fixed deposits that my mum wanted initially, giving a returns of about 70% better and not significantly more risk. In fact, the fixed deposits will also be invested directly into high grade bonds and bills like the one that I'm looking at, so effectively I'm just cutting the middle layer of fees by going semi-direct (direct will be to bid straight from MAS).


Then there's the problem of getting bonds in a low interest rate environment, knowing that the tapering of funds injected into the system will probably slow down or stop in the near future. I reasoned it out that it doesn't matter because any drop in price of the bond when the interest rate increases is of not concern to a investor holding the bond to maturity. Just don't sell it before maturity.


I suggest doing this in stages:

1. First 20k to put into the sg bonds to get a yield of 2.122% pa

2. The remaining 30k to put into 12 or 24 mths fixed deposit with Maybank at 0.95% pa or 1.25% pa respectively

3. After the fixed deposit matures, look at the interest rate environment and decide whether to put in the funds into fixed deposit again or sg bonds. When the interest rate increases, we might be able to get more from either fixed deposit or from the sg bonds.


I'll meet up with my parents and tell them about my plan. Ultimately it's up to them. Knowing them, they will instinctively flock to fixed deposits but I'll have to try to convince them that it's worth taking that extra tiny risk to get almost 70% more returns.